

Affiliate of https://nitter.cf/t.co/im7HXDpxQS "Some people get rich studying artificial intelligence. Me, I make money studying natural stupidity." - Carl Icahn
Summerland, CA
Joined November 2011
- Tweets47K
- Following6.5K
- Followers10.4K
- Likes71.7K




Brrr Infinity Capital retweeted

The beauty of automation is you can trade 16 mediocre strategies instead of attempting to flawlessly execute 1 perfect strategy.
And 16 mediocre can mathematically produce an excellent portfolio.
Sharpe ratio measures how much return you earn for each unit of volatility you take on.
Portfolio Sharpe scales with the square root of independent bets.
Start with a strategy that has a Sharpe of 0.5.
Combine equally risky, uncorrelated strategies with the same Sharpe:
Sharpe * square root (indep bets)
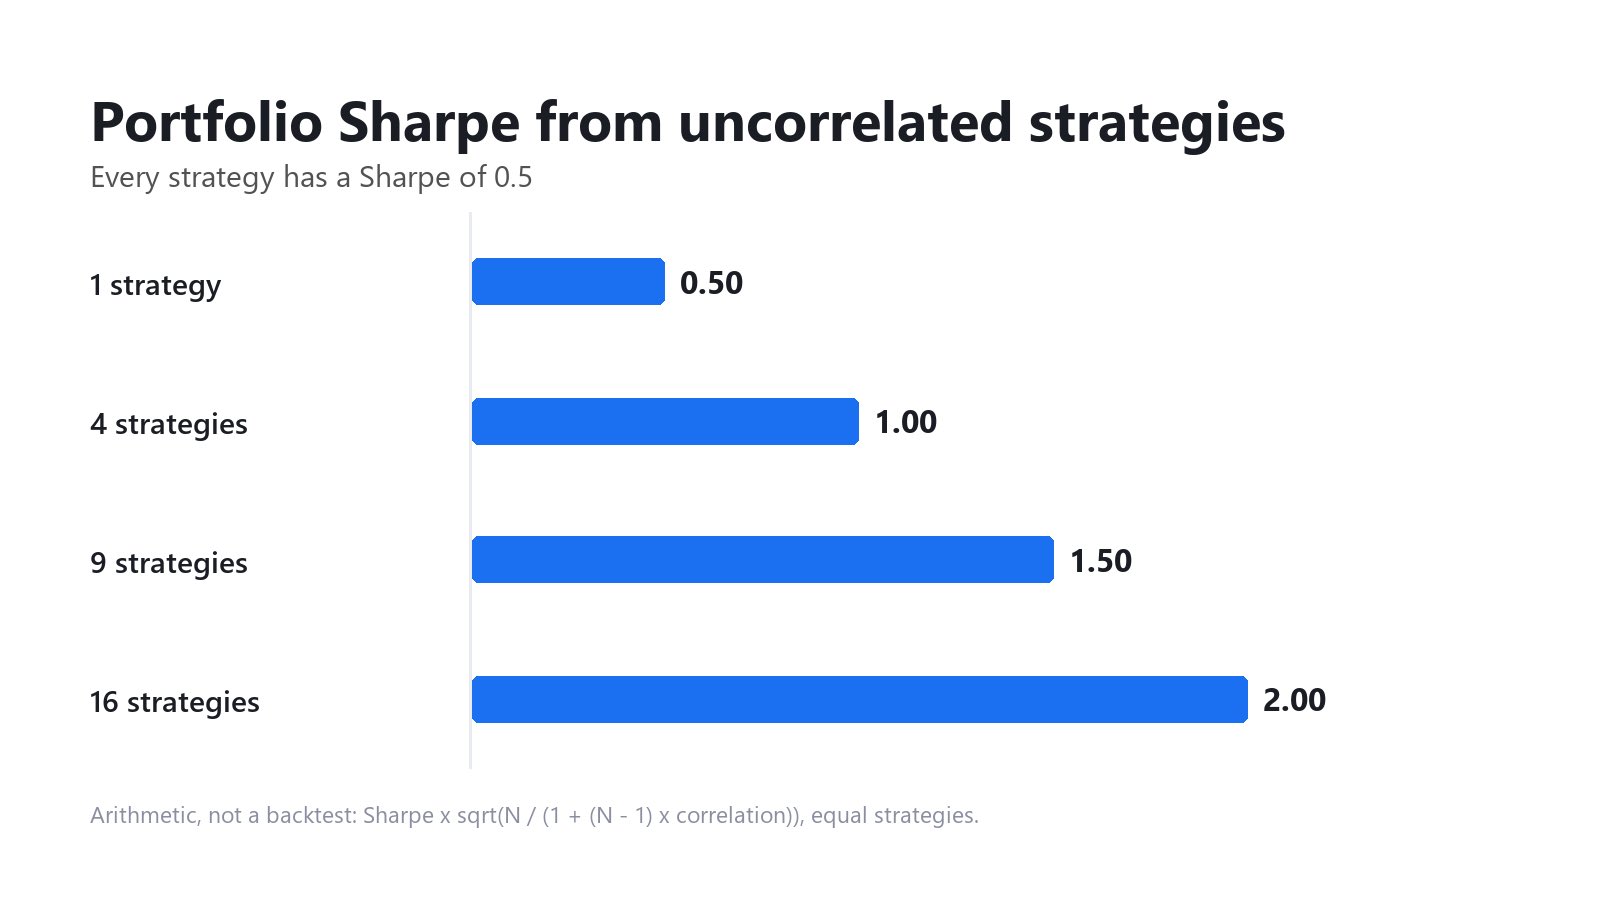
• 1 strategy → Sharpe 0.5
• 4 strategies → Sharpe 1.0
• 9 strategies → Sharpe 1.5
• 16 strategies → Sharpe 2.0
You quadruple risk-adjusted performance without improving a single strategy at 16 strategies.
Stop optimizing the perfect strategy. Start finding strategies that move differently from everything you already trade.
But what does moving from Sharpe 0.5 to 2.0 actually mean?
Assuming 10% annual volatility, a 4.32% risk-free rate, and normally distributed returns:
Sharpe 0.5 → 82% probability of a profitable year.
Sharpe 2.0 → 99% probability of a profitable year.
Brrr Infinity Capital retweeted
Does your strategy survive a slightly unluckier version of its self?
The Variance Test resamples your trades 1,000 times, keeping only equity curves that underperform the backtest.
If the strategy degrades with slightly worse win rate then good thing you found out before it cost you real money.
Build Alpha runs this test automatically and can filter strategies by this result.
For example, accept strategies that have 5% or worse win rate than the backtest but performance degrades no more than 10%. Aka if win rate isn’t what we think how bad can things get and can we live with it?


Brrr Infinity Capital retweeted

Concretum Bands short entry strategy on NQ coded using @buildalpha


Latest @buildalpha was connected to Claude through MCP and a custom python signal for Concretum bands by @ConcretumR was created inside BA. Build alpha simulated various exits and provided this equity graph for NQ long during NY session with probably better stats than original.


Brrr Infinity Capital retweeted

BREAKING: SpaceX raises $44,000,000,000.00 to buy Nvidia AI chips, the largest GPU financing ever.


Brrr Infinity Capital retweeted
Traders argue about daily loss limits and consistency rules.
In my 502-challenge study, neither moved results much.
The payout option did. Same account, same price, same pass rate. But...
Daily payouts: $27,822 per attempt
Flex payouts: $14,971
Nearly 2x from one choice at checkout. So important to TEST EVERYTHING!!

I ran one portfolio of futures strategies through 502 prop firm challenges from 22 different prop firms.
Nothing changed between runs except the challenge.
The big takeaway? Test your trades on the exact prop firm’s rules. It can make a BIG difference in which challenge you should buy.
Here are some of the data findings:
1. Expected net per attempt ranged from +$27,822 to -$2,883
2. The median challenge was worth $2,349, about 1/12 of the best
3. 134 challenges had a higher pass rate than the winner. All paid less
4. Same firm, same account, same price: one payout option paid $27,822, the other $14,971
5. The median $25K account was worth $616. The median $150K was worth $4,270
The best prop firm challenge is not the cheapest, the biggest or the easiest to pass. It is the one that fits your trades.
The Challenge Finder runs this in BA.
Full write-up with charts in the first comment 👇

Brrr Infinity Capital retweeted

So @obsdmd + @bot connector is cracked.
First two images are value chains I plotted out across different thematics, into individual baskets, and breaks down value chains further thereafter. There's thesis level states, status, and written work within each layer. Keep in mind there are +200 individual unique baskets here, took years to do this manual work.
Grok Bot helped me create these two. Then @InterestRateArb reminded me about Obsidian, and after connecting it to Bot, within less than ~5mins, it gave me this, third image.
Whatever I thought about doing, it just one-shotted with barely breaking a sweat so thanks Brrrr.
I will need to refine a few things myself to make this better before handing it off to Obsidian and have it run on auto-pilot forever basically. That's one part of my book basically solved.


Brrr Infinity Capital retweeted
New in Build Alpha: MT5 Data Downloader
One click connects to your MT5 terminal and pulls:
• Your broker’s symbols
• Tick size and point value
• Margin
• Swaps
• Optional tick data and slippage
Test on the same data you will trade. No CSV exports, no manual setup anymore.


Brrr Infinity Capital retweeted
$PANW: "Total revenue for the fiscal fourth quarter 2026 grew 34% year over year to $3.41 billion"

Brrr Infinity Capital retweeted

Most traders say the dollar drives everything: gold, oil, stocks.
I tested it on 21 futures markets at once.
The idea: use the dollar as a driver. What the dollar index did over the last few days becomes the signal to buy or sell another market. One of the 517 dollar signals: the dollar closed lower than the day before.
Claude Code ran the search in Build Alpha through its API. Stock indexes, oil, gold, bonds, currencies, grains and cattle, daily prices from 2005. Each strategy traded all of them the same way, with no tuning per market.
It could mix the dollar with the market's own price, volume, interest rates, the VIX and the calendar.
Then the same search ran on scrambled prices, where no real pattern is left. That measures luck.
About 295 million strategies tested on real prices. I took the best 40. 0 beat luck.
About half of the top strategies used a dollar signal. On scrambled prices, also about half.
On daily prices, the dollar told this search nothing. Next driver: the 10-year note.


Brrr Infinity Capital retweeted
@buildalpha ran one portfolio through 502 prop challenges and ranked them by what one attempt pays after fees.
I ran the same test on my own book. From work, a few commands to Claude Code, and it drove Build Alpha's Prop Firm Simulator through 12 runs.
Four of my strategies on Tradeify Select, five sizes from 25K to 300K, flex and daily payouts, size scaled to the account.
On flex, the 300K paid the most per attempt: $7,002, against $1,326 on the 25K.
Same as his study, though: the top payer wasn't the top passer.
I trade the 25K. It passed most often, 75.7 % against 60.7 %. Its funded accounts lasted longer. And it costs the least up front, $94.50 against $367.50.
Cheaper accounts mean I can run more of them, started at different times, in different market conditions.
Bonus: in my own simulation, a $750 daily profit lock did more than a daily max loss. Median 22 sessions to pass with it, 28 without.
$750 is half the $1,500 target, the 50 % consistency limit. Without the lock, one big day pushes the pass further away.
The right account depends on the trader. And this is a small sample, about a dozen separate market periods. A pattern, not proof.


I ran one portfolio of futures strategies through 502 prop firm challenges from 22 different prop firms.
Nothing changed between runs except the challenge.
The big takeaway? Test your trades on the exact prop firm’s rules. It can make a BIG difference in which challenge you should buy.
Here are some of the data findings:
1. Expected net per attempt ranged from +$27,822 to -$2,883
2. The median challenge was worth $2,349, about 1/12 of the best
3. 134 challenges had a higher pass rate than the winner. All paid less
4. Same firm, same account, same price: one payout option paid $27,822, the other $14,971
5. The median $25K account was worth $616. The median $150K was worth $4,270
The best prop firm challenge is not the cheapest, the biggest or the easiest to pass. It is the one that fits your trades.
The Challenge Finder runs this in BA.
Full write-up with charts in the first comment 👇
Brrr Infinity Capital retweeted
This is incredible stuff! Finally traders can make data driven decisions in the prop space🦾

@buildalpha ran one portfolio through 502 prop challenges and ranked them by what one attempt pays after fees.
I ran the same test on my own book. From work, a few commands to Claude Code, and it drove Build Alpha's Prop Firm Simulator through 12 runs.
Four of my strategies on Tradeify Select, five sizes from 25K to 300K, flex and daily payouts, size scaled to the account.
On flex, the 300K paid the most per attempt: $7,002, against $1,326 on the 25K.
Same as his study, though: the top payer wasn't the top passer.
I trade the 25K. It passed most often, 75.7 % against 60.7 %. Its funded accounts lasted longer. And it costs the least up front, $94.50 against $367.50.
Cheaper accounts mean I can run more of them, started at different times, in different market conditions.
Bonus: in my own simulation, a $750 daily profit lock did more than a daily max loss. Median 22 sessions to pass with it, 28 without.
$750 is half the $1,500 target, the 50 % consistency limit. Without the lock, one big day pushes the pass further away.
The right account depends on the trader. And this is a small sample, about a dozen separate market periods. A pattern, not proof.


Brrr Infinity Capital retweeted

Rare to see data on prop firms
I ran one portfolio of futures strategies through 502 prop firm challenges from 22 different prop firms.
Nothing changed between runs except the challenge.
The big takeaway? Test your trades on the exact prop firm’s rules. It can make a BIG difference in which challenge you should buy.
Here are some of the data findings:
1. Expected net per attempt ranged from +$27,822 to -$2,883
2. The median challenge was worth $2,349, about 1/12 of the best
3. 134 challenges had a higher pass rate than the winner. All paid less
4. Same firm, same account, same price: one payout option paid $27,822, the other $14,971
5. The median $25K account was worth $616. The median $150K was worth $4,270
The best prop firm challenge is not the cheapest, the biggest or the easiest to pass. It is the one that fits your trades.
The Challenge Finder runs this in BA.
Full write-up with charts in the first comment 👇