
Credit | Ex-L/S, PE https://nitter.cf/t.co/zt4wcXrfRq https://nitter.cf/t.co/dVpl14Nel2
Joined June 2018
- Tweets11.5K
- Following1.5K
- Followers11.3K
- Likes6K




Pinned Tweet
1/
I believe $ENR.de could generate 20B EBITDA in in 2030, which puts the stock at 6x 2030 EBITA and 4x after FCF.
Siemens Energy: The Art of the Possible newmooncap.substack.com/p/si…
Well. I like to quote @John_Hempton 's quote on Charlie: If you mix turds and raisins, you still have turds.
In this case, its turds and turds, so you a bigger turd.

My 2 cents:
$NBIS and $IREN should merge. Together they'd be a real challenger to the hyperscalers, and far better positioned to handle the headwinds both are facing.
$NBIS needs $IREN's power and land. $IREN needs $NBIS's software ecosystem. Each has exactly what the other is missing.
This is a 1+1>2 deal.
@danroberts0101 @romanchernin @mvcinvesting @Jason @MB_Hogan @nebiusai @IREN_Ltd
4
1,107
Solid math. Bid the stock up

My 2030 price target for $NBIS is $3,000.
Here’s the math.
Nebius expects to deploy at least 5 GW of active compute capacity by 2030.
And the economics keep improving:
• Annual revenue per MW was previously around $10M.
• Long-term contracts now exceed $25M per MW.
• Short-term contracts can generate $40–50M per MW.
And the trend is accelerating.
The gap between AI compute supply and demand is expected to widen for at least another 18–24 months.
For 2030, I’m using a conservative assumption of $25M in annual revenue per MW.
5,000 MW × $25M = $125B in annual revenue.
Now look at profitability.
AWS currently operates at approximately 40% operating margins, suggesting a net margin of roughly 30%.
For Nebius, I’m assuming a 25% net margin at scale.
$125B revenue × 25% = $31.25B in annual net income.
And 2030 is not the finish line.
Management expects to add at least 1.5–2 GW of additional compute capacity every year.
On a 5 GW base, that represents 30–40% annual capacity growth.
A company generating more than $31B in annual profits while expanding its capacity at that rate commands a premium valuation.
I’m applying a 30x P/E multiple.
$31.25B × 30 = approximately $940B in market capitalization.
I’m also accounting for roughly 25% additional share dilution by 2030, reflecting the enormous capital investment required to support this expansion.
The result?
A $3,000 price target for $NBIS by 2030.
Nearly $1 trillion in market capitalization.
And a business that could still be expanding its compute capacity by 30–40% annually.
$3,000 per share is not a fantasy. It’s what the numbers point to.


OpenAI goes after Apple Pay and Google Pay -
"We’re introducing ChatGPT Wallet, setting a new bar for secure payments by agents. It’s the first wallet that lets agents pay without access to users’ actual card details and that requires a security check for every purchase, while also preserving existing card rewards and protections for eligible disputes. Built in partnership with American Express, Mastercard, and Visa"
Haiz. $NBIS bull won 1 over me. I covered too early and left money on the table.
1
2
1,497
Shit man. $nbis must be so glad they get to buy the stock cheaper each everyday. as WB says you should be happy if the stock goes down
1
983
Mistake i made here is to cover too early.

Look $nbis bull. You like to boast the $25+/mw and 100% prepayment. Both wont last and if u just
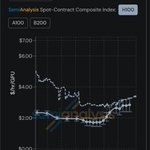
model through fy30 using cons numbers. stock px depends on exit multiple, which is dependent on the $/mw u assume forward. If pricing falls like how h100 did. The stock is done.
559

Look $nbis bull. You like to boast the $25+/mw and 100% prepayment. Both wont last and if u just
model through fy30 using cons numbers. stock px depends on exit multiple, which is dependent on the $/mw u assume forward. If pricing falls like how h100 did. The stock is done.
Dont give me the shit that pricing goes up forever. It makes 0 sense when we have enough lps supply coming up. Also, why should $nbis be earning 70% adj. ebitda margin in 2031
1
5
1,478


Such a ridiculous take.
1) is not a fact. Its just cope. So if she stays ?
2) it always about terminal value and not this 5 year.
3) Neoclouds impt to $nvda? You sure? Why would they fund the "circular demand" vs buying back own shares.

$IREN, $NBIS, $CRWV: Nvidia Temporary CEO Against Neoclouds? Sorting out the FUD.
On first glance this might seem bad, but a few key facts here:
1. She's temporary and they will get a real CEO soon. No way she she's accepted by the Taiwanese supply chain bosses if she and Jensen had beef. She's not going to last more than 6 months if she tries to become permanent.
2. IREN, NBIS, CRWV don't need any more Nvidia funding. Actually IREN built that they have today without any Nvidia funding besides those warrants which aren't even used yet.
3. With all the hyperscalers ramping up their ASICs at full force, Neoclouds are more important to Nvidia than ever.
4. The Neoclouds that get actually get impacted are Nscale, Firmus, and low quality Neoclouds that are a waste of money for Nvidia anyways. Will clean up the ecosystem and prevent the low quality Neoclouds from idling GPUs.
1
2
2,665
