

Personal Opinions | Executive
Harare, Zimbabwe
Joined March 2020
- Tweets7.9K
- Following2.1K
- Followers7K
- Likes6.2K



Pinned Tweet
INDEX UP 63%, MARKET UP 2%: THE ZSE RALLY THAT ISN’T
The Zimbabwe Stock Exchange All Share Index rose 63% between 31 December 2025 and 11 September 2026, while the combined value of the shares it measures (Market Cap) increased only 2.42%.
Our latest report examines the gap and finds a rally concentrated in two months and four counters, alongside significant changes to the market itself. Five companies left the board, removing 21.59% of December’s value, while CBZ and FBC generated 182% of the board’s third-quarter gain.
The evidence suggests that the headline index performance, which tells only one part of the story, needs to be read alongside market composition, concentration and liquidity.
Download the full article from the link below:
lnkd.in/p/dKwje4kK

Valuation models, where earnings are discounted back to the present, will over estimate the value of the equity in the firm.
Source: Aswath Damodaran, Discounted Cash Flow Valuation, slide 93

Closed at $1.81 today.

We initiate coverage of Innscor Africa Limited with a 12-month target price of $1.72, implying 32% upside from the current VFEX price of $1.30.
DCF values Beverage & Light Manufacturing Segment at $0.43/share (33.5% of VFEX price)
Full report below.
linkedin.com/posts/sylvester…

Sylvester Mupanduki retweeted

“I was 25 and the leading fund manager in Zimbabwe. In the ZSE’s heyday, more than 25 brokers rang me every day…”
Investor and former fund manager Ritesh Anand writes on why the iconic Zimbabwe Stock Exchange is in decline, and what to do about it
newzwire.live/opinion-ritesh…

Sylvester Mupanduki retweeted

Thinking of buying the Amalgamated Brands IPO? Read this first.
AB is a good-looking company. But a good company and a good price are two different questions.
I went through the prospectus and ran the numbers. Here’s what stood out. 👇 View article

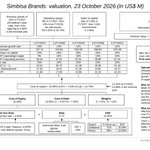
Our Simbisa Brands forecast assumes a Zimbabwe-led group that sustains its FY2022–FY2026 operating record. Revenue grows from US$367.2m in FY2026 to US$670.4m by FY2031, while EBIT after tax rises from US$29.5m in FY2027 to US$51.5m.
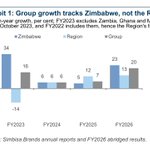
Zimbabwe’s revenue grew 16% annually over FY2022–FY2026. We carry that rate into FY2027, then moderate growth to 12% through FY2031, in line with the Group’s five-year historical rate as slower growth in the Region weighs on the consolidated outcome.
The long-term constraint is economic growth. World Bank projections put Zimbabwe’s real GDP growth at 4.12% annually over 2027–2030 and 4.26% over 2031–2040, slowing to 3.6% by 2050. Our forecast therefore transitions from above-economy growth to a 4.60% perpetual rate.
Full report: lnkd.in/p/dm3USRaX

Simbisa Brands’ share price rose 46% in 2026, adding US$126.9m to market capitalization. My valuation puts fair value at US$0.43 per share, 40% below the US$0.72 market price.


If the Lobels contract is renewed, my estimated value rises from US$0.20 to US$0.27 a share.

This is an estimate of value for Amalgamated Brands Limited, not a forecast of where the shares will trade. After Admission, sentiment, momentum and comparables, not cash flows, will set the price.
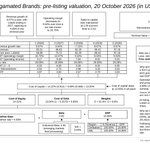
The prospectus puts the implied enterprise value at US$66m, 6.3 times FY2025 proforma EBITDA of US$10.47m. On the pre-Offer share count, net asset value per ordinary share at 31 December 2025, excluding preference shares, is 15.2 cents, and my value before the Offer, with 31 December 2025 cash and no Offer proceeds, is US$0.19.
Estimated post offer value per share, including net offer proceed, is $0.20 against the proposed issue price of $0.35. The downside risks are UNICEF's proposed restrictions, and price competition from Innscor, National Foods and Varun. This is not an investment advice.

This is an estimate of value for Amalgamated Brands Limited, not a forecast of where the shares will trade. After Admission, sentiment, momentum and comparables, not cash flows, will set the price.
The prospectus puts the implied enterprise value at US$66m, 6.3 times FY2025 proforma EBITDA of US$10.47m. On the pre-Offer share count, net asset value per ordinary share at 31 December 2025, excluding preference shares, is 15.2 cents, and my value before the Offer, with 31 December 2025 cash and no Offer proceeds, is US$0.19.
Estimated post offer value per share, including net offer proceed, is $0.20 against the proposed issue price of $0.35. The downside risks are UNICEF's proposed restrictions, and price competition from Innscor, National Foods and Varun. This is not an investment advice.
A good business can still be overpriced. The trick is knowing when you’re buying the cash flows and when you’re buying the story. The market, of course, loves a good story.
Hamutereri ka?
Rights issue yeUS$20 million yaenda kwakaenda mvura yemuchirimo. Vakuru vakati; Murombo haarove chine nguwo; kana akarova, chinenge chaonda kare.
Investors paid in expecting the US$20 million rights issue to revive a corpse, they waited, and at some point they thought their luck had turned, but the kill was already skin and bone.
Now the company is being delisted with no way out for the people who put money in. They are locked in the kraal with a cow that has gone dry: they cannot milk it and they cannot sell it. Everything they put in has gone the way of a dry season shower, and before long nobody will even remember it fell.
In a September article in The Herald, I noted that although OK Zimbabwe had successfully raised $20 million through a rights issue, the capital injection alone does not guarantee a successful turnaround. The paragraph that quoted me started with “However,” indicating that my comment was presented in contrast to what the writer had previously said about the company’s situation. I also cautioned that the underlying issues are so big that the normalization process will take time. Now it looks like l was right, things have actually gone from bad to worse.
The full article is provided below.
heraldonline.co.zw/


Sylvester Mupanduki retweeted

This week we take a look at the Zimbabwe stock exchange many of the points made in this video have been highlighted well by @SMRI_Institute and @its_hot_o
Full clip: youtu.be/8IqpB5Ewa3U
@BgoniJustin would love your thoughts.
@ShareholderView @harveylb_ shoutout!

In June I valued TN CyberTech (ZSE: TNCI) at 51.84 ZiG cents conservative and 120.47 ZiG cents base case, while it traded at 13.37c.
It now sits at 85c, a gain of about 536% in 4 months.


This is a follow-up to my July 2025 report in The Zimbabwe Independent, which put ZSE Holdings at US$2.5m to US$3m against a US$13.5m listing tag.
FY2025 came in at the base case, with revenue up 5% and an operating loss after impairment. H1 2026 changed the picture, with revenue up 37% to $4.85m, a 37% operating margin and $2.27m of cash. My model now puts intrinsic value at $9.3m, or 9.1 US cents a share.
Full report linked below.
lnkd.in/p/d7CU7JtH

Sylvester Mupanduki retweeted

Glad to see the ZSEHolding valuation above the listing value of $13m to 16.8m USD equivalent. We thought some of the analysis at the listing were unfair . The shoe is on the side so we know like other listed companies, the key is delivering value to shareholders and let the market understand what we do
Sylvester Mupanduki retweeted

The quiet exit: why Zimbabwe’s companies are leaving the stock market, and what the public is paid on the way out thezimbabwefinancialmail.com…

A ruler measures things. If a ruler is re-marked so that a two-metre table reads four metres, the table has not grown. Only the ruler has changed. VFEX just re-marked its ruler, which is the market cap formula: share price × number of shares. The table is Old Mutual.
On 13 August, Old Mutual closed at US$0.8028, with a market cap of US$50.96 million. That was measured on the roughly 65 million shares on the Zimbabwe register. On 14 August, it closed at US$0.8385, with a market cap of US$3.77 billion. That was measured on all 4.498 billion shares issued globally. The price rose 4.45% and the market cap +7 300%. As a result, VFEX's total market cap went from US$4.08 billion to US$7.81 billion in one day, and Old Mutual's re-measurement accounted for US$3.72 billion of that US$3.73 billion jump. Today, VFEX stands at US$8.23 billion, with Old Mutual alone making up US$4.08 billion, or 49.5% of the exchange.
Same company. A price up 12.86% since 13 August, against a market cap up +7,800%. Same shares available to Zimbabwean investors. The market did not grow. The ruler that measure the market did. The reform is fair for showing Old Mutual's true global size. But it adds no investors, no trading and no capital. A larger reported market is not a deeper market.
aedsafrica.com/the-quiet-exi…

Now ZiG0.55/share or US$0.021/share at the official rate of 26.69, an 83% gain from its ZiG0.30/share closing price or US$9.011 on 1 September 2026 (21 days).
The ZSE headline index performance needs to be read alongside market composition, concentration and liquidity.
@zim_now_zw
zimbabwenow.co.zw/articles/2…