

Crypto Researcher on All Chains | L1, L2, L3 & Coin Expert.. building @Velvet_Capital
enjoy research? ⏎ Highlights
Joined June 2009
- Tweets39K
- Following2.1K
- Followers51.1K
- Likes96.4K



THEDEFIPLUG retweeted
A prediction market can have millions of dollars in liquidity and still depend on the quality of a single piece of offchain information.
I think the economics of verifying that information are becoming increasingly attractive.
Consider the latest figures from Cournot Protocol as of November 19:
➤ $1.41B in notional market value influenced
➤ 25,106 resolutions
➤ 99.80% reported resolution accuracy
➤ Under 8 minutes in median resolution time
Cournot recently partnered with @primus_labs to introduce verifiable web evidence into its reasoning infrastructure.
Imagine a prediction market with $10M at stake on whether the Federal Reserve cuts interest rates at its next meeting.
Once the decision is announced, someone has to establish what happened.
But there are several questions to consider:
1. Did the information come directly from the Federal Reserve?
2. Was the information retrieved at the appropriate time?
4. Was the original data manipulated?
5. Does the announcement satisfy the market’s resolution criteria?
Primus uses zkTLS to cryptographically verify the authenticity of web data. Cournot then interprets that evidence against the market’s rules to produce an auditable judgment.
Of course, proving that information came from a particular website doesn’t necessarily prove that the information itself is correct.
But it gives participants a much better foundation for examining and disputing a decision.
What I particularly like about this partnership is that the commercial applications extend well beyond prediction markets.
Private credit, insurance and trade finance are all industries where substantial amounts of capital change hands based on information originating outside a blockchain.
As more of these financial activities move onchain, I suspect there will be considerable demand for infrastructure that can authenticate the information determining who gets paid.
There is a lot of money to be made facilitating bets.
There might also be a very profitable business in establishing who actually won.

THEDEFIPLUG retweeted
The next $100B of onchain credit probably doesn’t come from traders borrowing more stablecoins against ETH.
It comes from financing actual economic activity.
That’s the shift I’m interested in.
For most of DeFi’s life, credit growth has been dominated by crypto-native demand:
➤ Leveraged trading
➤ Looping
➤ Yield farming
➤ Basis trades
➤ Treasury management inside crypto itself
That was good enough to build the first generation of lending markets.
It is probably not enough to build the next one.
———
If onchain credit is going to become materially larger, I think the next wave of borrowing demand has to come from outside the closed loop of crypto speculators lending to crypto speculators.
The more interesting borrower categories are:
➤ Securities-backed loans
➤ Commodity financing
➤ Mortgage credit
➤ Corporate working capital
➤ Consumer lending
➤ Trade finance
➤ Institutional fund financing
This is why the recent direction of the market matters.
Jupiter is proposing a tokenized equity lending market.
Injective is highlighting growth in tokenized assets.
Those developments are important not because they instantly create a $100B market, but because they point toward a very different kind of borrower.
Not a trader trying to lever a volatile token.
➤ A business trying to finance inventory.
➤ A fund trying to borrow against securities.
➤ A lender trying to fund consumer credit.
➤ A company trying to smooth working capital.
That is a much larger addressable market.
The research question is straightforward:
Which DeFi infrastructure is actually positioned to intermediate that demand?
The obvious candidates are Aave, Morpho, Maple, Kamino, Jupiter Lend and Centrifuge.
But they are not all competing for the same opportunity.
➤ @Aave and @Morpho look increasingly relevant for large-scale collateralized lending.
➤ @Maplefinance is already closer to the institutional credit trade.
➤ @Kamino has shown how fast product-market fit can develop when real collateral demand emerges in a strong ecosystem.
➤ Jupiter Lend could become a very interesting bridge between tokenized equities and borrow demand.
➤ @Centrifuge has spent years pushing credit and real-world asset infrastructure in a direction the broader market may finally be ready to appreciate.
The big idea is that onchain credit becomes much more interesting when the borrower is financing something that exists outside crypto.
That changes the ceiling.
ETH-backed leverage is reflexive.
Real economic borrowing is expansive.
One mostly recycles existing crypto collateral.
The other can pull entirely new credit demand onchain.
That doesn’t mean this transition happens smoothly.
➤ Legal structure matters.
➤ Collateral enforcement matters.
➤ Identity matters.
➤ Underwriting matters.
➤ Liquidity matters.
And most importantly, tokenized assets need to become financeable, not merely tradable.
A tokenized stock is interesting.
A tokenized stock that can be borrowed against at scale is a business.
That is the difference.
———
So when I ask where the next $100B of onchain credit comes from, I’m not making a forecast.
I’m describing the research direction.
If DeFi wants to become a serious credit system, it probably has to lend less to people chasing coins and more to businesses financing reality.

THEDEFIPLUG retweeted
One feature of @primus_labs social-payment infrastructure I hadn’t fully appreciated is the treatment of unclaimed funds.
Ordinary crypto transfers are generally irreversible once they’ve settled.
But what happens when you’re sending funds to a social identity rather than directly to a wallet?
Primus documents a different payment structure.
1/ The sender allocates tokens to a supported online identity.
2/ The recipient authenticates control of that identity.
3/ The recipient claims the allocated funds through a wallet.
4/ If the funds remain unclaimed for 30 days, the documented fund-contract version allows the sender to initiate a refund.
That fourth step changes the payment experience.
Imagine a project allocating $5,000 across 100 community contributors.
If 20 contributors never claim their $50 payments, the project could potentially recover $1,000 after the applicable claim period.
Compare that with sending funds directly to inactive wallet addresses.
The project may have no way of recovering those transfers.
Of course, this isn’t equivalent to reversing a payment that somebody has already claimed.
And the exact recovery conditions need to be checked against the deployed product version.
But I think the mechanism has a particularly strong application in community distributions and creator compensation.
Projects often need to pay people identified by their contributions on different internet platforms.
Collecting wallet addresses manually adds another layer of coordination.
Primus provides a way to associate those payments with existing identities while introducing a defined claim process.
The appeal isn’t simply making crypto payments easier to initiate.
It’s making certain forms of payment distribution easier to manage afterward.

THEDEFIPLUG retweeted
The AI bull market is creating an enormous headache for crypto.
Anthropic is preparing to raise over $80B this week.
> IPO pricing: Nov 18
> Trading debut: Nov 19
> Price range: $70–$78
> Strategic private investment: $26B
> Estimated net proceeds: $84.6B
Where does the marginal dollar come from?
If institutional investors want exposure to Anthropic and are already fully invested, they have to sell something else.
That doesn’t necessarily mean Bitcoin, but crypto is competing for the same capital.
I want AI stocks and my shitcoins to go up together.
For that to happen sustainably, we need more fiat credit creation.
Both casinos need more money at the tables.


THEDEFIPLUG retweeted

1/ As the industry matures, the next winners in RWA are those capable of transforming them into accessible, liquid & capital-efficient financial primitives.
Ofc asset availability is the foundation, and with ~1.55k tokenised assets @Mantle_Official has already made a strong headstart on that front.
But the next frontier lies in distribution, composability, & financialisation.
And throughout 2026, Mantle has quietly positioned itself as an under-appreciated beneficiary of this transition.
Particularly through its CeFi x DeFi convergence strategy, where its close relationship w/ @Bybit_Official provides a distribution advantage that few other ecosystems can replicate.
As we approach EOY here’s a throwback to Mantle's 2026 progress & why I believe it's uniquely positioned to capitalise on the next RWA phase 🧵


Monday blues aren't that blue after all.
Tokenized assets on Mantle just set a new all-time high at 1,555, up 85% since August, per @blockworksres.
More assets, fewer borders, for anyone, anywhere.
THEDEFIPLUG retweeted

The Infrastructure Behind the Growing Onchain Economy
Onchain markets are expanding beyond simple token transfers into a broader financial ecosystem involving trading, lending, tokenised assets and automated financial operations.
This growth is creating demand for infrastructure that supports economic modelling, token distribution, liquidity formation and ongoing financial management.
Behind this development is an emerging ecosystem of platforms addressing different stages of building and operating onchain economies.
Here’s how the infrastructure works, which projects are contributing and where the ecosystem is heading.
—
● Understanding the Onchain Infrastructure Stack
Onchain economies depend on four interconnected layers:
* Economic design and validation: Modelling token supply, incentives and economic behaviour.
* Token creation and distribution: Issuing assets, fundraising and managing allocations.
* Liquidity and market formation: Establishing trading markets and price discovery.
* Financial operations: Managing treasuries, vesting, governance and ecosystem incentives.
—
● Economic Design and Simulation
Every token economy begins with decisions around supply, allocations, vesting, emissions and incentives.
@machinationsIo provides economic modelling and simulation tools for testing token flows and incentive structures.
@TokenomicsCOM provides tokenomics design and advisory services.
Tecommons approaches economic design through systems engineering and sustainable cryptoeconomic mechanisms.
@KenomicAI is developing infrastructure connecting economic design and validation with token deployment and ongoing management.
These platforms help teams evaluate economic structures before introducing them into live markets.
—
● Token Creation and Distribution
Once an economic model is established, projects need mechanisms to issue assets, raise capital and distribute tokens.
@FjordFoundry provides token sale infrastructure, including Liquidity Bootstrapping Pools. @Pumpfun uses bonding curves for token launches and price discovery, while @MetaDAOProjec applies futarchy to connect prediction markets with governance decisions.
@hedgeyFinance provides programmable token vesting, investor lockups and scheduled distributions.
These mechanisms influence token allocation, circulating supply and the timing of unlocks, all of which can affect market behaviour after launch.
—
● Liquidity and Market Formation
Token distribution creates ownership, but liquidity enables assets to trade.
@Uniswap provides automated market-making infrastructure through liquidity pools and concentrated liquidity.
@RaydiumProtocol supports trading and liquidity across Solana, while @MeteoraAG offers different liquidity pool mechanisms. @AerodromeFi serves the Base ecosystem, and @Balancer supports configurable liquidity pools with different asset weights.
Liquidity depth and token unlock schedules influence trading efficiency and market stability.
—
● Treasury Management and Onchain Operations
Projects also need infrastructure to manage treasury assets, contributor payments, grants and governance.
@Safe provides smart accounts and multisignature controls for shared assets. @0xCoinshift offers treasury management tools, while Tally and @AragonProject provide governance and organisational infrastructure.
@HedgeyFinance also supports ongoing vesting and token distributions.
These platforms help organisations coordinate financial operations through programmable approvals and execution.
—
● How the Infrastructure Layers Connect.
The interaction between these layers creates a continuous economic cycle.
Economic design → Validation → Token distribution → Liquidity formation → Financial operations → Ecosystem growth
As more projects move onchain, demand for infrastructure grows across the entire lifecycle of digital assets.
However, unsustainable incentives, concentrated ownership, fragmented liquidity and weak treasury controls can undermine this growth.
—
● What Could Shape the Next Phase of Onchain Infrastructure?
The opportunity extends beyond token launches to the infrastructure supporting entire digital economies.
Several factors will influence its development:
* Economic sustainability: Maintaining participation without excessive token emissions.
* Liquidity fragmentation: Accessing sufficient market depth across chains.
* Security: Protecting smart contracts and treasury operations.
* Interoperability: Connecting different infrastructure providers.
* Adoption: Moving from product availability to real-world usage.
Ultimately, the next phase of onchain development will depend on how effectively these systems connect economic design, asset distribution, liquidity and financial management.
The infrastructure supporting digital economies could become just as important as the applications built on top of them.

THEDEFIPLUG retweeted
Modern life can feel like being in a sci-fi story—all that is missing is the aliens. They probably won’t appear in 2027. Here are ten other things to watch out for bit.ly/3UCxXw9
Illustration: Cleon Peterson

THEDEFIPLUG retweeted
Its obvious how the the competitive landscape of crypto neobanking is gradually shifting from user acquisition towards user retention + stickiness.
@ether_fi's Cash product is a pretty good example of this.
As highlighted by @glasscade_xyz, Etherfi Cash has surpassed $1B in cumulative card spending, w/ 12.6M+ transactions across 199 countries.
But what caught my attention wasn't necessarily the headline volume, it was the underlying growth dynamics.
Between April <> October:
🔹 Active addresses grew 67.5%
🔹 Transactions per address increased 31.5%
🔹 Average transaction size declined slightly by 2%
In other words, growth hasn't simply been driven by users making larger purchases, but by more people using the card more frequently.
And IMO, frequency of usage is one of the more encouraging early indicators of product stickiness.
Ofc, perks like cashback, rewards + promotional incentives are fantastic magnets for onboarding users.
But these are relatively easy for competitors to replicate, and incentives alone rarely create lasting loyalty.
The real challenge is getting users to stay even when the incentives become less attractive.
And that ultimately comes down to less tangible factors particularly trust, reliability, convenience + the overall user experience.
Does the card work consistently? Is funding seamless? Can users confidently keep meaningful balances in the app? Does the product keep pace w/ changing consumer expectations, security standards + regulatory requirements?
These might sound like basic considerations, but they're precisely what separates a promotional spending product from something users genuinely depend on.
This is also why Etherfi's recent moves are particularly interesting.
1. The @zealwallet acquisition creates another avenue for onboarding existing crypto card users.
2. The @moonpay integration aims to simplify funding + reduce friction between traditional banking rails and onchain balances.
3. Etherfi USD, built through Ethena Whitelabel could eventually make holding funds within the ecosystem more economically productive for the platform.
Individually, these are useful product developments.
Collectively, they point towards a much bigger ambition in making Etherfi a place where users don't just spend money, but actually keep + manage it.
And that's where I think the real competitive moat begins to form.
Because once a financial product becomes embedded in someone's everyday habits, switching becomes less about chasing an extra percentage point of cashback and more about whether the alternative is worth disrupting an experience they already trust.
Ofc transaction frequency alone doesn't prove long-term retention, and the impact of these new integrations remains to be seen.
But the direction is encouraging.
Perks attract users, while product experience builds habits, and trust keeps them around.
IMO, the winners of crypto neobanking won't necessarily be those offering the most generous incentives, but those that can consistently deliver a financial experience people are comfortable relying on every day.
That's a much harder moat to replicate.
Feel free to take a read at this research article for more in-depth insights 👇


THEDEFIPLUG retweeted
Crypto venture funding hasn’t disappeared. But the money is becoming extremely concentrated.
Over the 30 days ending November 12, approximately $1.84B was raised across 63 crypto funding rounds, according to DefiLlama.
Here’s the surprising part:
Kalshi alone raised $1B, accounting for roughly 54% of the total.
So I wouldn’t interpret the headline as a broad recovery in crypto venture funding.
The more revealing question is where the remaining capital is going.
Looking through the recent deals, three categories stand out.
1. Regulated trading and real-world assets
Some of the more notable raises:
> Kalshi: $1B at a $40B valuation
> Index Industries: $50M seed
> Alta: $47.5M Series A
> Uranium Digital: $16.5M Series A
> Marble: $11M seed
These companies are approaching financial infrastructure from different directions.
Kalshi is expanding from prediction markets into a broader derivatives exchange.
Index Industries is developing a tradable benchmark for U.S. residential property prices.
Uranium Digital wants to modernize physical uranium trading and settlement using blockchain-based ownership records.
Alta is building institutional blockchain infrastructure around privacy, compliance, and financial transactions.
What’s notable is that these businesses aren’t simply trying to bring existing assets onchain.
They’re trying to build the infrastructure through which those assets can be traded, financed, and settled.
The potential revenue opportunities are in execution, financing, data, and asset servicing.
2. Institutional insurance and risk transfer
Soter Insure also expanded its Series B financing, bringing in SC Ventures and SBI alongside investors including Galaxy, Coinbase Ventures, Franklin Templeton, and Brevan Howard Digital.
The latest investment amount wasn’t disclosed.
But I find this category particularly compelling.
As institutions increase their exposure to digital assets, they also need protection against theft, smart contract failures, validator slashing, and operational losses.
Insurance is one of the less discussed parts of institutional crypto adoption.
Yet it could become an important business as more capital moves onchain.
The companies underwriting these risks may have a different economic profile from the protocols generating the activity.
3. AI agents and commercial infrastructure
DECA Labs raised $12M to develop infrastructure for agent-led software commercialization.
Marble is also building financing products for AI compute operators alongside its institutional trading business.
Different approaches, but both are targeting commercial activities that require capital, distribution, and financial infrastructure.
I think that’s a more concrete investment direction than assuming every AI agent needs its own token.
What This Means?
The $1.84B headline looks impressive, but the concentration is important.
One company absorbed more than half the disclosed funding, and the remaining deals span very different businesses.
There are still L1 and infrastructure raises, so this isn’t a complete abandonment of traditional crypto sectors.
But the selection of projects suggests investors are increasingly interested in businesses that can earn fees from financial activity rather than relying entirely on token appreciation.
For 2027, I’d pay particular attention to three potential revenue pools:
Trading and settlement infrastructure, institutional risk underwriting, and financing for new asset classes.
None of these raises guarantees that the businesses will succeed.
And private-market valuations don’t automatically translate into returns for publicly traded tokens.
Still, I find the direction of capital allocation revealing.
Crypto investors are funding more of the businesses that make financial markets function, not just the assets traded inside them.

THEDEFIPLUG retweeted
Even after the recent market selloff, millions are still flowing into stablecoin yield markets.
Some pools are offering 6–9% APY while pulling in fresh capital.
8 from DeFiLlama’s top 50 by 7d net inflows:
1. August $USDC V2 | @Monad
8.95% APY | +$4.35M inflows
7.57% base + 1.38% rewards
2. @saturn_credit $USDC | @Monad
8.63% APY | +$2.82M inflows
7.74% base + 0.89% rewards
3. @SteakhouseFi $USDG Pro | @Arbitrum
8.81% APY | +$23.93M inflows
3.76% base + 5.05% rewards
4. @SteakhouseFi High Yield $USDC | @Ethereum
7.70% APY | +$4.95M inflows
5. Clearstar cbAssets $USDC | @Base
6.45% APY | +$2.48M inflows
5.02% base + 1.44% rewards
6. @wintermute_t $USDC Select | @Ethereum
6.20% APY | +$3.48M inflows
6.15% base + 0.05% rewards
7. @wintermute_t $USDT Select | @Ethereum
6.16% APY | +$2.58M inflows
8. @0xfluid $USDC | @Ethereum
6.05% APY | +$7.35M inflows
Personally like the August and Saturn setups here, both showing over 7.5% base yield without needing much from incentives.
Wintermute $USDC at 6.15% base also looks pretty decent for parking stables.
Pretty good options for anyone sitting in cash waiting for the market to recover.

THEDEFIPLUG retweeted
➥ RNT Protocol: Making Real Estate Work as DeFi Collateral
Imagine an investor holding $10,000 worth of tokenized real estate who suddenly needs $4,000 for a business opportunity.
Selling the investment would mean giving up exposure to the property. But what if that investor could access liquidity without selling?
This is the problem @rntprotocol is addressing through RNT Lend, a Polygon based lending market that allows holders of eligible real estate security tokens to borrow stablecoins against their investments.
—
How It Works in Practice
Consider the investor with $10,000 in eligible real estate security tokens.
Instead of selling, they can deposit those tokens into RNT Lend as collateral and borrow USDT or USDC.
Under the protocol’s 75% maximum loan to value ratio, the collateral could support borrowing of up to $7,500, subject to available liquidity and the applicable lending conditions.
In this example, borrowing $4,000 would represent a 40% loan to value ratio.
The investor gets access to liquidity while retaining exposure to the underlying property investment. However, the collateral remains at risk if the loan becomes undercollateralized.
—
Where Does the Liquidity Come From?
RNT Lend connects two groups through its lending pools:
▸ Borrowers: Deposit eligible real estate security tokens as collateral and borrow USDT or USDC.
▸ Liquidity providers: Supply stablecoins to the lending pools and earn interest from borrowers.
▸ Smart contracts: Handle borrowing, variable interest rates and collateral liquidation using Aave V3-based infrastructure.
Interest paid by borrowers flows to liquidity suppliers, with rates changing according to pool utilization.
—
What the Numbers Reveal
RNT Lend’s dashboard currently reports:
▸ Total market size: $31.17M
▸ Total value locked: $21.58M
▸ Total borrowed: $9.59M
These figures show an active lending market connecting tokenized real estate collateral with stablecoin liquidity.
—
What This Changes for Real Estate
Traditional real estate investments can be difficult to use when immediate liquidity is needed.
RNT Lend introduces another option by allowing eligible property-backed tokens to participate in DeFi lending.
Instead of treating tokenized real estate purely as a representation of property ownership, the protocol gives those assets a role within an onchain credit market.
There are still risks to consider, including collateral valuation, smart contract vulnerabilities, borrowing costs and liquidation if collateral requirements are breached.
But the broader development is clear: tokenized real estate can serve a purpose beyond ownership representation.
RNT Protocol is connecting property backed investments with onchain liquidity, bringing real world assets into the lending side of DeFi.
Explore the lending market: lend.rnt.finance


RNT Protocol Is Connecting Real Estate With DeFi Lending
Real estate has traditionally been difficult to use as collateral for accessing immediate liquidity. Tokenization is beginning to change this by allowing property-backed investment assets to participate in blockchain-based financial markets.
@rntprotocol is applying this model through RNT Lend, a Polygon based lending market that allows holders of eligible real estate security tokens to borrow stablecoins against their assets.
Built on Aave V3 technology and approved through Aave governance, the platform combines established DeFi lending infrastructure with real world asset collateral.
RNT Lend reports a total market size exceeding $30M, connecting tokenized property investments with stablecoin liquidity.
—
How RNT Lend Connects Property With Liquidity
The model connects real estate investors seeking liquidity with users supplying stablecoins.
▸ Real estate investors: Holders of eligible property security tokens can deposit them as collateral to borrow USDT or USDC without necessarily selling their underlying investments.
▸ Liquidity providers: Stablecoin suppliers provide capital to the lending pools and earn interest generated by borrowers.
Using Aave V3 lending technology, RNT Lend incorporates established borrowing, interest rate and liquidation mechanisms while bringing tokenized real estate into its collateral structure.
—
The Economics Behind RNT Lend
The platform’s lending model creates a direct relationship between borrowing demand and supplier returns.
Borrowers pay interest on outstanding loans, while suppliers earn a share of that interest. On Polygon, interest accrues with every block, approximately every few seconds.
RNT Lend’s dashboard has displayed the following supply APYs:
▸ USDT: 10.76% APY
▸ USDC: 10.92% APY
These are variable rates that fluctuate with pool utilization and borrowing demand, rather than guaranteed returns.
The platform’s reported market size exceeds $30M, with supplied liquidity and outstanding borrowing representing separate measures of activity.
—
What Could Shape Its Growth?
The development of property-backed lending will depend on three important factors:
▸ Collateral reliability: Accurate property valuations and sound liquidation mechanisms are essential to managing lending risk.
▸ Borrowing demand: Consistent demand determines how effectively supplied stablecoins are utilized and how much interest suppliers can earn.
▸ Liquidity: Suppliers need sufficient available liquidity, while borrowers need access to capital when required.
Although Aave V3 provides established lending infrastructure, smart contract, collateral and liquidity risks remain.
RNT Protocol demonstrates how tokenized real estate can move beyond digital ownership representation and become useful within decentralized financial markets.
By allowing property-backed assets to support stablecoin borrowing, RNT Lend connects real world investments with onchain credit while creating an interest-generating opportunity for liquidity suppliers.
Its longer term development will depend on sustained borrowing activity, reliable collateral management and the ability to maintain liquidity as the market grows.

THEDEFIPLUG retweeted
A stablecoin issuer could launch a cryptographically verifiable reserve dashboard in under 7 days, without building the infrastructure itself.
That’s the business model @primus_labs is introducing through its managed Proof-of-Reserves (PoR) product.
Essentially, turning cryptographic verification into a recurring B2B subscription service.
Primus’s public PoR documentation describes:
➤ Integration targeted at under 7 days
➤ 7 days of free dashboard publishing
➤ A dedicated public reserve dashboard
➤ Monthly subscription pricing after the trial
➤ Managed verification and ongoing maintenance
So instead of a stablecoin issuer having to assemble its own cryptographic reporting infrastructure, Primus offers the reporting workflow as a service.
● What the Issuer Is Actually Buying
Reserve reporting involves more than generating a proof.
An issuer holding assets across onchain protocols and centralized exchanges needs to retrieve financial records, authenticate the information, calculate its backing and publish results that outside parties can independently check.
That also means maintaining the reporting pipeline when exchange interfaces change, verification fails or new reserve sources are added.
Primus packages several of these responsibilities together.
➤ zkTLS authenticates external financial records
➤ Protected computation and proving infrastructure process the relevant reserve information
➤ The dashboard publishes verifiable results
➤ Ongoing maintenance supports repeated reporting
The issuer still has to establish that the records are complete and that the underlying assets genuinely support its liabilities.
Cryptography doesn’t replace financial auditing.
● Why The Customer Keeps Paying
A free publishing period gives an issuer an opportunity to evaluate the reporting product before committing to a recurring subscription.
That’s different from selling a developer SDK and waiting for someone to build an application around it.
The product has a clearer customer journey:
Integration → Dashboard Deployment → Free Publishing → Paid Subscription → Ongoing Reporting
And reserve verification is naturally recurring.
An issuer doesn’t need to prove its backing only once. It needs to keep publishing updated evidence as balances, positions and liabilities change.
That creates a reason to retain the service beyond the initial integration.
● From Task Fees To Recurring Revenue
Primus already has a usage-based verification model where individual proof requests generate task fees.
Managed PoR introduces another potential revenue source.
One business depends heavily on verification volume.
The other can depend on the number of paying institutions, subscription pricing and customer retention.
Consider an illustrative example:
➤ 10 issuers paying $500/month = $60K annual revenue
➤ 25 issuers paying $1,000/month = $300K annual revenue
➤ 50 issuers paying $2,000/month = $1.2M annual revenue
These aren’t Primus’s disclosed prices, contracts or revenue forecasts.
They show why even a relatively small institutional customer base could produce a different revenue profile from low-priced individual verification tasks.
Of course, gross subscription revenue isn’t profit.
Exchange connectivity, proof generation, infrastructure monitoring and customer support all introduce ongoing costs.
● Verification Becomes A Subscription
Primus is turning cryptographic verification into a recurring financial service.
By packaging reserve reporting as a managed subscription, it creates a second potential revenue stream alongside zkTLS fees, built around ongoing institutional demand.

THEDEFIPLUG retweeted
550K+ holders, $45B+ in trading volume, and over $1B in AUM.
But the growth behind xStocks tells two different stories.
In September, @xStocksFi reported:
➤ 200K+ holders
➤ $40B+ cumulative volume
By October 28:
➤ 550K+ holders
➤ $45B+ cumulative volume
These are reported milestones, not exact growth figures. Still, the contrast is striking.
Holder adoption is expanding rapidly, but cumulative trading volume hasn’t increased at a comparable pace.
Now Payward has added 200+ UK and European equities, including Germany’s DAX 40, expanding distribution even further.
The question is whether xStocks is attracting active traders or a growing base of investors holding smaller positions.
Wallet counts alone can’t answer that. Neither can cumulative volume.
Monthly active holders, median position sizes and turnover per active wallet would tell us much more.
$45B in cumulative trading volume demonstrates substantial activity.
But the next test for tokenized equities is how much capital stays invested and how frequently those holders return to trade.

THEDEFIPLUG retweeted
The long-awaited @iris_credit mainnet is finally live🫡
For those unfamiliar, IRIS is building a fixed-rate borrowing layer for DeFi, allowing users to access more predictable borrowing costs by coordinating liquidity across existing lending markets.
This is a critical step towards bringing greater certainty to DeFi borrowing imo esp. for users who want to manage their financing costs without constantly worrying about fluctuating rates.
The launch begins with a limited Core Phase, supporting:
🔹 Collateral: cbBTC, wstETH & WBTC
🔹 Borrow USDC: via Aave/Morpho
🔹 Borrow USDT: via Aave/Spark/Morpho
The initial rollout comes w/ predefined limits and a narrower set of supported assets, which the team plans to expand progressively.
What interests me most is the broader opportunity for fixed-rate financing in DeFi.
While variable-rate lending has become a cornerstone of onchain finance, predictable borrowing costs are equally important for longer-term financial planning, leveraged strategies + capital efficiency.
IRIS is tackling this by building on top of existing lending infrastructure rather than trying to replace it.
Ofc, the real test will be how reliably its fixed-rate mechanism performs as liquidity, utilisation + market rates change.
But it's exciting to finally see the protocol move from concept to live deployment.
Keen to see how IRIS develops from here 🤝


1/ IRIS is LIVE on mainnet.
IRIS is a fixed-rate borrowing protocol.
Competitive quotes for any number of days, sourced from DeFi’s deepest liquidity.
Get a quote in seconds :
app.iris.credit/borrow
THEDEFIPLUG retweeted
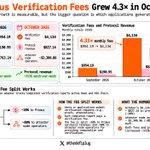
Primus’s onchain verification fees increased more than 4× in October.
And the fee distribution tells a pretty good story about how @primus_labs is monetizing its verification infrastructure.
Here’s how September compared with October:
September 2026
➤ Verification fees: $954.19
➤ Protocol revenue: $190.95
October 2026
➤ Verification fees: $4,134
➤ Protocol revenue: $827.14
That’s approximately 333% growth in monthly fees, with protocol revenue increasing at almost the same rate.
But there’s another detail I find more compelling.
DefiLlama’s fee adapter tracks completed verification reports across Base and HSK Chain.
Each completed report generates fees distributed between two recipients:
➤ Approximately 20% goes to Primus
➤ Approximately 80% goes to attestor node operators
So Primus isn’t capturing the entire verification fee. A larger portion compensates the infrastructure operators responsible for submitting the reports.
This creates a different economic structure from applications that retain nearly all their transaction fees.
The absolute numbers are still small, and the October increase doesn’t automatically establish recurring customer demand.
The missing piece is attribution.
Which applications generated the additional verification activity? Was it concentrated in a single integration, or distributed across multiple applications?
The public fee adapter doesn’t answer those questions on its own.
Still, October gives us a measurable increase in completed verification-fee activity rather than another adoption claim based entirely on partnerships.
And I think that’s the more compelling direction for researching Primus’s business: connecting actual verification usage with the economics of the network processing it.


Privacy is becoming a major crypto infrastructure narrative, but its leading projects are building for different customers.
Confidential DeFi, private execution, AI computation, institutional finance and cross-chain trading require different architectures.
The clearest comparison is what each team has actually deployed.
1. Primus
@primus_labs combines FHE-based confidential computation with zkTLS-authenticated external data.
Its BNB Chain Confidential Vault demonstrates encrypted balances, transfers and yield positions. An integration with Unitas and Brevis supports verification of exchange reserves and financial calculations without exposing every underlying position.
The opportunity is institutional finance that requires both confidentiality and independently verifiable records.
2. Zama
@Zama brings FHE-powered confidential assets to existing DeFi markets.
Its vault expansion connects encrypted positions to Morpho strategies curated by firms including Steakhouse and Flowdesk.
Rather than recreate lending liquidity, Zama adds privacy to established products. The question is how much economic value the encryption layer can capture.
3. Nillion
@Nillion’s Blind Computer targets private AI inference, protected workloads and verifiable computation.
By April 2026, it reported 112K+ users and 1.4M inference requests.
Its opportunity is closer to AI infrastructure and sensitive-data processing than private DeFi.
4. Aztec
@aztecnetwork is developing an Ethereum L2 built around private execution and confidential application state.
Its Alpha Network began processing transactions in March 2026. Building the execution layer provides architectural control, but Aztec must also attract developers, liquidity and sustained application activity.
5. Secret Network
@SecretNetwork has supported TEE-based confidential smart contracts on mainnet since 2020, including private tokens and DeFi applications.
Its newer products extend toward confidential AI and computing. That deployment history is substantial, but current usage is more revealing than longevity.
6. NEAR
@NEARProtocol integrates privacy into cross-chain trading through Confidential Intents, which protects selected transaction details.
Following its July 2026 general-availability launch, NEAR reported confidential mode surpassing 40% of near(.)com volume within weeks.
That figure applies to near.com, not the entire NEAR ecosystem. Still, it shows adoption inside an existing trading workflow.
7. Anoma
@Anoma launched AnomaPay V1 on Ethereum and BNB Chain, enabling supported shielded transfers without moving users to a separate privacy blockchain.
Its intent-based model connects private payments with programmable interactions. The commercial test is recurring transaction activity and integrations.
⸻
These seven projects represent different distribution strategies.
Primus combines confidential financial computation with authenticated external records. Zama brings encryption to existing lending markets. NEAR embeds privacy into trading. Aztec builds a private execution environment. Nillion targets AI workloads. Secret offers an established confidential-contract platform. Anoma extends shielded payments across public chains.
Ranking them solely by cryptography or token performance ignores the customer and business-model differences.
The stronger test is deployment, sustained usage and whether customers repeatedly pay for confidentiality.

THEDEFIPLUG retweeted
The gap between governance-only tokens and tokens with actual fee capture is becoming harder to ignore.
$UNI is a good example.
Since December 2025, @Uniswap has collected protocol fees from v2 and selected v3 pools, converting those fees into UNI burns.
Roughly one-sixth of swap fees goes to the protocol on some enabled pools. It’s not a blanket 17% burn across Uniswap.
@HyperliquidX takes a different approach.
Its Assistance Fund uses protocol revenue to continuously purchase $HYPE, with 99% of eligible trading fees allocated to the mechanism.
Other protocols have their own structures:
➤ @Aave uses DAO revenue for $AAVE buybacks.
➤ @JupiterExchange directs 50% of onchain revenue toward solana:JUPyiwrYJFskUPiHa7hkeR8VUtAeFoSYbKedZNsDvCN purchases.
➤ @Pendle_fi repurchases $PENDLE for active sPENDLE holders.
➤ @CurveFinance distributes fees to veCRV lockers.
➤ @pancakefi uses trading fees to buy and burn $CAKE.
The price comparison is revealing.
Over the 90 days ending November 10:
➤ $UNI: +87.28%
➤ solana:JUPyiwrYJFskUPiHa7hkeR8VUtAeFoSYbKedZNsDvCN: +51.17%
➤ $AAVE: +40.32%
➤ $HYPE: +26.54%
➤ $COMP: +22.49%
➤ $MORPHO: +1.79%
➤ $CRV: -3.84%
But the data doesn’t prove that revenue-accruing tokens always outperform.
$COMP appreciated without a direct fee-distribution mechanism. $CRV declined despite distributing fees to locked holders.
@Lido also has a conditional buyback mechanism, although its revenue threshold has prevented regular activation.
My preference is still for protocols where recurring customer payments translate into measurable token demand.
But the percentage of fees captured isn’t enough.
You need to compare actual buyback expenditure against token valuation, circulating supply changes, unlocks and the economics retained by the protocol.
Governance alone can command a premium.
A working fee mechanism gives investors another financial relationship they can measure.
The strongest candidates will be those where that relationship survives changing market conditions.

THEDEFIPLUG retweeted
Privacy is becoming a major crypto infrastructure narrative, but its leading projects are building for different customers.
Confidential DeFi, private execution, AI computation, institutional finance and cross-chain trading require different architectures.
The clearest comparison is what each team has actually deployed.
1. Primus
@primus_labs combines FHE-based confidential computation with zkTLS-authenticated external data.
Its BNB Chain Confidential Vault demonstrates encrypted balances, transfers and yield positions. An integration with Unitas and Brevis supports verification of exchange reserves and financial calculations without exposing every underlying position.
The opportunity is institutional finance that requires both confidentiality and independently verifiable records.
2. Zama
@Zama brings FHE-powered confidential assets to existing DeFi markets.
Its vault expansion connects encrypted positions to Morpho strategies curated by firms including Steakhouse and Flowdesk.
Rather than recreate lending liquidity, Zama adds privacy to established products. The question is how much economic value the encryption layer can capture.
3. Nillion
@Nillion’s Blind Computer targets private AI inference, protected workloads and verifiable computation.
By April 2026, it reported 112K+ users and 1.4M inference requests.
Its opportunity is closer to AI infrastructure and sensitive-data processing than private DeFi.
4. Aztec
@aztecnetwork is developing an Ethereum L2 built around private execution and confidential application state.
Its Alpha Network began processing transactions in March 2026. Building the execution layer provides architectural control, but Aztec must also attract developers, liquidity and sustained application activity.
5. Secret Network
@SecretNetwork has supported TEE-based confidential smart contracts on mainnet since 2020, including private tokens and DeFi applications.
Its newer products extend toward confidential AI and computing. That deployment history is substantial, but current usage is more revealing than longevity.
6. NEAR
@NEARProtocol integrates privacy into cross-chain trading through Confidential Intents, which protects selected transaction details.
Following its July 2026 general-availability launch, NEAR reported confidential mode surpassing 40% of near(.)com volume within weeks.
That figure applies to near.com, not the entire NEAR ecosystem. Still, it shows adoption inside an existing trading workflow.
7. Anoma
@Anoma launched AnomaPay V1 on Ethereum and BNB Chain, enabling supported shielded transfers without moving users to a separate privacy blockchain.
Its intent-based model connects private payments with programmable interactions. The commercial test is recurring transaction activity and integrations.
⸻
These seven projects represent different distribution strategies.
Primus combines confidential financial computation with authenticated external records. Zama brings encryption to existing lending markets. NEAR embeds privacy into trading. Aztec builds a private execution environment. Nillion targets AI workloads. Secret offers an established confidential-contract platform. Anoma extends shielded payments across public chains.
Ranking them solely by cryptography or token performance ignores the customer and business-model differences.
The stronger test is deployment, sustained usage and whether customers repeatedly pay for confidentiality.
THEDEFIPLUG retweeted
Crypto is on track to generate nearly $100B in blockchain-related revenue in 2026, yet only about 40% is accessible to investors through public stocks or tokens.
And publicly traded companies now capture 16% of that revenue, up from 7% in 2022.
The industry’s business growth and what investors actually own are becoming two different things.
According to 1kxnetwork’s study of 2,600+ protocols and 100+ public companies:
➤ ~$100B projected 2026 revenue, down 28% YoY
➤ 66% from DeFi and financial services
➤ 22% from blockchain infrastructure
➤ 30% connected to institutional and broader-economy activity
➤ 16% captured by publicly traded companies
These categories aren’t all additive. The estimate combines trading fees, reserve earnings, mining and staking rewards, and other income. It’s not $100B of comparable corporate profit.
The ownership structure breaks into four groups.
1. Public financial companies
@coinbase, @RobinhoodApp, @circle, listed miners and asset managers.
Coinbase earns from trading and services. Circle earns primarily from USDC reserve income. Miners receive block rewards and fees.
Investors can buy equity in these companies, but their earnings don’t automatically accrue to BTC, ETH or other tokens used in their businesses.
The growing public-company share means more crypto economics can be accessed through traditional equities.
2. Private crypto businesses
@binance, @Tether, private market makers, payment companies and custodians.
These businesses can generate substantial revenue without offering the public an equity claim.
Holding USDT doesn’t entitle someone to Tether’s reserve profits. Trading on Binance doesn’t provide ownership of its exchange earnings.
So some of crypto’s largest cash-generating operations remain outside the reach of ordinary token investors.
3. Token-based protocols
@HyperliquidX, @SkyEcosystem, @Uniswap and @aave.
This group is more complicated because protocol fees and token-holder benefits are not interchangeable.
Hyperliquid directs eligible fees toward HYPE purchases. Sky has buyback and staking distributions. Other protocols retain revenue for treasuries, liquidity providers or operators, subject to their individual rules.
1kx counted 283 protocols distributing economic value to holders in Q3.
But a token marketed as a governance asset isn’t necessarily a claim on net income. The percentage of fees distributed, buyback execution, emissions and future unlocks determine the actual exposure.
4. Blockchain infrastructure
Bitcoin, @ethereum, @solana and other networks.
Blockchain revenue includes transaction fees and, in the study’s accounting, mining or staking rewards.
But application success doesn’t flow automatically to the base token.
A DEX charging $100M can pay liquidity providers and retain most of its fees, while the blockchain underneath collects a much smaller amount for settlement.
1kx estimates direct transaction fees now account for less than 3% of total measured industry revenue.
That is a major distinction between financial activity happening on a chain and earnings captured by its native asset.
The final comparison is straightforward.
A public-company shareholder owns corporate equity. A private company’s customers own no part of its profits. A protocol-token holder receives only the rights and economics the system actually provides. A native blockchain token has its own issuance and fee model.
That is why the ~$100B headline needs an ownership breakdown.
The industry can generate enormous revenue while many of its most widely held tokens capture only a fraction of it.

THEDEFIPLUG retweeted

As of today, $AAVE has ~$30B in deposits and only $12.3B+ active loans.
That is a 41% utilisation rate to be improved.
Fixed-rate lending is still one of the biggest missing pieces in DeFi, and buying @avon_xyz’s fixed-rate markets and order book goes straight at it.
Since we know the intent, the first governance proposal will show who Aave is going after - treasury borrowers or experimenting an idea
(Data: @Token_Logic )


Aave Labs has acquired the team and technology behind @avon_xyz, one of the leading companies working on fixed-rate lending onchain.
The Avon team brings deep protocol engineering and market-structure expertise to Aave Labs as it expands onchain lending for a mainstream audience.

