



Pinned Tweet
@RealJimChanos says $IREN bulls should stop leaning on ARR, $/MW and prepayments and look at the actual accounting.
So I did.
It got more bullish.
At June 30, IREN disclosed ~$5.1B of ASC 606 remaining performance obligations plus ~$11.4B of contracted arrangements under ASC 842.
That’s ~$16.6B of contractual obligations in the financial statements.
Then ~$2.8B of new contracts were signed in July.
Before assigning anything to the unnamed frontier AI lab announced in August, I can identify >$19.4B of contracted obligations.
I’m intentionally not calling all of that “backlog.” Different accounting, different durations.
That’s the point: you don’t need the ARR slide to find the demand.
The contracts are in the filings.
IREN also ended June with $1.84B of deferred revenue. Roughly $1.62B was advance payments on lease-accounted tranches that hadn’t even commenced.
Not profit.
Customer cash arriving BEFORE the asset starts producing revenue.
And this is where I think the dilution argument starts to break.
For Microsoft/Horizons:
~$3.6B of investment-grade GPU financing + ~$1.9B of Microsoft prepayments against a ~$5.8B GPU purchase agreement.
~95–96% of associated GPU capex funded.
For Mackenzie, the $2.4B financing alone funds ~90% of associated GPU capex.
Customer prepayments sit on top, pushing total GPU-linked funding above GPU cost and helping fund data-center capex.
Now FY27:
$25–30B capex.
~$14B existing cash + committed GPU financing/prepayments.
~$8B additional GPU financing/prepayments targeted.
That leaves a $3–8B gross residual BEFORE data-center financing and operating cash flow.
Meanwhile management says 100% of its data-center portfolio remains unencumbered — including Horizons 1–4, the 300MW gross / ~200MW IT Childress build supporting a $9.7B Microsoft contract.
Think about that structure.
The Microsoft compute layer is already ~95–96% funded.
The data-center layer is still available to finance.
So the first DC financing doesn’t have to solve a $30B problem.
It attacks the remaining $3–8B residual.
In the favorable end of my funding bridge, DC financing + ex-prepayment operating cash flow can take that residual close to zero before incremental common equity.
I’m not making that my base case yet.
But it’s a very different setup from “IREN needs to issue $30B of stock.”
Customer prepay → GPU debt → operating asset → DC financing/refi → recycle capital.
That’s the flywheel.
The point isn’t zero dilution.
It’s that common equity can become the residual funding rail instead of the primary one.
Now Chanos’ ARR/revenue point.
How can IREN target >$4B of operational ARR at Dec. 31 while sell-side FY27 revenue is only ~$2.5B?
FY27 runs July through June.
Dec. 31 is halfway through it.
The >$4B is the annualized rate of the operating fleet at that point. The first half is the ramp.
Different clocks. No contradiction.
His capex comparison has the same issue.
FY27 capex funds multiple vintages: finishing CY26, CY27 air-cooled deployments, major DC construction for H2-CY27 Childress/Sweetwater, plus early CY28+ work.
The GPUs for those new H2-CY27 liquid-cooled facilities aren’t even in the FY27 guide.
A multi-vintage construction budget divided by one earlier vintage of ARR will obviously make returns look bad.
The numerator and denominator aren’t the same assets.
One Chanos point I’ll give him (cont.)


My last $IREN post looked at the economics of building a new AI data center. A post from @_Sgr_A_Star got me thinking about the mining halls IREN already owns at Childress. From a developer’s perspective, that’s a different deal. How much cash could I get back out of a retrofit while I still own the property?
I ran it on the same 10 IT MW example as before. IREN disclosed a five-year deal at about $22M of annual revenue per IT MW, with the customer prepaying 90% of the estimated GPU cost. IREN didn’t name the site. I wanted to see what those terms could do on a retrofit.
I used $400M for GPUs and $80M to convert the halls. That $8M per IT MW is @_Sgr_A_Star ‘s well reasoned assumption, at the high end of the $5M–$8M conversion range Core Scientific showed for its own projects. The customer advances $360M, leaving $40M on the GPU bill.
Say IREN puts up the $80M for the retrofit, then borrows $100M against the GPUs and $80M against the finished property. After paying the remaining GPU bill and $21.8M in fees and reserves, $118.2M comes back to IREN. That’s the entire $80M retrofit investment back, plus $38.2M of borrowed cash for the next build.
The first site keeps earning. At my assumed 75% operating margin, I get another ~$220M over five years after customer credits, upkeep, debt payments and estimated taxes. I’ve assumed no sale. IREN still owns the site and GPUs, with ~$55M of building debt left.
Here’s why I think it matters. Of the 250 gross MW IREN plans to retrofit at Childress, ~60 MW is allocated to NVIDIA. That leaves ~190 gross MW outside the NVIDIA deal. At my assumed 1.4 gross MW per IT MW, that’s about 135 IT MW, or roughly 13½ times this example.
If that whole footprint earns similar terms and financing, I get ~$1.6B back as the loans fund in phases, including $520M above the new retrofit investment, plus **$3B of cash over five years of service**. What I like as a developer is that the same property could help pay for the next build while it’s still earning on the first contract. Of course some of that capacity may be spoken for under deals already closed, but the illustration is important. One day the market will understand the flywheel $IREN has at its disposal. This is not a troubled company. It’s priced like it is. I recommend acting accordingly! (NFA of course 😉)

Such an important point by @_Sgr_A_Star on $IREN payback for air cooled retrofits. 1 year is insane.

$IREN
Good post BB.
The payback period for this ($22M, 90% Prepay) deal is much much lower than 2.1 years.
These numbers on the slide are for liquid-cooled deployments carrying a $20M per MW-IT data center capex.
Air-cooled data center capex is ~8M per MW-IT.
It means the net upfront investment is $12M ($4M from GPUs + $8M for DC).
Annual cashflow after operating costs and prepaid customer revenue credits is $11.8M per MW-IT per year.
($22M revenue - $3M operating costs - $7.2M prepaid credits = $11.8M)
Meaning the payback period on this deployment including the data center is 1.02 years.
Yes, 1 year.
No really, 1 year.
Yes, I'm positive.
1
27
3,866
Tree retweeted

Oracle has secured all the funding we need to fulfill our contract with OpenAI. With our final capital raise earlier this month, we became the first hyperscaler fully funded for this investment cycle. The financing we outlined at Oracle Investor Day, including vendor financing, is in place. Any further private discussions with vendors are just additional options. Our ability to deliver on our OpenAI contract does not depend on those discussions. Any media reports that will come out and say the contrary are incorrect and wrong.
Oracle and OpenAI are making rapid progress on our infrastructure partnership. Our Abilene campus, where Astra-6 was trained, is nearly complete. Shackelford, our next gigawatt-scale campus, is fully permitted. The handover of NVIDIA Vera Rubin racks in its data halls is on track for the coming weeks.
We continue to expect positive free cash flow in the second half of FY2028. We are targeting more than $30 billion in free cash flow in FY2029 and expect to self-fund future growth beginning that year.
Tree retweeted
How much more stock does $IREN actually need to sell to cover its $6B funding gap?
I’ve lost count of how many times I’ve seen this question on X. The dilution concern is fair. IREN has already sold a lot of shares. What I keep coming back to is how much of the remaining buildout they could fund with the assets they own and the contracts they sign.
First, the $6B was a September 30 number. After quarter-end, IREN raised about $630M through its ATM at an implied average of roughly $36 per share before fees. Giving them credit for that raise, I get about $5.4B left to fund against the original FY27 capex plan.
My last post looked at how IREN finances one AI deal. This time I put together four ways it could cover that $5.4B without another ATM sale or convertible.
The last row is the one I keep coming back to. IREN reported $6B of unencumbered data center assets, including land and projects under construction. If it can borrow $3B against Horizons and other eligible sites, another $2.4B in new GPU loans would cover the balance. That case assumes zero new customer advances.
Sweetwater is the obvious one to watch for a big prepayment, but a few smaller contracts at Childress or in Canada could help too. IREN already signed a five-year deal with a prepayment covering 90% of the associated GPU cost. Even a lower percentage on the next few deals could make a real dent.
That’s why I’d pay as much attention to the payment terms as the headline contract value. A smaller deal that puts cash in IREN’s hands before the GPU bills come due could do more for FY27 funding than a much bigger deal that pays in July. It would be a mistake to think that management is not close to addressing this very concern. I think we get news in the next month before the holidays. Buy the steep discount if you can!


Tree retweeted

The Fed Goes Rogue
There has been more Fedspeak in the past two weeks than in any other two-week stretch this year. Warsh appears to have a rebellion on his hands. So much for no forward guidance.
The Fed’s Keynesians are willing to risk everything, brushing aside data and theory. Headline inflation is an oil shock, not a demand boom: 3.7% against 2.6% core, with Dallas Fed trimmed-mean PCE at 2.3%.
October’s monthly CPI slowed from 0.6% to 0.4%. Shelter, a third of the rise, is partly the Fed’s own making. Core goods rose just 0.2%, and used cars fell 1.2%. There is no evidence of second- or third-round effects.
Services excluding energy cooled to 0.3%. Services inflation of 3.2% sits below its six-decade average of 4.7%. History is clear that rate hikes don’t fix services. After the Fed began hiking in March 2022, services inflation climbed from 5.1% to 7.6% over ten months. Under Volcker, it peaked at 18.1% eight months after the October 1979 shock. Services follow wages, rents and productivity, not the last rate move.
Meanwhile, base effects are doing the tightening for them. The real policy rate, proxied by the 2-year, is 1.93%. As the energy spike drops out, it rises to as much as 3.9% by December 2027, the tightest since 1990.
Their acolytes on Wall Street amplify the noise. This is not a disciplined policy debate. It is a political institution at war with itself.
Enough monetary policy by anecdote. Show us the data. Defend the theory. Explain the policy.
Remember how this crew acted when Biden and Yellen were in charge. They embraced MMT!
For a case study in the damage an unelected institution can do when it goes rogue, watch today’s Federal Reserve.
🤖 Made with AI

How much more stock does $IREN actually need to sell to cover its $6B funding gap?
I’ve lost count of how many times I’ve seen this question on X. The dilution concern is fair. IREN has already sold a lot of shares. What I keep coming back to is how much of the remaining buildout they could fund with the assets they own and the contracts they sign.
First, the $6B was a September 30 number. After quarter-end, IREN raised about $630M through its ATM at an implied average of roughly $36 per share before fees. Giving them credit for that raise, I get about $5.4B left to fund against the original FY27 capex plan.
My last post looked at how IREN finances one AI deal. This time I put together four ways it could cover that $5.4B without another ATM sale or convertible.
The last row is the one I keep coming back to. IREN reported $6B of unencumbered data center assets, including land and projects under construction. If it can borrow $3B against Horizons and other eligible sites, another $2.4B in new GPU loans would cover the balance. That case assumes zero new customer advances.
Sweetwater is the obvious one to watch for a big prepayment, but a few smaller contracts at Childress or in Canada could help too. IREN already signed a five-year deal with a prepayment covering 90% of the associated GPU cost. Even a lower percentage on the next few deals could make a real dent.
That’s why I’d pay as much attention to the payment terms as the headline contract value. A smaller deal that puts cash in IREN’s hands before the GPU bills come due could do more for FY27 funding than a much bigger deal that pays in July. It would be a mistake to think that management is not close to addressing this very concern. I think we get news in the next month before the holidays. Buy the steep discount if you can!
Tree retweeted
I work in real estate development, so when I saw the prepayment terms on $IREN’s newer AI deals, my first question was simple. How much of my own cash would I actually have tied up in one of these? I ran the numbers on 10 MW.
IREN reported about $22M in annual revenue per IT MW on recent five-year contracts. It also disclosed a five-year deal with a customer prepayment covering roughly 90% of estimated GPU cost. I used those figures for this example. The financing, margin and exit are my assumptions.
Using IREN’s illustrative costs, 10 MW takes $400M of GPUs and a $200M data center. At $22M per MW per year, that’s $1.1B of revenue over five years. The customer pays $360M up front, leaving $740M to collect over the contract.
I assume IREN puts in $200M of peak equity, then borrows $100M against the GPUs and $116M against the facility.
$200M equity + $360M prepayment + $216M debt − $600M build − $22M fees and reserves = $154M back to IREN.
That financing returns 77% of the original equity. IREN still owns the project and has $46M of its original cash tied up.
I used a 75% operating margin. For context, IREN’s own example leaves 85% of revenue after direct operating costs. My assumption puts five years of operating costs at $275M. Add $10M for upkeep, and $455M of the $740M still to collect is left. After principal, interest and modeled taxes, operations return roughly $206M.
So before selling anything, IREN gets about $360M back on $200M invested. That’s $154M from financing and $206M from operations. It still owns the site and GPUs, with about $79M of debt left.
I’d look at renewing the compute contract before selling. I modeled a year-five sale so I could compare the return with a real estate deal. For the property, I assumed a future colocation tenant could support $14.1M of annual net operating income. At an 8% cap rate, less conversion and lease-up costs, I get about $157M for the property. I valued the GPUs separately.
Including the sale, I get about $469M back on $200M invested. That’s $2.35 back per dollar over five years, or roughly $269M of project-level profit (~38% modeled equity IRR). Not bad if you ask me! As @_Sgr_A_Star says, word.
The number that interests me most is the $46M. That’s how much of IREN’s original $200M is still tied up after financing. The other $154M can go toward the next build while the first contract is still running.

I work in real estate development, so when I saw the prepayment terms on $IREN’s newer AI deals, my first question was simple. How much of my own cash would I actually have tied up in one of these? I ran the numbers on 10 MW.
IREN reported about $22M in annual revenue per IT MW on recent five-year contracts. It also disclosed a five-year deal with a customer prepayment covering roughly 90% of estimated GPU cost. I used those figures for this example. The financing, margin and exit are my assumptions.
Using IREN’s illustrative costs, 10 MW takes $400M of GPUs and a $200M data center. At $22M per MW per year, that’s $1.1B of revenue over five years. The customer pays $360M up front, leaving $740M to collect over the contract.
I assume IREN puts in $200M of peak equity, then borrows $100M against the GPUs and $116M against the facility.
$200M equity + $360M prepayment + $216M debt − $600M build − $22M fees and reserves = $154M back to IREN.
That financing returns 77% of the original equity. IREN still owns the project and has $46M of its original cash tied up.
I used a 75% operating margin. For context, IREN’s own example leaves 85% of revenue after direct operating costs. My assumption puts five years of operating costs at $275M. Add $10M for upkeep, and $455M of the $740M still to collect is left. After principal, interest and modeled taxes, operations return roughly $206M.
So before selling anything, IREN gets about $360M back on $200M invested. That’s $154M from financing and $206M from operations. It still owns the site and GPUs, with about $79M of debt left.
I’d look at renewing the compute contract before selling. I modeled a year-five sale so I could compare the return with a real estate deal. For the property, I assumed a future colocation tenant could support $14.1M of annual net operating income. At an 8% cap rate, less conversion and lease-up costs, I get about $157M for the property. I valued the GPUs separately.
Including the sale, I get about $469M back on $200M invested. That’s $2.35 back per dollar over five years, or roughly $269M of project-level profit (~38% modeled equity IRR). Not bad if you ask me! As @_Sgr_A_Star says, word.
The number that interests me most is the $46M. That’s how much of IREN’s original $200M is still tied up after financing. The other $154M can go toward the next build while the first contract is still running.
$IREN @danroberts0101 @mikealfred I am a big proponent of some insider purchases and have pushed numerous times for this. They do not need to be big. Showing your own confidence instills confidence in existing shareholders.
I know the IREN team is working insanely hard and that they can only do but so much in the short term to correct share price. I thank you for all your hard work. It wouldn’t take much to get this done.
Please consider!

An open message to @danroberts0101 and the $IREN team, from the shareholders who've been riding this down.
The stock is nearly 80% off its highs and down 26% in the last week alone. A lot of us bought because we believed in what you're building. Many of us still do. But it's been hard to watch the stock get cut in half again while shareholders hear nothing from the company.
What's most disappointing is that there hasn't been a single open-market insider buy in over a year. Not at $40, not at $25, not at $15. You tell the market there's a $20B backlog, 86% AI Cloud margins and a clear path to $4B+ of ARR. If management believes the stock is this mispriced, the strongest signal you can send is to buy it with your own money. When the people with the best information don't, why would anyone else step in?
And it's hard to ignore what shareholders have absorbed over the past year:
– 77M shares sold through the ATM
– 12M shares issued for Mirantis
– 18.2M RSUs granted to the co-CEOs, vesting on time served with no performance hurdles
– $4.3B of cash burned in one quarter, with debt up to ~$9.9B
– $6B of FY27 capex still unfunded, roughly the company's entire market cap today
– The $4B ARR target pushed from year-end to Jan 31, possibly end of February
When a stock falls like this, leadership should come out and talk to its holders. Not a press release full of backlog numbers, but a straight update on:
1. How the remaining $6B gets funded, and whether more ATM selling at these prices is off the table
2. Whether insiders plan to buy
3. Whether the RSUs will be tied to performance
4. Whether Jan 31 is on track, and what the real risks are
We're not asking for a stock price. We're asking for leadership. We would really appreciate some feedback from you and the team. Thank you!
$IREN
Tree retweeted

Stop stressing about $IREN's capex and assuming they’ll dilute shareholders to death at the current market cap...
The company’s unfunded capex “gap” for FY27 is $6B.
Management’s expected GPU financing and customer prepayments alone already cover about $5B of that.
And to be clear, their assumptions here are stupidly conservative, because they are only modelling around 90% of GPU capex being funded through BOTH prepayments and financing combined.
... $IREN literally signed a new 5-year contract two weeks ago where the customer alone prepaid 90% of the GPU capex.
They could then layer GPU-backed debt on top for another 50% of capex and get to 140% of the underlying GPU capex being funded, just ad they did across their 80 MW of Mackenzie capacity.
Non-dilutive funding is clearly not the issue in this market environment. Customers are DESPERATE for compute.
How is that not obvious??
We all know $IREN already has Anthropic as one of its customers. The company’s CCO recently said they have “one of the two leading AI labs” as a client.
And given Anthropic’s hunger for compute and willingness to sign contracts across a wide variety of cloud providers, it’s pretty clear who that is.
If $IREN wanted to, it could sell 100% of its FY2027 capacity, the same capacity that still requires the $6B of funding, to Anthropic and demand prepayments worth more than 100% of the underlying capex tied to those contracts.
All they would have to do is give up some revenue per MW in exchange.
So instead of signing a 5-year contract at $22M / MW, they'd likely get ~$20M / MW... Ouh no, what a disaster lol.
Anthropic is currently getting absolutely fleeced by $SPCX, paying something like $30M / MW for old-ass H100s and H200s.
They would happily jump on 100 MW of B300s for just two-thirds of the price if the trade-off is simply prepaying a larger portion of the contract upfront.
But if you’ve been paying attention, $IREN generally doesn’t pre-sell large amounts of capacity far in advance, while also prioritizing customer diversification to de-risk its contract portfolio.
If they really needed the funding, though, they could lean much harder on prepayments.
The market is totally retarded for failing to see that... 🙃
I’m looking forward to reflecting back on this period and quote-reposting a bunch of the stuff I’m publishing these days.

$IREN @jimcramer I hate companies that are “losing so much money” into extremely valuable income producing assets with short payback periods and near infinite long term demand…. 🤡

Jim Cramer on $IREN Iren: “Iren is one of those stocks that is just really hard to own right now, particularly in light of the fact that it is a company that was blessed by Nvidia. And even though I did agree with you that the quarter wasn’t that bad, they are losing way too much money for me to endorse.”
For anyone that needs a mindset shift after the worst PA imaginable for $IREN only lesson here for me was to always have more cash on sidelines for a worst case scenario.
The thesis for IREN has only strengthened overall. Markets can stay irrational for quite a time. Plenty of signs this a temporary setback. I can promise you buying $IREN today will be much better than hiding out in expensive “safe” stocks like Staples. Invest in the future and be patient. The rewards will come in time.

$IREN READ

Sentiment in $IREN is lower than I've ever seen. Price targets falling everywhere to match. One year ago, sentiment was at all time highs - it can change fast (in both directions). $IREN is pacing to ~10x+ operating ARR from ~$1B today to ~$10B+ by end of 2027 - either you think that will flip sentiment and drive multiples higher or you don't. The biggest question: will they get the money? Every channel check suggests customers are stepping in to fill the gap when lenders don't. Will they dilute to oblivion? The most recent earnings showed they have a path to not do that - either you believe @danroberts0101 or you don't. Do they have a moat / can they sustain a high multiple if we get high multiples again? 5+ GW of secured power with a ~35 GW development pipeline beyond is more than any hyperscaler has. Let it play out. NFA / DYOR.
nitter.cf/mcF_dan/status/2122293…
5
1,802
Tree retweeted

$IREN
I thought Kent made some very revealing comments on this interview that are very bullish and completely refutes the "nO MoRe cApiTal!" sentiment in the markets right now. Two in particular were key take-aways for myself.
1. Kent was very confident about the GPU debt markets remaining open to IREN
Quote:
"Similarly, on the GPU debt financing side, where we've raised over $6 billion in the last number of months, that market very much remains open. And by June 30 next year, we'll have a very significant amount of unencumbered GPUs that we can arrange debt financing against."
2. The increased scrutiny of hyperscalers' balance sheets and why that is already benefitting IREN
Quote:
“What we're actually seeing from the largest users, whether hyperscalers or the large foundational AI labs, is a continued increase in demand. If you look at hyperscalers, for example, who have increased scrutiny on their balance sheet positions, I think it's actually becoming more attractive for them to contract with players like ourselves. Instead of taking capex onto the balance sheet, they can secure compute as an opex line item. So that's actually driving an increase in demand on our side, contrary to some of those very specific examples, which I think are more tied to the underlying assets themselves.”
These two comments don’t guarantee anything, but they give me greater confidence that GPU debt financing will remain available to IREN - even for deployments backed by non-investment-grade customer cash flows.
They may also offer clues about who could become the anchor tenants at SW1 and Horizon 5–6.
Could we see a bidding war among hyperscalers and frontier labs for that capacity?
Here’s hoping. 😀

I know Kent personally. He's a real talent for $IREN and the AI infrastructure industry. I always listen when he talks to understand the inner loop where IREN plays.
When he says development timelines have stretched from 2 to 3 years to 7 plus in most jurisdictions. The bottleneck isn’t capital or GPUs it’s the multi-year process of securing land, power, and permits. Companies that started building that pipeline years ago have a structural advantage that can’t be compressed or bought later. That’s the game IREN is in.
Tree retweeted

We started shipping the Nvidia H100 in 2022.
A year ago it rented for $1.96/hour.
Today: $3.10.
+58%, on a chip that was supposed to be obsolete by now.
So much for GPU depreciation.

Tree retweeted

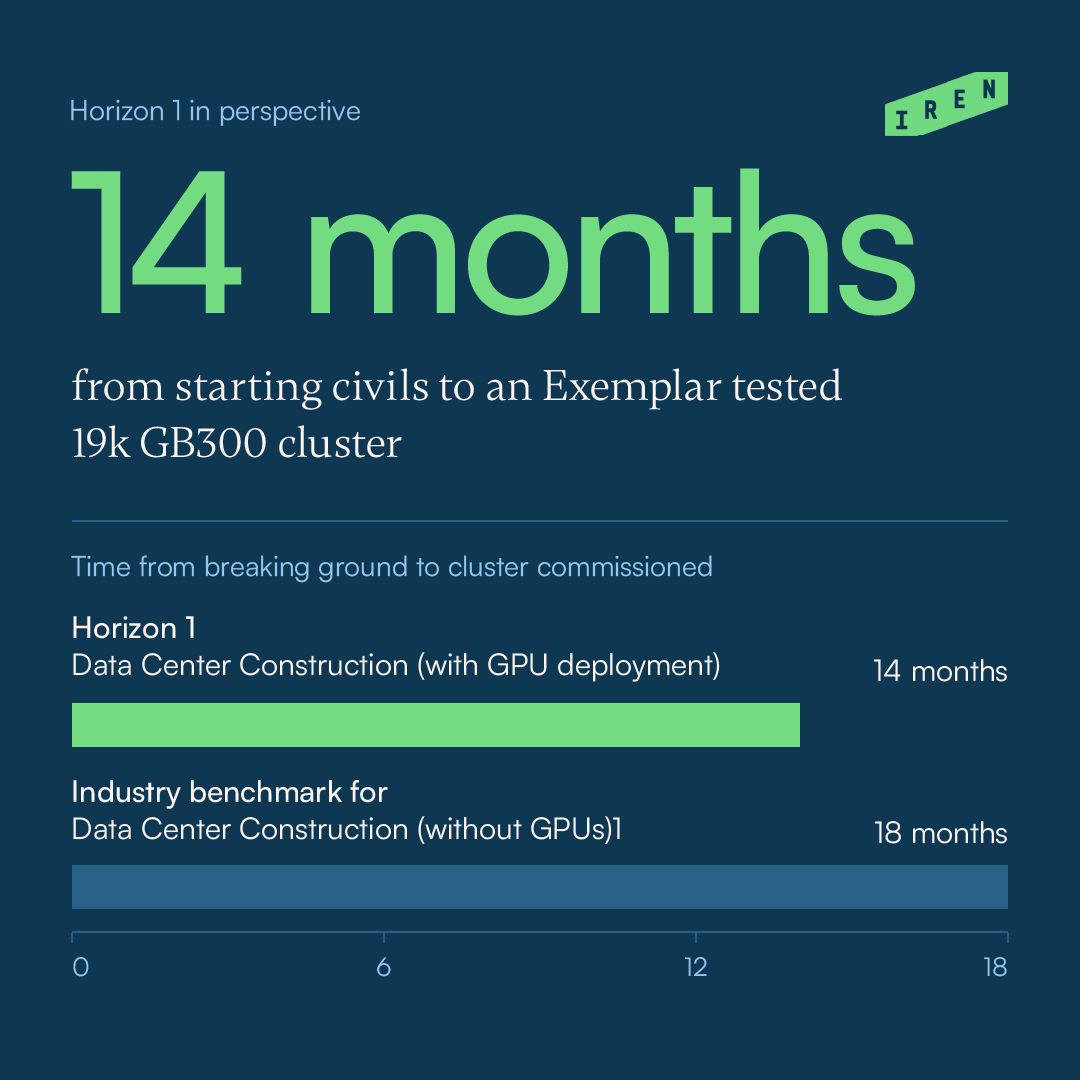
22% faster delivery than the industry benchmark.
Horizon 1, the first of four 50MW (IT) AI Cloud deployments for Microsoft, went from starting civils to an NVIDIA Exemplar Cloud-tested GB300 cluster in 14 months.
IREN's vertical integration delivers end-to-end control across design, engineering and construction, so contracted capacity reaches customers sooner.

Tree retweeted

Reasons not to hike rates at all, let alone 50bps:
1. Oil just crashed 20%
2. CPI is backward-looking
3. Inflation is at the average of the last 40 years
4. Stocks crashed last week
5. It's one print. An ugly print, but one print, and the Fed shouldn't be making decisions based on one data point
6. Inflation was a lot higher in 2021 and there was no urgency then, why, I wonder, does everyone have religion about this all of a sudden?
7. You never hike into a supply shock
8. Everyone knows this is about politics
9. Everyone knows Warsh is strongly disliked
10. And Warsh is a proxy for Trump
11. Copper just broke the uptrend
12. A 50bp move is for emergencies. Nothing here constitutes an emergency.
13. See my previous tweet