



Tree retweeted

Oracle has secured all the funding we need to fulfill our contract with OpenAI. With our final capital raise earlier this month, we became the first hyperscaler fully funded for this investment cycle. The financing we outlined at Oracle Investor Day, including vendor financing, is in place. Any further private discussions with vendors are just additional options. Our ability to deliver on our OpenAI contract does not depend on those discussions. Any media reports that will come out and say the contrary are incorrect and wrong.
Oracle and OpenAI are making rapid progress on our infrastructure partnership. Our Abilene campus, where Astra-6 was trained, is nearly complete. Shackelford, our next gigawatt-scale campus, is fully permitted. The handover of NVIDIA Vera Rubin racks in its data halls is on track for the coming weeks.
We continue to expect positive free cash flow in the second half of FY2028. We are targeting more than $30 billion in free cash flow in FY2029 and expect to self-fund future growth beginning that year.
Tree retweeted
How much more stock does $IREN actually need to sell to cover its $6B funding gap?
I’ve lost count of how many times I’ve seen this question on X. The dilution concern is fair. IREN has already sold a lot of shares. What I keep coming back to is how much of the remaining buildout they could fund with the assets they own and the contracts they sign.
First, the $6B was a September 30 number. After quarter-end, IREN raised about $630M through its ATM at an implied average of roughly $36 per share before fees. Giving them credit for that raise, I get about $5.4B left to fund against the original FY27 capex plan.
My last post looked at how IREN finances one AI deal. This time I put together four ways it could cover that $5.4B without another ATM sale or convertible.
The last row is the one I keep coming back to. IREN reported $6B of unencumbered data center assets, including land and projects under construction. If it can borrow $3B against Horizons and other eligible sites, another $2.4B in new GPU loans would cover the balance. That case assumes zero new customer advances.
Sweetwater is the obvious one to watch for a big prepayment, but a few smaller contracts at Childress or in Canada could help too. IREN already signed a five-year deal with a prepayment covering 90% of the associated GPU cost. Even a lower percentage on the next few deals could make a real dent.
That’s why I’d pay as much attention to the payment terms as the headline contract value. A smaller deal that puts cash in IREN’s hands before the GPU bills come due could do more for FY27 funding than a much bigger deal that pays in July. It would be a mistake to think that management is not close to addressing this very concern. I think we get news in the next month before the holidays. Buy the steep discount if you can!


Tree retweeted

The Fed Goes Rogue
There has been more Fedspeak in the past two weeks than in any other two-week stretch this year. Warsh appears to have a rebellion on his hands. So much for no forward guidance.
The Fed’s Keynesians are willing to risk everything, brushing aside data and theory. Headline inflation is an oil shock, not a demand boom: 3.7% against 2.6% core, with Dallas Fed trimmed-mean PCE at 2.3%.
October’s monthly CPI slowed from 0.6% to 0.4%. Shelter, a third of the rise, is partly the Fed’s own making. Core goods rose just 0.2%, and used cars fell 1.2%. There is no evidence of second- or third-round effects.
Services excluding energy cooled to 0.3%. Services inflation of 3.2% sits below its six-decade average of 4.7%. History is clear that rate hikes don’t fix services. After the Fed began hiking in March 2022, services inflation climbed from 5.1% to 7.6% over ten months. Under Volcker, it peaked at 18.1% eight months after the October 1979 shock. Services follow wages, rents and productivity, not the last rate move.
Meanwhile, base effects are doing the tightening for them. The real policy rate, proxied by the 2-year, is 1.93%. As the energy spike drops out, it rises to as much as 3.9% by December 2027, the tightest since 1990.
Their acolytes on Wall Street amplify the noise. This is not a disciplined policy debate. It is a political institution at war with itself.
Enough monetary policy by anecdote. Show us the data. Defend the theory. Explain the policy.
Remember how this crew acted when Biden and Yellen were in charge. They embraced MMT!
For a case study in the damage an unelected institution can do when it goes rogue, watch today’s Federal Reserve.
🤖 Made with AI

Tree retweeted
I work in real estate development, so when I saw the prepayment terms on $IREN’s newer AI deals, my first question was simple. How much of my own cash would I actually have tied up in one of these? I ran the numbers on 10 MW.
IREN reported about $22M in annual revenue per IT MW on recent five-year contracts. It also disclosed a five-year deal with a customer prepayment covering roughly 90% of estimated GPU cost. I used those figures for this example. The financing, margin and exit are my assumptions.
Using IREN’s illustrative costs, 10 MW takes $400M of GPUs and a $200M data center. At $22M per MW per year, that’s $1.1B of revenue over five years. The customer pays $360M up front, leaving $740M to collect over the contract.
I assume IREN puts in $200M of peak equity, then borrows $100M against the GPUs and $116M against the facility.
$200M equity + $360M prepayment + $216M debt − $600M build − $22M fees and reserves = $154M back to IREN.
That financing returns 77% of the original equity. IREN still owns the project and has $46M of its original cash tied up.
I used a 75% operating margin. For context, IREN’s own example leaves 85% of revenue after direct operating costs. My assumption puts five years of operating costs at $275M. Add $10M for upkeep, and $455M of the $740M still to collect is left. After principal, interest and modeled taxes, operations return roughly $206M.
So before selling anything, IREN gets about $360M back on $200M invested. That’s $154M from financing and $206M from operations. It still owns the site and GPUs, with about $79M of debt left.
I’d look at renewing the compute contract before selling. I modeled a year-five sale so I could compare the return with a real estate deal. For the property, I assumed a future colocation tenant could support $14.1M of annual net operating income. At an 8% cap rate, less conversion and lease-up costs, I get about $157M for the property. I valued the GPUs separately.
Including the sale, I get about $469M back on $200M invested. That’s $2.35 back per dollar over five years, or roughly $269M of project-level profit (~38% modeled equity IRR). Not bad if you ask me! As @_Sgr_A_Star says, word.
The number that interests me most is the $46M. That’s how much of IREN’s original $200M is still tied up after financing. The other $154M can go toward the next build while the first contract is still running.

Tree retweeted

Stop stressing about $IREN's capex and assuming they’ll dilute shareholders to death at the current market cap...
The company’s unfunded capex “gap” for FY27 is $6B.
Management’s expected GPU financing and customer prepayments alone already cover about $5B of that.
And to be clear, their assumptions here are stupidly conservative, because they are only modelling around 90% of GPU capex being funded through BOTH prepayments and financing combined.
... $IREN literally signed a new 5-year contract two weeks ago where the customer alone prepaid 90% of the GPU capex.
They could then layer GPU-backed debt on top for another 50% of capex and get to 140% of the underlying GPU capex being funded, just ad they did across their 80 MW of Mackenzie capacity.
Non-dilutive funding is clearly not the issue in this market environment. Customers are DESPERATE for compute.
How is that not obvious??
We all know $IREN already has Anthropic as one of its customers. The company’s CCO recently said they have “one of the two leading AI labs” as a client.
And given Anthropic’s hunger for compute and willingness to sign contracts across a wide variety of cloud providers, it’s pretty clear who that is.
If $IREN wanted to, it could sell 100% of its FY2027 capacity, the same capacity that still requires the $6B of funding, to Anthropic and demand prepayments worth more than 100% of the underlying capex tied to those contracts.
All they would have to do is give up some revenue per MW in exchange.
So instead of signing a 5-year contract at $22M / MW, they'd likely get ~$20M / MW... Ouh no, what a disaster lol.
Anthropic is currently getting absolutely fleeced by $SPCX, paying something like $30M / MW for old-ass H100s and H200s.
They would happily jump on 100 MW of B300s for just two-thirds of the price if the trade-off is simply prepaying a larger portion of the contract upfront.
But if you’ve been paying attention, $IREN generally doesn’t pre-sell large amounts of capacity far in advance, while also prioritizing customer diversification to de-risk its contract portfolio.
If they really needed the funding, though, they could lean much harder on prepayments.
The market is totally retarded for failing to see that... 🙃
I’m looking forward to reflecting back on this period and quote-reposting a bunch of the stuff I’m publishing these days.

Tree retweeted

$IREN
I thought Kent made some very revealing comments on this interview that are very bullish and completely refutes the "nO MoRe cApiTal!" sentiment in the markets right now. Two in particular were key take-aways for myself.
1. Kent was very confident about the GPU debt markets remaining open to IREN
Quote:
"Similarly, on the GPU debt financing side, where we've raised over $6 billion in the last number of months, that market very much remains open. And by June 30 next year, we'll have a very significant amount of unencumbered GPUs that we can arrange debt financing against."
2. The increased scrutiny of hyperscalers' balance sheets and why that is already benefitting IREN
Quote:
“What we're actually seeing from the largest users, whether hyperscalers or the large foundational AI labs, is a continued increase in demand. If you look at hyperscalers, for example, who have increased scrutiny on their balance sheet positions, I think it's actually becoming more attractive for them to contract with players like ourselves. Instead of taking capex onto the balance sheet, they can secure compute as an opex line item. So that's actually driving an increase in demand on our side, contrary to some of those very specific examples, which I think are more tied to the underlying assets themselves.”
These two comments don’t guarantee anything, but they give me greater confidence that GPU debt financing will remain available to IREN - even for deployments backed by non-investment-grade customer cash flows.
They may also offer clues about who could become the anchor tenants at SW1 and Horizon 5–6.
Could we see a bidding war among hyperscalers and frontier labs for that capacity?
Here’s hoping. 😀

I know Kent personally. He's a real talent for $IREN and the AI infrastructure industry. I always listen when he talks to understand the inner loop where IREN plays.
When he says development timelines have stretched from 2 to 3 years to 7 plus in most jurisdictions. The bottleneck isn’t capital or GPUs it’s the multi-year process of securing land, power, and permits. Companies that started building that pipeline years ago have a structural advantage that can’t be compressed or bought later. That’s the game IREN is in.
Tree retweeted

We started shipping the Nvidia H100 in 2022.
A year ago it rented for $1.96/hour.
Today: $3.10.
+58%, on a chip that was supposed to be obsolete by now.
So much for GPU depreciation.

Tree retweeted

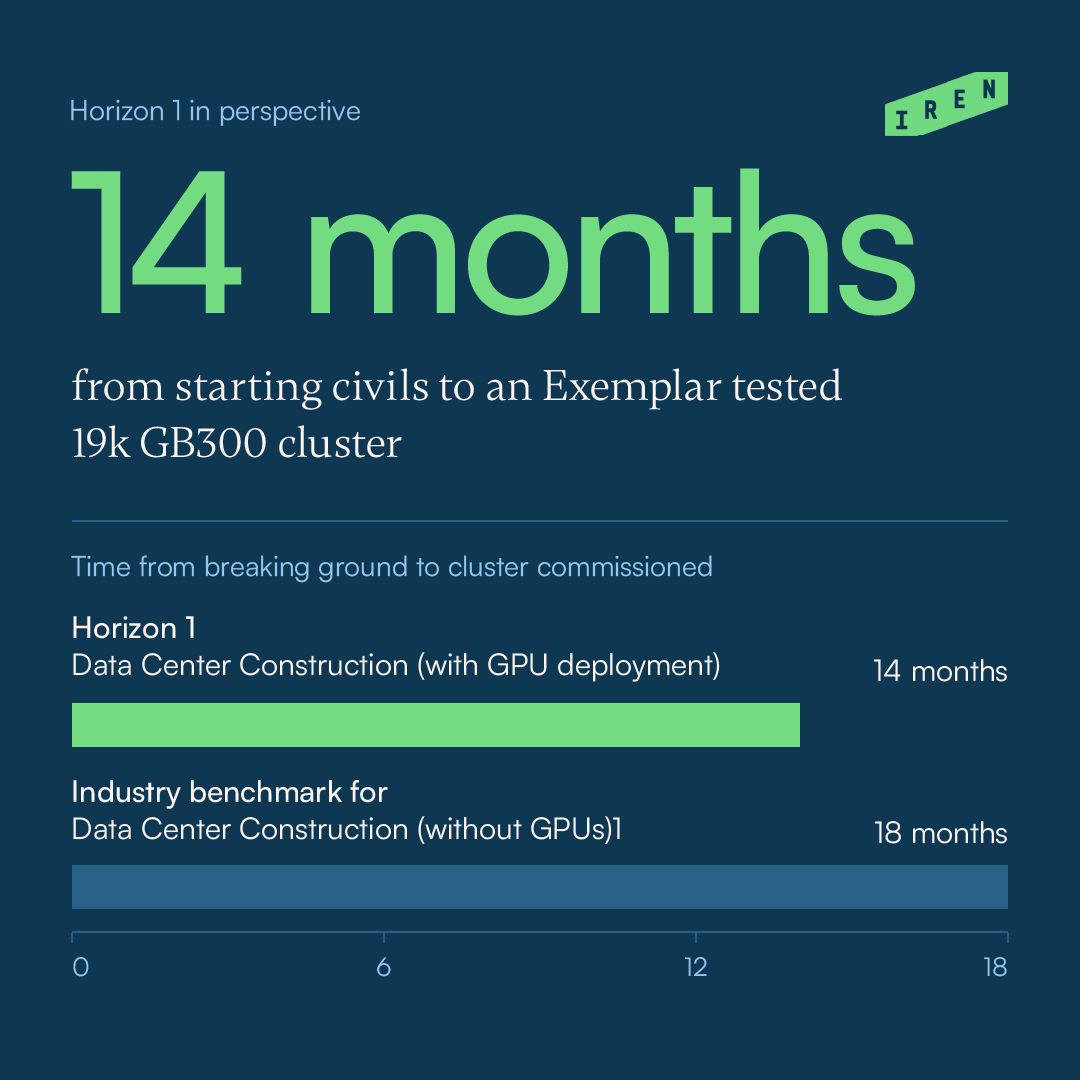
22% faster delivery than the industry benchmark.
Horizon 1, the first of four 50MW (IT) AI Cloud deployments for Microsoft, went from starting civils to an NVIDIA Exemplar Cloud-tested GB300 cluster in 14 months.
IREN's vertical integration delivers end-to-end control across design, engineering and construction, so contracted capacity reaches customers sooner.

Tree retweeted

Reasons not to hike rates at all, let alone 50bps:
1. Oil just crashed 20%
2. CPI is backward-looking
3. Inflation is at the average of the last 40 years
4. Stocks crashed last week
5. It's one print. An ugly print, but one print, and the Fed shouldn't be making decisions based on one data point
6. Inflation was a lot higher in 2021 and there was no urgency then, why, I wonder, does everyone have religion about this all of a sudden?
7. You never hike into a supply shock
8. Everyone knows this is about politics
9. Everyone knows Warsh is strongly disliked
10. And Warsh is a proxy for Trump
11. Copper just broke the uptrend
12. A 50bp move is for emergencies. Nothing here constitutes an emergency.
13. See my previous tweet
Tree retweeted

IREN: I Tripled My Position After The Crash $IREN #markets #business #investing seekingalpha.com/article/496…

Tree retweeted
Don’t Strangle the Supply-Side Recovery
The case for another Federal Reserve rate increase is crumbling. Gasoline prices are falling. Some DRAM spot prices are retreating. Two-year inflation breakevens have dropped 20 basis points in three days to 2.18%. Yet the tightening debate remains trapped in yesterday’s inflation.
That is how policy mistakes happen.
Tariffs and chip shortages raise the price level. They do not automatically create permanently higher inflation. Once those increases enter the comparison base, their contribution to annual inflation fades.
A product that rises from $100 to $110 records ten percent inflation. If it stays at $110 a year later, inflation is zero. No rate increase is needed to make that arithmetic work.
As 2026’s price spikes roll out of the annual comparison in 2027, base effects will pull inflation lower, without another Fed hike.
Now add actual price declines. Gasoline and parts of the memory market are reversing earlier increases. Disinflation is not merely approaching. It is underway.
The bigger story is productivity. Strong productivity growth, falling unit labour costs and a strong jobs market describe an economy expanding its capacity, not simply overheating. Businesses can produce more, support higher wages and contain costs simultaneously.
These are the green shoots Trump’s supply-side agenda is designed to cultivate: stronger investment, greater productive capacity and non-inflationary growth. The test of that agenda is sustained improvement in output and costs, not whether every strong jobs report triggers another inflation scare.
Employment growth is not the enemy of price stability. Weak productivity is. Treating every sign of economic strength as excessive demand risks strangling the supply expansion that makes growth sustainable.
The bond market is delivering its own warning. Two-year breakevens approaching 2% undermine the argument that inflation expectations are becoming unmoored. In fact they’re negative for the year.
The Fed must explain what another hike would fix. Higher borrowing costs cannot repeal tariffs or manufacture chips. They can crush investment just as productive capacity begins delivering results.
Those demanding tighter policy carry the burden of proof.
Do not punish stronger supply for looking like stronger demand.
🤖 Made with AI

Tree retweeted
@RealJimChanos Is this serious? I’m a CRE developer and I can tell you one thing. If i could collect prepayments from future apartment renters that cover 30%+ construction costs of that community, id be in heaven. You talk about it like it’s nothing important whatsoever. Yes it’s a capital intensive business. Yes there are risks. And therefore YES there is immense upside. The paybacks are so quick now and they are designing for future GPU generations in mind. DSX will give their LPS all sorts of upside options in the future. AI is not going away. $IREN

That’s just another form of financing. And the market has finally figured that out. $IREN
Tree retweeted
$IREN CCO Kent Draper just confirmed on the earnings call that the company has secured all the relevant construction permits for SW1 & SW2.
That removes one of the biggest uncertainties hanging over $IREN heading into earnings, especially after the Texas election results raised concerns around an extended freeze on new data center permits.
Honestly, the stock should be up 20% on that news alone.

At this point, I don’t even care that much about a potential delay in $IREN's Horizon deployments with $MSFT
...especially if it really comes down to the cabling topology mess-up that appears to have originated on Microsoft’s side.
We’re likely talking about a few extra weeks here, which isn’t going to break the camel’s back or change the fundamental setup.
The one thing I REALLY care about tonight is a reiteration of the 2027 capacity guidance.
With Texas flipping blue and the incoming governor aiming to continue the temporary pause on new construction permits, I’d really like management to directly or indirectly confirm that $IREN already has every permit it needs to finish Phase 1 of Sweetwater 1 (300 MW, gross).
I’m not asking for much…
Tree retweeted
🚨 $IREN: $22m / MW on a 5-year contract including 90% prepayment of GPU capex.
This is MASSIVE, wow... the demand for compute is unreal.

Tree retweeted

The governor-elect of Texas, Gina Hinojosa, has explicitly said that all currently permitted datacenters in Texas will be allowed to finish construction. This essentially covers all of the 2027 and likely well into 2028.
She is going to pass laws that ensure that all *newly* permitted datacenters going forward for delivery in 2028/2029 will pay taxes, commit to no increase in power prices for consumers, don’t impact water availability for people, be constructed with union labor and give “Texans a seat at the table.”
Sounds reasonable. She doesn’t want to lose a lot of good blue collar jobs and property taxes for small towns in rural Texas.
Datacenter commentary starts at 6:30 in this interview.
Also attaching her official campaign position from her website in the next post.
Sidenote: After watching a bunch of her speeches and interviews, I do think she is a political talent and probably has a future in national politics.
youtu.be/D-T6H3b8ZeE?is=mEWu…

Tree retweeted
You have to be mentally handicapped to wake up with the Nasdaq 100 trading at its lowest fwd P/E ratio in years and feel compelled to sell your tech stocks, while we continue going through the biggest, most profitable tech revolution in human history
Tree retweeted

I’ve been long $IREN since $5.30, and the call back then was pretty simple: if AI kept scaling, grid-connected power would go up in value. That played out, and I went quiet while it ran.
I’m back because the stock now looks more disconnected from the business than at any point since I bought it.
At $22 we're at an ~$8.4bn market cap and ~$19bn of EV once you include YE 2026 GPU debt: about 6.3x exit-2026 run-rate EBITDA, and ~2.3x 2028 EBITDA, including the debt needed to fund the buildout.
If the 2027 capacity signs even at bear-case prices, about 20% below today’s, it trades roughly at what its contracts are worth, even if every GPU and every building is worthless the day those contracts end. And it owns roughly 2.3GW of energized capacity at a time when the biggest buyers in the world are saying they can’t get enough.
My floor works out around $24–36 and my base case for end-2027 is around $130 🧵

Tree retweeted

When $IREN reports tomorrow that Horizon 2, 3 & 4 remain on schedule, the $4 billion ARR target is intact, and financing costs remain favorable, what legitimate bearish argument remains at a $21.71 stock price?