

Ironsides Macroeconomics LLC. Macroeconomic & public policy strategy I'm not joking. This is my job. Podcast: https://nitter.cf/t.co/RDQlWX61FE…
Vail, Colorado
Joined November 2011
- Tweets8.6K
- Following723
- Followers11.9K
- Likes7.6K
I could paint a similar picture about my 4+ decades on Wall Street.

Academic note: I have tried to be serious as a scholar, teacher and colleague since 1980s. In doing so I have constantly searched for productivity hacks — things that enable me to be more effective at being serious. Little things, like finding the right time of day to do research and to do teaching, or seeking ways to absorb needed knowledge like lectures at Great Courses or New York Review of Books or TLS. I moved from Word Perfect to Word, I have tried Palm Pilot, Blackberry, iPhone, I had a luggable portable computer that I traded in for laptop, and I used computer programs to take notes but switched back to notebooks and pen, and now use Kindle Scribe rather than ReMarkable. I try, I experiment, I assess. I read books in physical form, electronic form and audio. I watch YouTube and listen to podcasts all to help with lectures and papers. I used to search physically in libraries now I search online. My point is simple — I have always looked for ways to augment my skills and improve productivity. AI and LLMs are NO different in my experience. They don’t think for me, but they help speed up search and information gathering. I still have to exercise judgment, absorb what I need, and execute in a lecture, in writing, or in meetings with students and colleagues. The best productivity hack in my career is face to face dialogue with PhD students about ideas. These conversations are infinitely more interesting to me than me prompting Chat or Claude about material. Even working with a student on a difficult problem or struggling to understand concepts is more intellectually rewarding. Maybe I am doing it wrong, or maybe everyone else is describing their experience wrong. Modern AI is not the Palm Pilot, nor early versions of Netscape Browser (BTW, Browzine is a good hack for journal article access). But its not like having Kenneth Boulding, James Buchanan or Gordon Tullock as a teacher either! Its not like having been mentored by Don Lavoie and Karen Vaughn, or first inspired by Hans Sennholz, or arguing about economics 24/7 with Dave Prychitko and Steve Horwitz, let alone working closely with Israel Kirzner and Mario Rizzo for almost a decade, or teaching and learning from scores of PhD advisees at GMU. It just isn’t. Don’t buy the false narrative. It is not a substitute, it is a tool. You need to learn how to use the tool effectively to increase YOUR productivity as a scholar, teacher, and colleague. So invest in it, but at the end of the day you will have to be the one who uses the tool effectively or poorly. YOU, not the machine make the final judgement call.
Monday Morning Briefer Brief, by @barryknapp ironsidesmacro.substack.com/…
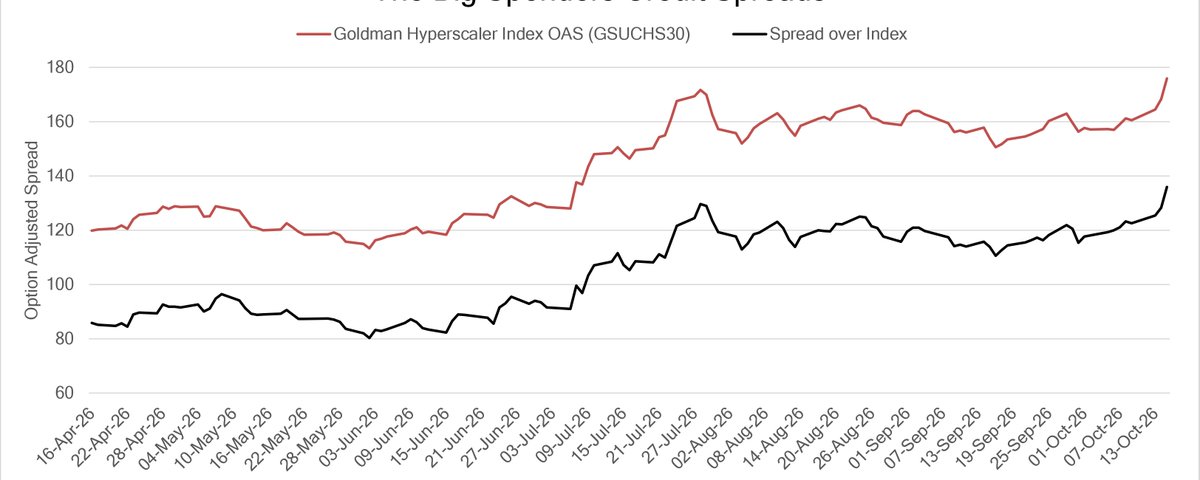
We enter the final stretch of 2026 with the Fed’s hawkish pivot—not fiscal supply or persistent inflation—as the principal driver of the sharp rise in long-term rates. The resulting real-rate shock has impaired housing, tightened technology credit, narrowed the equity market’s path to a year-end rally, and increased the odds that policy will have to reverse in 2027.
Our central concern is that the Fed is using rate hikes to offset structural inflation and administration policies while leaving its balance-sheet framework largely unchanged. That mix is damaging rate-sensitive sectors, raising federal interest expense, and exposing leveraged parts of the data-center investment boom without addressing the supply-side sources of inflation.
We remain cautious into year-end. Strong results from the largest cloud providers could stabilize equities and credit, but that outcome may also preserve the case for another December hike; conversely, further labor-market weakness or wider credit spreads could end the tightening cycle and create a more constructive setup for 2027.


Really good audience, I went last and they were engaged. Jared has a high quality group of subscribers!

This week, I hosted my annual Daily Dirtnap conference in Nashville. About 140 people were in attendance, with some of the brightest minds in finance as presenters. And a party at Nashville's greatest underground club!
Everything about it was perfect. And thanks to all those who helped with the details so I could focus on the content. We'll be doing it again next year.
Thanks to speakers: @TgMacro, @EricBalchunas, @barryknapp, @VD718, @Seawolfcap, @JanvanEck3, @CultishCreative, @MebFaber, @cafreiman, @pboockvar, Mark Lapolla, John Burns, and Marcin Zdunek.
If you want to come to the best financial conference on earth, you must be a subscriber to The Daily Dirtnap. DM me for details (and a discount).

Ironsides Macro retweeted

TLDR: movement in the $VIX and VIX options yesterday far outstripped moves in the SPX. there's information about market fragility here that we should be mindful of.
the VIX and SPX are negatively correlated. run the regression and it's on the order of -80%. but the slope of the regression (change in VIX per change in the SPX) is time varying. we have periods when the VIX moves a ton relative to the SPX move (Feb'18 volmagedon). in contrast, 2022 brought an extremely dull VIX, muted reactive to moves in the SPX.
yesterday, especially from 12:30 to 1:30pm, both the VIX and $VVIX moved a great deal relative to the move in the SPX. I show this below (thank you, Claude). typical VIX beta (% move in VIX per 1% move in the SPX) has been around 7. yesterday it reached on the order of 50. from 12:30 to 1:30, SPX down just 60bps...VIX up 29% (50x)...
talking my own thinking here, but there is no security in markets better equipped (at a low price) to hedge a near term crash than a short-dated out of the money call option on the VIX. this is what got really bid yesterday. the Oct 25 call (expires Wednesday) went from being worth 6 cents in the morning to more than $1 a few hours later. it exploded not just because the VIX rose so much, but because "vol of vol" surged as well.
no security is more "spot up, vol up" than the VIX itself. it will be interesting to see if this was a one-off or indicative of a larger shift in behavior where investor seek to cover deep left tail risk.


Any disinflationary impulse from the Fed’s rate hike(s) is likely to be swamped by the longer run inflationary effect on financing government debt

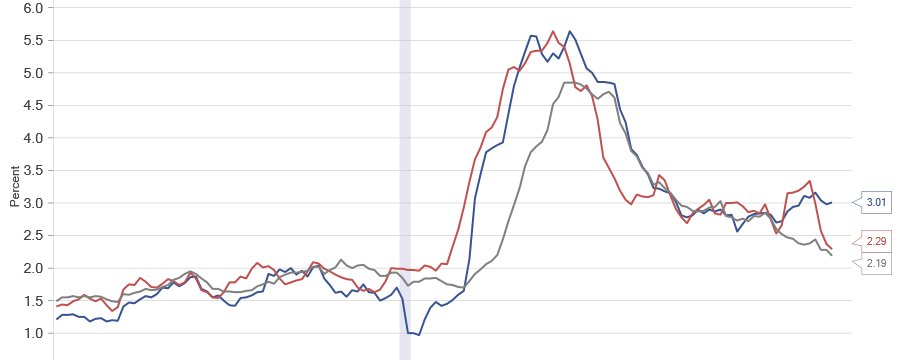
The Fed policy path started the fire in the long end, but even with October hike expectations cooling the correction intensified.
Monday Morning Briefer Brief, by @barryknapp ironsidesmacro.substack.com/…
The Fed, perhaps unknowingly, is betting the ranch on the K-shaped economy being particularly special, perhaps hoping for a productivity prize at the bottom of the box.
Insightful observations from Anna, the economic justification for this hiking cycle is weak. The Chair has another agenda in our view.

Debate on cause of rise of the long term bond yields:
Two models, both produced by economists affiliated with the Fed:
1) ACM (it’s all real yields/growth/ppl expect Fed to hike)
2) KM (it is term premium)
Warsh picked the former interpretation. As did the rest of the FOMC, implied in the SEP
More than a year ago, debate on whether tariffs would generate persistent vs transitory inflation:
Two models also from Fed affiliated economists:
1) tariffs generate persistent inflation (new research)
2) tariffs deflationary in the long term, and initially a one off price change (from a long standing structural model that proved to be correct in 2018)
The FOMC adopted the first interpretation, until facts showed otherwise today.
Tell me that economics is not a dismal science.
At least the Fed should debate about this, disagree. That is not what the SEP show.
Group think is rearing its ugly head inside the Fed again.
We sounded exceedingly bearish during this interview on Sunday, for context I had just won a big golf match! What is happening in the rates market today is what we expect to persist until and unless the Fed ends their ill-advised pursuit of target intended to communicate determination to avoid deflation. As Goolsbee put it, there will be pain.

If Fed embarks on additional rate hikes, that'd be a 'massive policy mistake': Economist cnb.cx/4iEO8Ta

Monday Morning Briefer Brief, by @barryknapp ironsidesmacro.substack.com/…
The Fed policy path, not inflation or term premium, explains the pressure on the ‘world’s most important asset’.
If Fed embarks on additional rate hikes, that'd be a 'massive policy mistake': Economist cnb.cx/4iEO8Ta
Resilient consumer?
If you take a deep breath and look at the trend in the control series of retail sales the picture that emerges is the adverse demand shocks/detox (government spending growth deceleration, immigration, tariffs) bottoming out in January, and the subsequent recovery driven by fiscal stimulus more than offsetting another demand shock (energy). The fiscal stimulus is fading. @SaraEisen @KellyCNBC @EconguyRosie

Monday Morning Briefer Brief, by @barryknapp ironsidesmacro.substack.com/…
Rate hikes will only stabilize the long end of the Treasury when they drive interest sensitive sectors into a deeper ditch. Doubling down on Powell Fed unbalanced policy is a mistake.
Ironsides Macro retweeted

Ahead of Friday’s CPI report, @barryknapp assesses the inflation outlook and the Fed’s potential rate path.
He explains what may be the “knife edge” for markets and what could lead to a “decent pullback” in equities.
For more: schwabnetwork.com/?CID=SM:Tw…