

Investor with a newsletter - https://nitter.cf/t.co/ekobHKkHro
Boston, MA
Joined February 2009
- Tweets2.1K
- Following1.1K
- Followers1.1K
- Likes2.8K







Pinned Tweet
Thank you @MSmicrocaps for giving me the opp to present $AMNF at the MSM Summer Virtual Conference. Deck here drive.google.com/file/d/1Hk9… . Armanino is the rare microcap with sane capital allocation, capex lite biz, #1 player in great market and growth runway. Frozen pesto bull!


Will answer my own question here with Pershing Q2 letter from 8/12 w/ table below. You need a little multiple expansion on 20% IRRs bc EPS growth <20% on all three.
Overall though I like that Bill is choosing names on avg w/ faster EPS growth + lower starting multiple than S&P.


@BillAckman Enjoyed your @CNBC interview this week - on $V , $MA and $NFLX 20% IRRs from here, what are you assuming for EPS and exit multiple in 3-5 years on each and why if you can share?
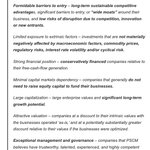
Looking at @BillAckman 's investing principles, recent interview and $META Q3, I think it's likely Bill believes equity raise unlikely, $META will generate substantial FCF regardless of next 3-5 years of capex spend and that Muse will lead to substantial long-term growth.


$TNIE competitor Yoto even though private does have history of annual reports - while Yoto is growing much faster, the gap is shrinking as Yoto decelerates and Tonies as of 25 end is 4x bigger on sales. 25' was a deceleration for Yoto from 86% to 43% y/y growth in USD while Tonies went from 33% to 31%. I make this point bc since I wrote Tonies up in August, most of the pushback has been on Yoto gaining share and anecdotally being more popular among older kids in the US. I think Tonies' size will continue to give it a substantial advantage and also I'd bet it will show operating leverage and be able to fund out of cash flow sooner than Yoto.

IMO $BRK.A should look at $CRWV debt. Very attractive yield and a lot of equity buffer. In @lloydblankfein 's book he talks about how $GS needed Buffett blessing to push down future cost of capital and calm market. $CRWV may be fine but optics matter, could be win-win for both.

Stock got bid today on Q3 update that orders are up 50% y/y + first wins in Mexico, Costa Rica and Slovenia. This is acceleration from Q3 25' growth (+23%). IMO what is happening here is CNS went from 1 to 6 products and AI made those products more important. $DDOSF $CNS.L


Per Zuck, it's $15 bn to "operate" a 1gw data center cluster per year after 50-$60 bn of upfront capex (I am guessing this includes depreciation). AI boom really is changing long term cost structure of $META and others. @alexandr_wang calls it "entrepreneurship on hard mode"


On $MGM , drawdown I think is deserved based on this data, rates, $PPLI bid falling apart and subsequent interest in $PPLI . No idea when bottom will be in on RevPAR. Wonder what we'll see on buybacks given they bought all through 30s, avg last 5y at $38.52


Tonies sold out Disney Princess bundle on $AMZN (since have restocked) and I have been seeing Pokemon set ads and deals for TB2 bundles, also $WMT has TB2 bundle sale for $109 versus $170 non-sale. I think Tonies is being aggressive growing install base into holiday season


Every time I see $BFAM in ValueLine I'm surprised by how it has compounded earnings + improved ROE v stock price. Will have doubled EPS in 4 years while multiple shrank from 30s to 12x. Enrollment, occupancy + quality concerns, but still think this one is interesting.


The Combs - Munger interview just shared on @shaneparrish pod echoes this point. Price can make great businesses bad investments. Ian writes in his book that most microcaps end up being <36m holding periods, and IMO changing conditions / price make it hard to hold longer.


As you mature as a stock picker and accumulate more reps, you begin to respect how quickly conviction changes, especially in microcap. You start to understand that businesses don’t operate in a vacuum. Businesses are dynamic and conviction must also be dynamic.
I may love a company today, but there is only a 10% chance I will love it in 24-months. This is further proof you shouldn’t talk openly about your positions unless you are strong enough to change your mind in front of the crowd. The more defending you do, the more you anchor yourself to yesterday’s conviction.
2) Why not just buy $AKAM here? The Anthropic agreement is capex intensive for Akamai ($5.5bn of spend over two yrs on CPU buildout) whereas Corero's solution will be largely software only and capex light. Corero has no debt + CEO has said they will be FCF positive from 27+.

Looks like $NET can block Dots from accessing content (interesting this does not happen with Muse). Even when I take over the browser control, it gets stuck in a verification loop. Will be interesting to see long term what happens with agents accessing websites from VMs...


$AKAM also is a customer of Corero (great research below from @Edison_Inv_Res ) and Linode prior to Akamai acquiring it was a Corero customer

