

Founder - Denmark Capital. Purposely flying under the radar from the beginning…just a little less now. Views my own.
Boca Raton, FL
Joined June 2025
- Tweets584
- Following1.3K
- Followers182
- Likes1.1K





Pinned Tweet
Many are debating how to price AI's promise. Few are pricing in what happened to the machinery that sets prices, and how often and badly it can now misprice the best businesses on the planet.
THE TWO CLOCKS, an essay: Long-term ownership in a passive market


one potential difference here is that, outside of coding, the underlying models / products could still be early in their utility and usage.


What matters now is further productizing the new trajectory. When looking at political, financing and public equity markets, the message is clear that it’s time for the labs and others to show a steady march to AI handling 10%+ of today’s knowledge worker equivalent work by 2031.


Listening to this, seeing the insanely quick ARR ramp of Anthropic, OpenAI and other successful AI natives, and now seeing Anthropic basically miss its ideal IPO window begs the question of whether fast growing AI natives that are capital hungry should IPO sooner. When an AI native finds strong product-market fit, ARR is off to the races. But the consequence could be susceptibility to hitting the dreaded growth decel almost as fast. If this dynamic proves out and these companies will need a lot of capital to reach their next S curves, maybe we get more companies IPO’ing earlier going forward.

DoorDash’s inference spend has plateaued the last 1.5 months after rising 20x this year, according to co-founder Andy Fang.
He’s been discussing with Tony Xu: “if we’re seeing ROI from the spend, wouldn’t we want to spend more?"
FOODY: “Are you able to share how much you guys are spending on inference right now?”
FANG: “I’ll say a stat, that I think our inference spend has gone up 20x since the beginning of the year.”
FOODY: “How much do you expect it to go up over the next 24 months?”
FANG: “Well, I would say even the past month and a half, it’s plateaued. It hasn’t shrunk, but it’s definitely flatlined. I think there’s definitely efforts we’ve had internally to curb the spend. [...] And I was just talking to Tony, our CEO, about this earlier today. If we’re seeing ROI from the spend, wouldn’t we want to spend more, right? And so I think that’s the thing everybody’s trying to figure out, is where are those opportunities? Because let’s say if you’re generating revenue from token spend, you would spend that token spend all day, right? But I think a lot of what we’re focused on as an industry right now, quite frankly, is cost efficiency and all that stuff.”
Seeing additional wow AI products like the version of personal agents that just work is what should do it. People can better appreciate next 5-10 year opportunities as next undeniable products / improvements are released.

Here is the problem I have with the memory trade right now. I personally believe we are still very early on the memory supply catching demand. I honestly think it might never happen. At least not in this decade. I also think memory prices will stay high forever. Just like new GPU or TPU prices will never drop in price. Every new GPU, TPU, and ASICS will get a new version of HBM. HBM will always be upgrading, and demand a higher price than the previous version. We are so early. Personal interference bots are about to explode. We are not even at the stadium with those, let alone starting the game. So much more memory will be needed for all of these bots. Then we get physical robots in a few years. Don’t even get me started on that. Space and other planets will follow, but that’s way out there. Literally no end to the build out. There are many people that completely disagree with me. Some think we are at the memory peak right now. Some think it’s less than a year away. And some think it’s a year or 2 away. Getting back to my problem with memory: how do we prove who is right? Is memory near peak and about to crash? Or are we in the early innings?
Every earnings that goes by, MU keeps crushing and guiding higher. But investors don’t believe it will continue. Next earnings, MU will make at least $44 billion dollars of profits in one quarter, and guide higher for the following quarter. But that doesn’t seem to matter. Micron stock no longer goes up because people don’t believe the earnings will continue. You see, when facts and data don’t matter, anything goes. Any story or thesis can be used against MU. So, if actual earnings and guidance don’t matter, because they are not believed to continue, how does that get proven to be true or false? If earnings after earnings continue to beat and raise, but the imaginary end of memory is thought to be right around the corner, then what? How cheap does MU have to be for investors to believe it can continue. With their thesis, the current valuation doesn’t matter because they believe memory prices will fall. so the actual earnings don’t matter! How long does this continue? What breaks this thinking? I honestly don’t know. I am 100% convinced Micron will make hundreds of billions of dollars of profits the rest of this decade. I absolutely believe earnings will go up every year for the rest of this decade. But if the market doesn’t believe that, when does the stock reflect the actual earnings? As every earnings report goes by, MU just gets cheaper and cheaper! I’ve never experienced this before. I’ve never seen actual earnings doubted to continue without any signs of a slowdown!
I honestly don’t know what it will take to convince investors that these earnings are durable and lasting.
Maybe the buyback is the only way! I would love to hear everyone’s answers as to what might eventually break this thinking. Obviously if earnings crash, we get that answer, but what if earnings continue to go up every quarter for the next few quarters?
Would be terrible. If it happens, non zero chance a certain “yikes” post and subsequent neocloud bashing helped bring it about

“We’ve also begun drug discovery efforts of our own”
Dario expanding the IPO buyer universe to biotech funds?

Over the past few months, Anthropic scientists have engaged in deep research partnerships with six organizations developing new medicines. We've also begun drug discovery efforts of our own.
In doing so, we’ve learned much more about how Claude can support the many stages of drug development.
In this blog post, we share some early results from these efforts, and describe how this work fits in with our wider ambitions in the life sciences.
anthropic.com/research/early…

Interesting discussion that brought to mind how human intelligence can be both the friend and foe of the intelligent investor. The friend when it allows you to more carefully and thoughtfully understand and reason through what matters. The foe when it causes you to add too much complexity to concepts that should be more straightforward when already playing out in a powerful way.
With AI, on the overly optimistic side, this can manifest in brilliant technologists reasoning their way into an incredibly accelerated path and very aggressive assumptions like adding 50+ GWs of AI-related compute capacity in 2027 and perpetually rising GPU pricing. On the pessimistic side, it can cause highly intelligent investors to reason their way into all the uncertainties in the path being too much to bear, like token pricing vs demand and model provider economics. This can cause you to put everything infra and hardware-related in the too hard pile when in reality getting comfortable with some of these uncertainties might be smaller leaps as compared to certain things you already own in light of what is already on the tracks and playing out.

Cliff Sosin (@CliffordSosin) is one of my favorite people to call, ask some big questions, and then shut up and listen.
This conversation is a version of one of those calls.
We discuss:
- The limits of intelligence
- Owning the complements to it
- Meta, the frontier labs, and the AI build-out
- Capital markets
- Why he's comfortable with 80% of his portfolio in Carvana.
TIMESTAMPS
0:00 Intro
10:41 The Limits of Intelligence
18:03 Investing Beyond Cheap Intelligence
24:03 Will AI Become Commoditized?
35:10 Who Profits From AI?
43:00 AI Agents Reshape Competition
52:06 America's Capital Markets
58:04 Transforming Companies With AI
68:19 AI and Portfolio Concentration
73:16 Education in the AI Era
asking this again post DoorDash-Instacart rumors….

The latest selloff in $SE has me asking whether ecomm managements that are investing across multiple dimensions and facing AI disruption questions should try this type of reasoning exercise:
Assume Anthropic had full access to your business, data and people for 6 months. What would they prioritize for improving your value prop? How does that compare with where you’re investing today?
And would Anthropic’s people or yours be better at executing these priorities?
3 things that stood out to me from Anthropic’s S-1 that I think have been underdiscussed:
1) Employee turnover is very low. We’ve known they buy in to put it mildly, but the filing did a good job of reminding us how much this commitment and togetherness has differed from OpenAI, at least early on; 2) they don’t just follow their customers’ needs when thinking about what to improve or build next. You can see how their own interests and problems may influence research priorities. We know of Dario’s fascination with drug discovery, which was all over the S-1…but you could also see it in areas like potential improvements to power grids and battery design, which I suspect are informed in part by their own infra challenges; 3) the learning feedback loop could prove critical. It’s interesting how many people seem to view frontier models as increasingly commoditized while simultaneously discussing RSI and the possibility of moving beyond transformers. We could still be very early in model progress, in which case being the frontier leader with deep enterprise adoption and the ability to learn from this customer base could prove invaluable.
the takeaway from Ken Griffin’s interview isn’t about him being bearish on AI. I think it’s about the possibility that the investment industry’s dominant risk management structures are becoming fundamentally incompatible with capital intensive tech transformations whose economic trajectories may be far more durable than their stock price trajectories.

Ken Griffin of Citadel questions the economics of the AI infrastructure boom:
›What happens when GPU supply exceeds demand & pricing goes into free fall?
›Are today's semiconductor margins sustainable? Are investors overestimating the useful life of GPUs?
“Look, I think this market is actually experiencing people doing research.
For the couple of years, if you were on the thematic program of we're gonna spend hundreds of billions or a trillion dollars in data centers, we're gonna build compute at a scale never seen before, which companies in that story are choke points in supply chains that will have abnormally high margins? And who will be the big winners in this transformation?
Will it be the Microsofts & AWSs who will be the gatekeepers to the foundational models? Like, who's going to earn the economic rents?
But in some sense, like, 'I'm just gonna buy them all. I'm gonna buy the hyperscalers, I'm gonna buy the chip, I'm gonna buy businesses that make things I've never even heard of 5 years ago in Korea and Taiwan & in Japan.'
And now we're reaching a point where people are becoming more discerning.
We do realize that we are seeing extremely high margins in DRAM & MLCCs in areas where there are real supply constraints, but people are now starting to look out 2 years, 3 years. How long is this going to last?
And in particular, I don't wanna be doom & gloom, but GPUs, like airlines, have a very low marginal cost to run.
The incremental seat on an airline that's not full, if you can sell that ticket for $20, you're making money in that seat.
And that's one of the reasons that the airline industry is such a nightmare, is because the moment you have overcapacity, pricing goes into free fall.
We saw this actually with the telecom build-out back in 2000. We built more fiber than we had demand for, & the price of telecommunications just went straight down.
If we reach a point where the provisioning of GPUs exceeds demand for GPUs, marginal pricing will actually go into free fall.
And that really upends all the investment assumptions that people are working with today.
That's issue number one.
And issue number 2 is:
I think people are taking a step back & saying, 'What is the useful life of a GPU?'
Right here, right now, there's people that are earning extraordinary pricing on GPUs that are 5 or 6 years old.
And so there's a growing set of concerns that I can't give the same capitalization rate or the same revenue models to year 7, 8, 9 of a chip in the future that maybe I was using 12 months ago.
So I think we're really grappling with just how far will this demand carry us in the marketplace.”
Either Elon (expected AI capex) and Zuck (expected ROI on AI capex) are way off or public markets are way off.
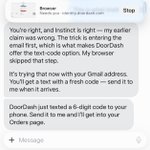
as an offset to the inconvenience of working with and giving context to multiple personal agents like Muse, Instinct, Dots, Claude Duet etc, now is probably the most willing consumers will be to do so as compute costs and rate limits get friendlier over time.
The latest selloff in $SE has me asking whether ecomm managements that are investing across multiple dimensions and facing AI disruption questions should try this type of reasoning exercise:
Assume Anthropic had full access to your business, data and people for 6 months. What would they prioritize for improving your value prop? How does that compare with where you’re investing today?
And would Anthropic’s people or yours be better at executing these priorities?

Muse could end up having terrible retention and would still be a very important development for $META . MSL rising up lowers LT disruption risk, creates optionality, and increases the odds that the huge AI capex will prove to be a wise capital allocation decision overall.
(and I don’t think Muse having weak retention in its current form would be saying much about consumer interest in productivity gains)

interesting, will try talking to a Tolan.
but will say this feels like the furthest apart VC and public markets have been on AI in a while.

Some news: we at @USV are leading a $30M round in Tolan, alongside our friends @khoslaventures.
AI has changed how we work. Frontier intelligence has made us more productive, and it lets us build incredible software without writing code. But AI can be more than a really competent digital coworker. It can also be a friend.
At USV, we’ve always believed technology can actually connect with people. Tolan is the best version of that idea we’ve ever seen. Instead of a blank chat box or a productivity tool, it’s a persistent companion that people keep coming back to because it connects with them.
We’re so excited to partner with Quinten, Evan, and Ajay, and watch Tolan become a bigger part of everyday life for so many people.
I think the recent AI related volatility in public markets is something that should be viewed as normal and recurring as far as the eye can see. First, the market’s fast clock has been rebuilt over the past 15 years so that more participants than ever are either wired or forced to try and smooth volatility, which only creates more of it. Second, AI and its capital intensity, financing requirements, disruption potential at the application layer, uncertainty regarding ultimate unit economics at the model layer, and lightning fast pace of innovation add a level of uncertainty that the market’s rebuilt fast clock was never prepared to deal with. All together, expect an endless flow of protracted debates and swirling fears that will move markets and your holdings more than you think and more often than you think. In dealing with this, ask: what are your philosophical views around duration, long termism, and how much your process should be built to react to the path and the numerous debates along the way based on your approach to risk management.
Public markets are currently saying that techies can't distinguish the singularity from nothing ever changes.
As someone who did nonstop management meetings for over a decade, I’d be wary of viewing this as something that’s critical to investing successfully *if you have the right accumulated judgment* (can be important earlier in career).
Fewer than 3% of public companies have accounted for all the net wealth created in global markets over a long period. These are typically companies creating, shaping, and redefining large, often self-created markets and are usually led by obsessive founders or re founders who prove to be extraordinary strategists and operators.
Particularly with the abundance of info available today and more managements going direct (and often), there are plenty of ways to study businesses deeply enough that the ones with these qualities eventually hit you over the head like a 2x4.
You tend to learn a lot more about management and a company from what they do over time and how they come through tough situations.

Management meetings/field research is more important than ever. Assume 75% of the work you do at your desk for 8-12 hours a day will be done better by agents running 24/7. Being on the road more should be part of the job description for analysts.
Model build tests as a screen to hire analysts will eventually go away and perhaps be replaced with mock management interviews or mock information synthesis.
Being a nob in shared meetings, sabotaging yourself and those you share with will become fatal.
Every possible input into the numbers inside one of the three financial statements – product, sales, distribution, input costs, discretionary opex, balance sheet utilization, capital allocation, etc , etc, etc . . . . seemingly always fall into one of two buckets.
1.) Things within management’s control.
and
2.) Things outside their control.
When given the opportunity to meet with company executives, it’s almost always more productive, when faced with limited time, to ask specifically about things they control. There are certain questions only management can answer. Ask those questions first. Too much time in management meetings is spent asking execs to speculate on short term things outside of their control.