

CIO at FortyTwo Capital | Marathon Runner | Cyclist
Utrecht
Joined July 2009
- Tweets3.5K
- Following134
- Followers939
- Likes2.3K





Ferguson's Law is a geopolitical and fiscal principle formulated by historian Niall Ferguson stating that any great power spending more on debt interest payments than on defense risks losing its status as a great power.

Absolutely insane stat: The U.S. is spending more on interest payments ($1.33T) than on national defense ($1.23T).
The cost of past debt now exceeds the cost of protecting the nation.
The bill for decades of borrowing has come due.

1
362
Jan Klein Poelhuis retweeted

🦔Three CoreWeave founders cashed out $3.3 billion of stock, and now one of them wants a pat on the back for buying $30 million of bonds. If Venturo believed in the stock, he’d buy the stock. Bonds get paid first if things go bad, and these ones paid around 16% in October, which is what lenders charge when they’re nervous. Nvidia backs CoreWeave so it can buy more Nvidia chips, and the founders already took their money off the table.
Hedgie🤗


It feels like this entire message was drafted because of the final part: Jensen is willing to make a comeback. Ending the message with that makes the ‘not living up to the standard’ part not really genuine. Think the way to go is to wait for the independent research. If that comes in clean, Jensen can reconsider a come back. Fair to say that Jensen made himself irreplaceable, something you never want a CEO to do as a shareholder. Anyways, just a few random thoughts as an outsider without shares.

This looks even more pathetic after the prospect of him returning was completely shutdown by the Chairman of the Board on the earnings call
1
1
649
Earlier this year I took a position in $III.L, a UK holding company with close to 80% of its net asset value in Dutch retailer Action. Action has a phenomenal business model that has proven it can scale across Europe. Next up is the US in 2027. That will be a bigger challenge, but success there would be major upside. 3i is a 3% position in my aggregate portfolio, so still fairly small.


One of my more ‘exotic’ positions, $NU, reported earnings last week. Over the weekend I studied the Q3 results and I’m pretty happy with what I saw. Nubank is executing like clockwork in Brazil, Mexico and Colombia. And then there’s the (controlled) expansion into the US, which isn’t even needed to earn a solid return. That said, Nu is still a bank, with all the complexities that come with one, and those are hard to judge from the outside.


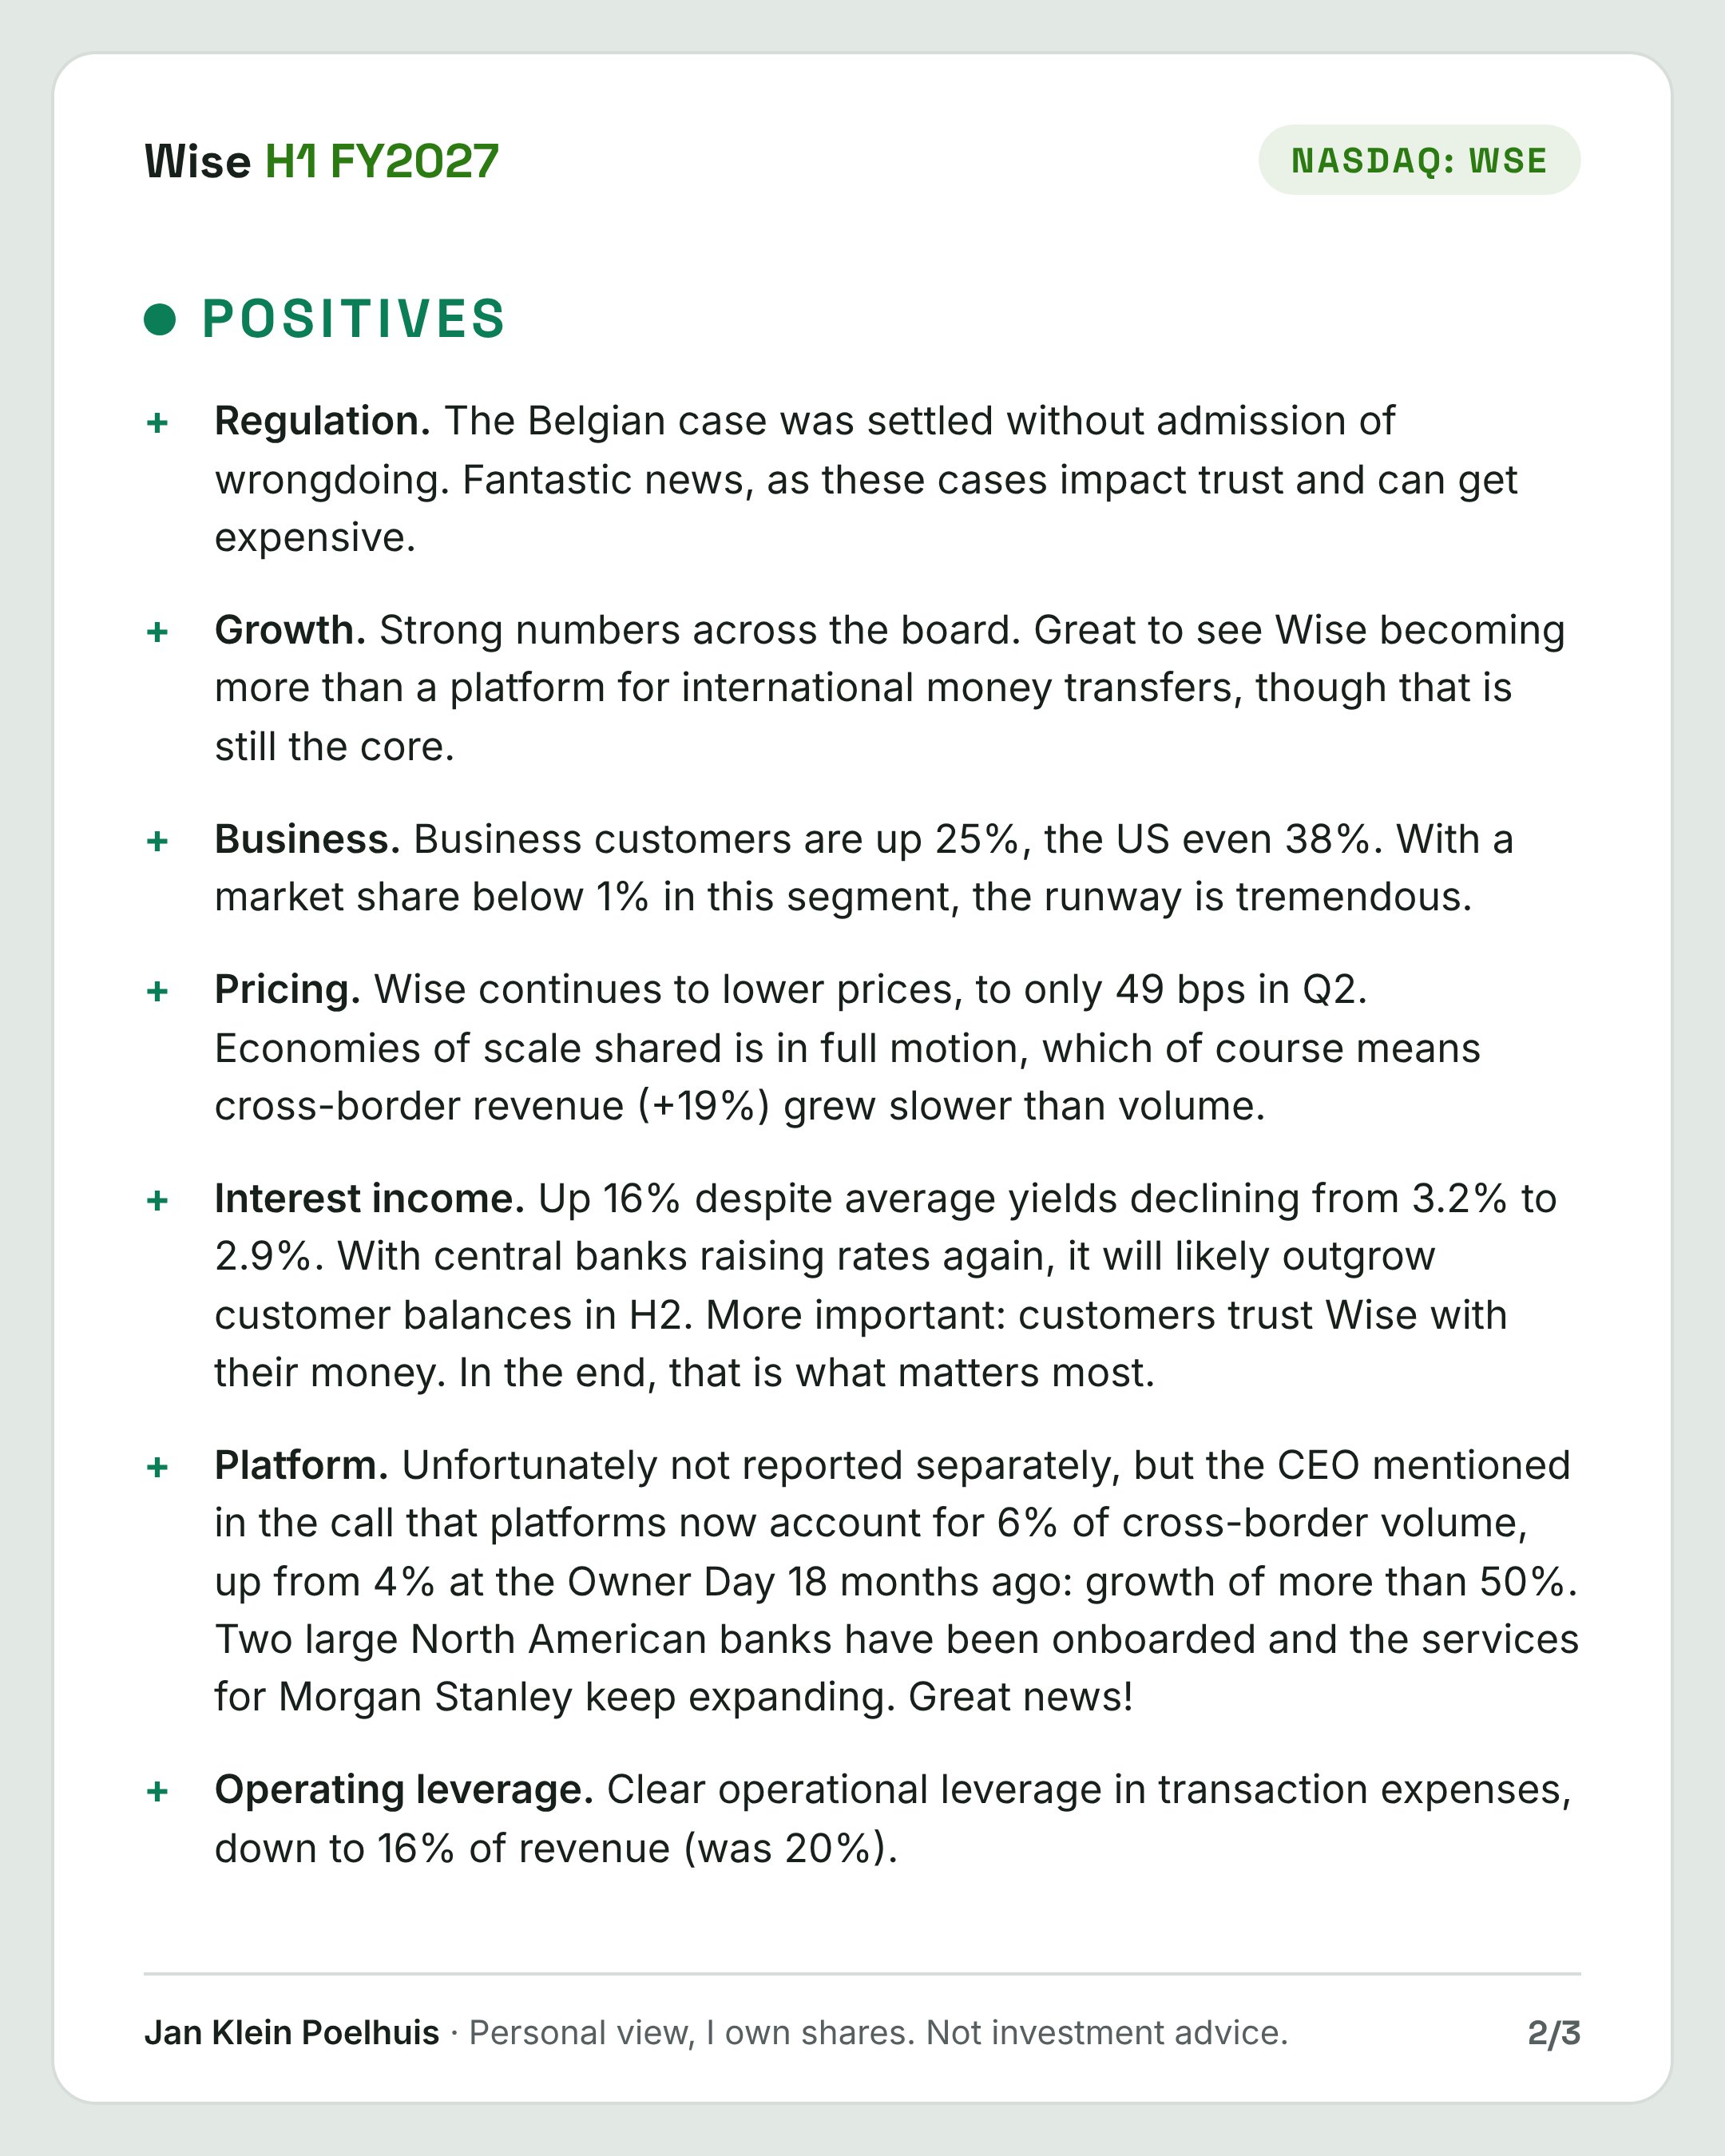
$WSE is perhaps one of the more misunderstood stocks in my portfolio. Lowering cross-border fees on purpose is just so counterintuitive. But Wise has created a flywheel that at this point is very hard to slow down. At today's price I expect roughly 15% a year, so I feel very optimistic about the valuation. In hindsight, I might have slightly overpaid at >£11 early 2025. As always, happy to hear opposing thoughts!


Funny to see that the strongest offensive language often comes from the anonymous accounts who lack the courage to post under their own title.

It is striking to see how investors are willing to put aside their values when their wallets are impacted. Whether that one lady was a spie or not, does it matter? Having an affair within the company is a violation of Nvidia’s policy and more important, integrity of the individual.
1
3
701
It is striking to see how investors are willing to put aside their values when their wallets are impacted. Whether that one lady was a spie or not, does it matter? Having an affair within the company is a violation of Nvidia’s policy and more important, integrity of the individual.

BREAKING: Jensen Huang is considering returning to Nvidia, $NVDA, as CEO as tech executives pressure the company’s board to reinstate him, per FT.
Huang is reportedly discussing a potential return even as an independent investigation by Nvidia's board is underway.
One "ally" of Jensen Huang is reportedly putting together a "war room" of tech executives to lobby for his return.
It's going to be an interesting week to say the least.

Jan Klein Poelhuis retweeted

Wie betaalt in Nederland de rekening?
6,3 miljoen fte verdienen hun salaris in de markt. (🔴)
2,1 miljoen fte worden betaald uit belasting en premies. (⚫️)
Dat is 3 op 1. Elke ambtenaar en elke zorgbaan rust op drie mensen die het eerst moeten verdienen.
En dat zijn niet de multinationals. De top 100 bedrijven is goed voor 500.000 fte. Het mkb voor 2,7 miljoen, ruim 5 keer zoveel.
De bakker, de installateur en de zzp'er betalen uw en mijn welvaart.
Toch is de publieke sector sinds 2018 met 16% gegroeid en worden ondernemers nu met de hoogste belastingen op hun pensioenpotten weggezet.
Bron: CBS

Yesterday I pulled the trigger and sold my $BN position. It was a tough call, since great investors like @BillAckman and Tom Gayner are bullish on the company. That said, I think it’s important to play a game that matches your own investment style and personality. After almost three years, I still kept questioning my Brookfield position. I’d rather spend those brain cycles on positions with a larger weight in the portfolio. This was not an easy call, and I could very well be wrong.


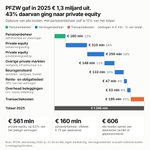
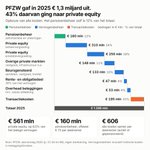
Kan het pensioenfonds PFZW (Pensioenfonds Zorg en Welzijn) 60% van de kosten besparen is de vraag? Ik ben er samen met Fable 5.2 mee aan de slag gegaan.
Het pensioenbeheer maakt slechts 12% uit van de totale kosten. Dus wat mij betreft komt '88%' van de totale €1,3 miljard in aanmerking voor een schoonmaakbeurt. Let's dive in!
Wat blijkt, liefst 43% van de kosten komt voor rekening van private equity met een jaarlijks netto rendement van 3% tussen 2022-2025 versus 9,1% netto rendement voor aandelen. Ook over een langere periode doen aandelen het minstens 250 bps beter. Dit geld gaat grotendeels naar externe managers.
Kan dit pensioenfonds 60% besparen op de kosten? Die conclusie mag een ieder voor zichzelf trekken. Ik durf de conclusie wel te trekken dat deelnemers van dit soort pensioenfondsen nul profijt hebben van deze dure instellingen en dat de 'diversificatie' naar PE-fondsen een dure hobby van het management is.


Minstens 60%? Graag onderbouwing. Inclusief meenemen van taken als o.a. pensioenrechten administreren, premies verwerken, uitkeringen doen, deelnemers informeren, renterisico beheren, verschillende leeftijdscohorten bedienen en pensioenrisico's delen. En het risicoprofiel.
2
5
672
@beursanalist. Wellicht een leuke aangezien je laatste berichten ook over dit soort pensioenfondsen gingen.
298
Last week I said I'd take a proper look at $BRK.B before making up my mind. The work is done, and I'd genuinely like your pushback.
My sum-of-the-parts valuation (balance sheet 30 Sep 2026) comes to $445 per B share. At $571 the stock trades about 28% above that. Put differently: the market pays ~23x normalised earnings for the operating businesses, where I use ~15x on average.
The part I find most interesting is the bridge to Chris Bloomstran's valuation ($570 at year-end 2025). We largely agree on earnings power. The gap is mainly in two choices:
1. Float. I deduct the $178.5 bn in full; he treats it as equity. Together with deferred tax that is ~$106 per share.
2. Multiples. He pays ~19.8x for BNSF, BHE and MSR, I pay 15.6x. That's another ~$43.
With his treatment of float and tax but my multiples, I get ~$551. So whether Berkshire looks expensive depends more on how you view float than on the operating businesses.
What matters more in the end is how fast intrinsic value grows. The operating businesses grow slowly, so a lot rests on putting ~$357bn of cash to work at better returns. I realistically expect 8–9% a year from here. Fine, but a bit below what I'm looking for, so I'm considering trimming Berkshire with 20-40%.

In the coming week, I will devote quite some time to make up my mind about $BRK.B. It’s hard for me to criticise the company, as doing so feels like implicitly letting my role model Buffett down. But my gut feeling is giving me signals that Berkshire at $570 is quite richly valued. Especially since their more recent capital allocation decision (Oxychem, Pilot, Bending Spoons) are hard for me to get really excited about (in fact: perhaps the opposite is true). As always happy to hear pushback and/or input before doing the work. Will share the outcome when done of course.
Interesting take from @oost_marcel and exactly the reason why I’m long $ADYEN. Being a shareholder is no walk in the park as both communication and capital allocation can significantly improved. But I feel that the current valuation provides enough margin to absorb that impact.

@stripe 's last tender valued it at about 5.5x @Adyen 's market value, on only about 1.2x the payment volume 🤯
That valuation gap is hard to ignore. 159B vs. 29B.
Here are the numbers:
→ Stripe's private valuation rose ~74% in the year to February
→ Adyen trades at ~21x last year's EBITDA
→ Adyen's payment volume grew 30% in Q3
→ Stripe's Revenue suite is heading for a $1B annual run rate
And the comparison just got more interesting.
Adyen lowered its 2026 margin outlook as it keeps investing following the acquisitions of Talon One and Orb.
Its shares dropped ~13% on the day: bit.ly/4BA7KyG
But Adyen's payment volume growth has accelerated sharply:
From just 8% for full-year 2025 (dragged down by one large customer) to 30% in Q3.
Stripe, meanwhile, says it remains "robustly profitable" but doesn't disclose the number.
And that's an important difference.
Adyen gets judged by the public markets every quarter.
Stripe gets repriced through private tenders.
Both are investing heavily.
Both are growing.
But one is currently valued at roughly 5.5x the other.
Is that gap justified?
Want a closer look at how Stripe and Adyen really compare? 👉 Read my full deep dive into their latest financial results, growth, profitability, and valuations here: lnkd.in/dhjntqXp

In the coming week, I will devote quite some time to make up my mind about $BRK.B. It’s hard for me to criticise the company, as doing so feels like implicitly letting my role model Buffett down. But my gut feeling is giving me signals that Berkshire at $570 is quite richly valued. Especially since their more recent capital allocation decision (Oxychem, Pilot, Bending Spoons) are hard for me to get really excited about (in fact: perhaps the opposite is true). As always happy to hear pushback and/or input before doing the work. Will share the outcome when done of course.
Jan Klein Poelhuis retweeted

Video for today
🤖 Made with AI


