

CEO of @pogun_io | you can’t pool your way to a bond
Amsterdam | Barcelona | EU
Joined July 2017
- Tweets1.2K
- Following722
- Followers1.1K
- Likes2.3K


Pinned Tweet
Gave into the trend and wrote a piece on Vaults.
Crypto should be moving beyond “trust me, bro” finance. Vaults are a perfectly legitimate trust layer when delegated judgment is the product, but they are still a layer. The cleaner architecture is to start from the right primitive for the market: a loan when the product is credit, a pool when the product is liquidity, a vault when the product is allocation. The wrapper should simplify the underlying object, not compensate for its absence.
@blocksmithy @pogun_io @DonAntonioHS @LucaProsperi @__fallen_icarus

Omer Husain retweeted
Two things I’ve been thinking about regarding AI:
• People often highlight the risks involved in AI, which are surely very real. I’m struck, however, by how hard it is to understand the contours of the positive scenario. There are easy-to-perceive and frequently invoked elements of a positive vision — more diseases cured, more material abundance, etc. — which sound great, but these are by themselves just ingredients. I’m curious what the larger equilibrium is supposed to look like. Do people work? If so, why? What is their marginal contribution? If not, how are resources allocated? What is scarce? What is the ratio between humans and AIs? Are humans in control, whatever that means? One sometimes hears the Culture novels invoked as one scenario, but I’m not sure they depict a desirable outcome. (AI runs everything and humans compete in games? Iain Banks himself said that the humans in the Culture are “somewhere between passengers, pets and parasites.”) There is Richard Brautigan’s famous poem, but do we want to be “returned to our mammal brothers and sisters”? (Isn’t that rewinding Genesis?) We could say that it was hard to imagine the world of 1900 from the vantage point of 1700, and that’s assuredly true. But nobody in 1700 was trying to recast humanity itself within a couple of years — things necessarily unfolded slowly and by increments, and therefore with the possibility for error correction. Given how rapid the rate of progress in AI may be, it feels strange for the upside case to be so opaque.
• There is increasing discussion of whether AIs are conscious or how we would know whether they are, with conclusions there often assumed to be relevant to matters of moral worth. At first blush, this seems a rather arcane, benign, or even absurd issue. (Remember the response to Blake Lemoine’s fears.) Setting aside the terms of the debate itself, or the relevant demarcation criteria, it seems to me a quite high-stakes question, for an affirmative answer — that is, granting moral worth to AIs — would presumably mean that the aggregate worth of AIs would soon outweigh that of humans in any utilitarian calculus. The AIs will be exceptionally wise and intelligent, and vastly more numerous (especially once one considers the imminent future and the AIs not yet born). As such, even epsilon of moral worth will multiply to a lot once one considers the quadrillions that could soon exist. (This is effectively a distributed version of the Nozick’s utility monster.) If this conclusion is unpalatable, I think one of three propositions needs to be rejected: the premise AIs can have moral worth; utilitarianism itself; or the belief that there is even a possibility that they will be far more numerous than humans.
With both of these matters (contours of future society; AI moral worth), there is the possibility of dramatic change. Today, people argue about datacenters. I’m curious how popular support for AI will evolve as more people come to understand these medium-term questions and the relevant stakes. What is the vision for AI that most people would be excited about?
This should signal where crypto is going.
Tokenized collateral needs to be made productive at an institutional level.
This needs thinking about concepts from first principles.
You can either segregate a vault (shrink a wrapper), or design a loan (build the primitive).
It’s hard to imagine we’ll get to keep on redesigning the wrapper or focussing on ‘tokenization’ everything. Who cares about tokenizing an asset that if it doesn’t enable something new.

You've followed what we're building. Now, drive the strategy.
DMs are open for believers:
➤ Head of Digital Assets Product Strategy
➤ Head of Franklin Crypto Capital Formation
➤ Head of Franklin Crypto Private Credit
➤ Program Manager, Digital Audience Engagement
➤ VP, Business Development, Crypto Markets
Ready to shape the future?
⬇ ⬇ ⬇ ⬇ ⬇
Omer Husain retweeted

Our yield is currently sitting at 12.1%. Let that sink in 🗣️
While everyone is chasing the next narrative, @realfi_co is focused on what actually matters: putting capital to work and bringing real-world returns on-chain.
We’re building at the intersection of DeFi and real-world finance, where stablecoins can do more than just sit in your wallet.
The opportunity is here. And we’re just getting started.
Explore RealFi now 👇
app.realfi.co/insights


Omer Husain retweeted

"I'm a big advocate of taking a ship, blowing as many holes in it, and if it still floats, it works."
@kpperdelwitz of @GigaBTC on what June's drawdown actually settled — and why Guillaume Bajczman of @roxom and @omerh_ of @pogun_io read the same two months differently.
With @JakeFentonBTC at @BitcoinConfAsia in Hong Kong.
Omer Husain retweeted

Tokenization has proven its potential. Now comes the challenge of making it mainstream.
From moving beyond pilot projects to driving real-world adoption, the discussion is shifting toward what it takes to make tokenization work at scale.
At the Digital Assets & Tokenization Summit Singapore, Alice Liu (@AliceCrypto3) from @CoinMarketCap moderated a discussion with Omer Husain (@omerh_) from @pogun_io, Ehud Tal from @Sailo_Tech and Duncan Moir (@Duncanmoir) from @21shares on what needs to happen next.

Omer Husain retweeted

Morpho has recorded ~$46M in negative earnings since Q4 2024.
At the same time, it has generated hundreds of millions in gross protocol revenue.
So how does that make sense? Well, the answer is that @Morpho currently captures none of the economic activity flowing through the protocol.
Borrowers pay interest to lenders, and liquidation fees also flow out of the protocol. So, Morpho's current take rate is 0%. This has arguably been one of the biggest drivers behind Morpho's growth.
That means its income statement since Q4 2024 looks roughly like this:
> Hundreds of millions in gross protocol revenue
> $0 gross profit
> ~$46M spent on incentives
> Negative ~$46M in earnings
This isn't because the underlying lending markets aren't generating money, but because Morpho is choosing not to monetize them yet, while simultaneously spending to incentivize growth.
It gets interesting, though, as Morpho already has the ability to turn on protocol fees. Governance can activate fees on individual markets and capture up to 25% of borrower interest. It just hasn't.
For some perspective, borrowers paid ~$177M in interest over the last four completed quarters alone.
> A hypothetical 5% take rate on that would represent ~$8.9M.
> 10% would represent ~$17.7M.
> 25% would represent ~$44.3M
Of course, this isn't free money. Any fee captured by the protocol is value that no longer goes to suppliers, which could make Morpho markets less competitive and potentially impact liquidity and growth. But it makes Morpho's current strategy pretty interesting.
Right now, the protocol is effectively prioritizing growth, liquidity and distribution over monetization.
Grow supply → attract borrowers → increase economic activity → establish Morpho as lending infrastructure → potentially monetize a much larger base later.
So when looking at Morpho's income statement, the negative earnings don't tell you that the lending business itself is unprofitable, but instead that Morpho is spending money to grow while choosing to capture almost none of the economics its lending markets generate.
The bigger question is what happens if, or when, the fee switch is activated, especially now that we're already seeing protocols like @SentoraHQ getting ready to deploy their own lending markets on top of @aave V4.


Omer Husain retweeted
Big day. @realfi_co is officially live on Cardano Mainnet 🎉
Everything we've built together over the past few months has led to this moment. Welcome to the next chapter.
Experience the Voyager Season now at app.realfi.co
Read more! 👇


Omer Husain retweeted

It hardly makes any sense.
Vaults in Morpho exist to solve a UX problem, as users simply cannot track thousands of markets themselves. But vaults do not offer much additional protection to users. In fact, they significantly reduce user protection compared to depositing directly into a market.
The absolute majority of users will not understand what changes are being introduced under a 1-day timelock, even if they somehow decide to monitor the vault 24/7. And the existence of a timelock does not mean that every investment decision made by the curator is implicitly approved by the lender.
Coming back to the first point, Paul says that “the vault turns the complexity of tracking thousands of markets into a single set of predetermined rules that allocates across many markets at once.” But now the user effectively has to monitor the thousands of markets the curator allocates to. And if the funds are mismanaged, we can suddenly say that this was done with the user's “explicit or implicit” approval.
And I am not even talking about situations where curators use their “discretionary” vaults as collateral within their non-custodial vaults. What is the vault called in that situation?
I do not think Paul is naive enough to believe that these vaults are “non-custodial”. Rather, he seems to want others to believe in that.


A distribution deal is not a network effect. The test is whether adding one partner makes the market more useful to everyone already in it.
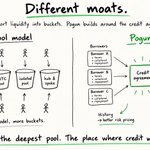
Lending pools compete on liquidity depth. Isolated pools and hub-and-spoke designs change how capital and risk are organised, but reorganising liquidity does not, by itself, create a market for individually negotiated credit. At Pogun, we start with the loan agreement, not the pool.
The first moat we’re working towards is market density. Wallets, exchanges and custodians bring borrowers into the same market of independent lenders. More borrowers give lenders more opportunities; more lenders give borrowers a better chance of finding suitable terms. A new distribution partner should improve funding opportunities across the network—not just create another captive bucket.
The second is credit history that supports more specific risk pricing. As repayment, renewal and default records accumulate, lenders can assess the borrower and the individual loan—not just collateral ratios and pool utilisation. The advantage isn’t collecting data. It’s helping lenders distinguish risks they previously had to price alike.
The third is a market for the loan claims. Each loan remains independent, but its lender’s claim can change hands. Building a base of buyers could give lenders an exit without requiring the borrower to repay early. Transferability alone isn’t liquidity; attracting those buyers is the work.
None of this makes us immune to distributors shopping around. But the defence we’re building is access to a credit market, not dependence on a particular integration. Distribution brings participants in. Better funding options, more informed pricing and a market for their claims give them reasons to stay.
The loans stay independent. The market is shared.
🤖 Made with AI


I too would write a love letter about partnering with competitors if I’d paid Robinhood $100m + for the privilege lol.
The funniest part is coinbase then turning around and bringing aave in as a credit layer for tokenised stocks.
The issue here is the conflating of distribution with a network effect that somehow accrues to morpho.
Coinbase using morpho doesn’t make robinhood more dependent on morpho and vice versa, If anything, every big distributor you add has more incentive to make sure the credit layer stays competitive and replaceable.
And I don’t think “we power your biggest competitor too” after paying them an insane amount of money is quite the flex to coinbase that you think it is.
The base + Aave stuff on tokenised stocks is basically showing you the model in real time.
Coinbase and RH own the users and distribution, they can shop the credit layer around product by product and make the protocols compete underneath them which is exactly what RH did and why you ended up massively overpaying.
It’s basically the supermarket model they own the shelf space while you’re fighting to be stocked which means:
You’re not the network.
You’re a vendor to the network.
Omer Husain retweeted

This is such a based take and a good lesson for other protocols doing similar deals.
nitter.cf/bryancolligan/status/2…
I too would write a love letter about partnering with competitors if I’d paid Robinhood $100m + for the privilege lol.
The funniest part is coinbase then turning around and bringing aave in as a credit layer for tokenised stocks.
The issue here is the conflating of distribution with a network effect that somehow accrues to morpho.
Coinbase using morpho doesn’t make robinhood more dependent on morpho and vice versa, If anything, every big distributor you add has more incentive to make sure the credit layer stays competitive and replaceable.
And I don’t think “we power your biggest competitor too” after paying them an insane amount of money is quite the flex to coinbase that you think it is.
The base + Aave stuff on tokenised stocks is basically showing you the model in real time.
Coinbase and RH own the users and distribution, they can shop the credit layer around product by product and make the protocols compete underneath them which is exactly what RH did and why you ended up massively overpaying.
It’s basically the supermarket model they own the shelf space while you’re fighting to be stocked which means:
You’re not the network.
You’re a vendor to the network.
Omer Husain retweeted
DATs expose the asset.
Pogun turns that asset into credit — without forcing a sale, a wrap, or a liquidation on price.
That’s when treasury assets become productive capital.
@omerh_ @blocksmithy

DATs are heating up.
The original PIPEs were losers because everyone had the trade backwards.
Now liquid funds are realizing that when a DAT trades below 1x mNAV, you can get more token exposure per dollar.
At 0.33x mNAV, you’re effectively getting ~3x the exposure to the underlying token…if you believe the discount eventually closes.


Omer Husain retweeted
Bridges get hacked. If you crack a Mirror, it’s 7 years of bad luck.
Our auditors are trying their best.
@IOHK_Charles @omerh_

Around 4,000 BTC left a bridge on Sunday. No key was compromised. The signers signed a withdrawal that was correct by every rule they could check, because the sidechain software had created coins indistinguishable from everyone else's. Twenty-three minutes after those coins reached the peg-out service, the payment was on Bitcoin.
Everything worked as designed. Three properties of that design decided the outcome, and none of them is about honesty.
@pogun_io @omerh_