

Investor | Uncovering high-potential stocks & market anomalies | AI enthusiast | Founder of LARYA AI, a real estate technology startup.
Joined January 2026
- Tweets338
- Following71
- Followers654
- Likes770






Pinned Tweet
🚨 $OPEN — POSSIBLE ALGORITHMIC MARKET MANIPULATION.
@nejatian — I am addressing this directly to you as CEO of Opendoor.
After weeks of forensic work on $OPEN trading, I believe our findings justify review by Opendoor, Nasdaq, FINRA and potentially the SEC.
As an $OPEN shareholder, I can provide the complete dataset, order IDs, timestamps, code and methodology.
We reconstructed ~2.23 MILLION individual orders across Nasdaq, NYSE Arca, Cboe BZX, EDGX and MEMX, covering ~86% of observed volume: MBO/L3 orders, executions, cancellations, off-exchange trades, auctions, options and short-sale data.
Thousands of quantitative tests: regressions, event studies, cross-venue synchronization, market-impact models, VPIN and order-lifecycle reconstruction.
The findings raise serious questions about potential algorithmic market manipulation.
From Sep 9–17 alone, 14:00–15:00 ET produced −4.94M shares of aggressive net flow, negative in 6/7 sessions.
But the key evidence is inside the book.
📍 SEP 9 — 11,200
An 11,200-share SELL executes @ $3.05.
Then 335 SELL orders of exactly 11,200 shares appear.
326/335 — 97.3% — disappear within ONE SECOND.
After $OPEN trades lower:
🟢 BUY 11,200 @ $3.00 → EXECUTED.
SELL → REPEATED SUPPLY → CANCEL → LOWER PRICE → BUY
If CAT links these actions to the same beneficial owner/coordinated accounts, regulators can determine whether displayed supply influenced price discovery before a lower execution.
📍 SEP 17 — THE $2.57 WALL
172 SELL orders of exactly 14,500 shares.
167/172 — 97.1% — cancelled within one second.
Around 108 identical 14,500-share SELL orders repeatedly appear around $2.57 while genuine selling hits $OPEN.
Median lifetime:
~78 MILLISECONDS.
Same size. Same price. Appear. Disappear. Repeat.
Genuine liquidity — or the appearance of a larger sell wall than actually intended for execution?
📍 SEP 24 — THE CLOSE
Nasdaq SELL imbalance jumps:
354K → 970K → 1.17M shares in ~20 seconds.
At virtually the same time, selling appears across ALL FIVE exchanges.
Around 15:54:40 ET, in ~ONE SECOND:
🔴 ~134,060 aggressively SOLD
🟢 ~810 aggressively BOUGHT
~165 : 1
Nasdaq. Arca. EDGX. BZX. MEMX.
The five venues finish at approximately −822K shares of identified aggressive net flow.
⸻
THESE ARE ONLY EXAMPLES.
Across the five-exchange sample:
🔴 38,076 large fleeting SELL orders
🔴 ~353M shares of cumulatively displayed sell liquidity
A stricter test — 5,000+ share orders appearing before an opposite-side execution and cancelled within 50ms — identified:
68,524 SELL-side candidate sequences
vs 49,769 BUY-side
= 18,755 more SELL occurrences.
We also tested thresholds down to 5 milliseconds.
These totals alone don’t prove manipulation; high-frequency activity exists on both sides. But the specific fingerprints come from tens of thousands of order/cancellation sequences and deserve account-level investigation.
WE DOCUMENTED:
• persistent aggressive selling
• identical non-round SELL orders
• 97%+ cancellation rates in specific fingerprints
• lifetimes measured in milliseconds
• apparent sell walls
• auction imbalances
• simultaneous cross-exchange selling
These patterns overlap with spoofing/layering when non-bona-fide liquidity creates misleading supply/demand while genuine transactions obtain an economic advantage.
The decisive question: WHO controlled these orders?
Public data cannot answer it. The Consolidated Audit Trail (CAT) can.
@nejatian , I hope you and @Opendoor take this seriously. I can provide the entire analysis and dataset immediately.
If Opendoor does not act, on Monday, as an @Opendoor shareholder, I intend through legal counsel to submit the prepared documentation directly to the SEC and appropriate regulators for independent review and to protect Opendoor shareholders’ interests.
The data, order IDs, timestamps and anomalies exist. Now they deserve to be investigated.
@rabois @ericjackson @mikealfred

Quantum Leopard retweeted
$SMCI just discovered a new law of physics: astronomical earnings, catastrophic stock performance. 🤡📉
$SMCI just discovered a new law of physics: astronomical earnings, catastrophic stock performance. 🤡📉
Quantum Leopard retweeted
THEY’RE DEMOCRATS, NOT IDIOTS. 🇺🇸😂
Wall Street is panicking over Democratic governors and data center restrictions.
But I think the market is missing something fundamental.
Since when does slowing down the construction of a factory mean its customers no longer need the product?
Think about it.
The AI revolution doesn’t exist because politicians approve building permits.
It exists because companies need computing power. And that demand doesn’t magically disappear when a governor signs a moratorium.
Now, let’s look at some facts.
🇺🇸 MICHIGAN: Democratic Governor Gretchen Whitmer supported OpenAI and Oracle’s massive 1 GW Stargate campus. Construction is already underway, with hundreds of workers on site.
🇺🇸 PENNSYLVANIA: Democratic Governor Josh Shapiro welcomed Amazon’s planned $20 BILLION AI infrastructure investment. He then introduced tougher rules requiring developers to protect communities and cover their energy costs.
🇺🇸 GEORGIA: Newly elected Democratic Governor Keisha Lance Bottoms has called for a pause on new projects to assess their impact. She has also indicated she doesn’t support a permanent shutdown.
And here’s my favorite part:
TEXAS — REPUBLICAN Governor Greg Abbott had ALREADY frozen new data center permits before the election!
So please, explain to me again how this is suddenly a Democrats-versus-AI story. 😂
Now let’s talk about what Wall Street seems to be forgetting.
According to CBRE, across North America’s eight largest data center markets:
📊 80.4% of capacity under construction is already preleased.
📊 Vacancy is just 1.4%.
📊 Construction capacity increased 24.8% in H1 2026.
Read those numbers again.
The industry is facing a serious shortage of deliverable capacity, not an obvious collapse in customer demand.
And here’s where things get really interesting.
What happens when demand remains strong but new supply becomes harder to build?
Existing facilities with secured power and permits can become MORE valuable.
Developers may move projects to other states or invest in upgrading existing infrastructure.
And companies capable of delivering reliable, on-site electricity could become increasingly important.
Of course, delays can hurt developers, postpone server orders and increase costs. I’m not ignoring those risks.
But let’s distinguish between a supply bottleneck and a demand collapse.
They’re not the same thing.
And politicians have powerful economic incentives to get this right: investment, jobs, tax revenue, energy infrastructure and America’s technological competitiveness.
Nobody wants households subsidizing billion-dollar data centers. Requiring developers to pay their fair share is entirely reasonable.
The question isn’t whether America needs AI infrastructure. It’s how, where and at whose expense it gets built.
The U.S. is competing for technological leadership. China isn’t going to stop building computing infrastructure while American politicians debate electricity bills.
And that brings me to my investment thesis.
I think Wall Street may be pricing a political permitting problem as if it were the end of the AI infrastructure boom.
That’s a very different risk.
And today, I decided to do a little shopping. 🛒
💻 $SMCI — Super Micro Computer: The servers and AI systems.
☁️ $CRWV — CoreWeave: The computing capacity.
⚡ $BE — Bloom Energy: The electricity needed to power it all.
Three businesses, three parts of the same infrastructure chain.
I see the current fear as an opportunity to build exposure to a long-term transformation, while keeping the execution risks firmly in mind.
You can delay a building permit. You can’t legislate away the need for computing power.
THE AI REVOLUTION ISN’T A RED OR BLUE PROJECT. IT’S AN AMERICAN INDUSTRIAL PROJECT. 🇺🇸🚀
🤖 Made with AI

THEY’RE DEMOCRATS, NOT IDIOTS. 🇺🇸😂
Wall Street is panicking over Democratic governors and data center restrictions.
But I think the market is missing something fundamental.
Since when does slowing down the construction of a factory mean its customers no longer need the product?
Think about it.
The AI revolution doesn’t exist because politicians approve building permits.
It exists because companies need computing power. And that demand doesn’t magically disappear when a governor signs a moratorium.
Now, let’s look at some facts.
🇺🇸 MICHIGAN: Democratic Governor Gretchen Whitmer supported OpenAI and Oracle’s massive 1 GW Stargate campus. Construction is already underway, with hundreds of workers on site.
🇺🇸 PENNSYLVANIA: Democratic Governor Josh Shapiro welcomed Amazon’s planned $20 BILLION AI infrastructure investment. He then introduced tougher rules requiring developers to protect communities and cover their energy costs.
🇺🇸 GEORGIA: Newly elected Democratic Governor Keisha Lance Bottoms has called for a pause on new projects to assess their impact. She has also indicated she doesn’t support a permanent shutdown.
And here’s my favorite part:
TEXAS — REPUBLICAN Governor Greg Abbott had ALREADY frozen new data center permits before the election!
So please, explain to me again how this is suddenly a Democrats-versus-AI story. 😂
Now let’s talk about what Wall Street seems to be forgetting.
According to CBRE, across North America’s eight largest data center markets:
📊 80.4% of capacity under construction is already preleased.
📊 Vacancy is just 1.4%.
📊 Construction capacity increased 24.8% in H1 2026.
Read those numbers again.
The industry is facing a serious shortage of deliverable capacity, not an obvious collapse in customer demand.
And here’s where things get really interesting.
What happens when demand remains strong but new supply becomes harder to build?
Existing facilities with secured power and permits can become MORE valuable.
Developers may move projects to other states or invest in upgrading existing infrastructure.
And companies capable of delivering reliable, on-site electricity could become increasingly important.
Of course, delays can hurt developers, postpone server orders and increase costs. I’m not ignoring those risks.
But let’s distinguish between a supply bottleneck and a demand collapse.
They’re not the same thing.
And politicians have powerful economic incentives to get this right: investment, jobs, tax revenue, energy infrastructure and America’s technological competitiveness.
Nobody wants households subsidizing billion-dollar data centers. Requiring developers to pay their fair share is entirely reasonable.
The question isn’t whether America needs AI infrastructure. It’s how, where and at whose expense it gets built.
The U.S. is competing for technological leadership. China isn’t going to stop building computing infrastructure while American politicians debate electricity bills.
And that brings me to my investment thesis.
I think Wall Street may be pricing a political permitting problem as if it were the end of the AI infrastructure boom.
That’s a very different risk.
And today, I decided to do a little shopping. 🛒
💻 $SMCI — Super Micro Computer: The servers and AI systems.
☁️ $CRWV — CoreWeave: The computing capacity.
⚡ $BE — Bloom Energy: The electricity needed to power it all.
Three businesses, three parts of the same infrastructure chain.
I see the current fear as an opportunity to build exposure to a long-term transformation, while keeping the execution risks firmly in mind.
You can delay a building permit. You can’t legislate away the need for computing power.
THE AI REVOLUTION ISN’T A RED OR BLUE PROJECT. IT’S AN AMERICAN INDUSTRIAL PROJECT. 🇺🇸🚀
🤖 Made with AI


Quantum Leopard retweeted
🚨 $OPEN — THE STOCK PRICE TELLS ONE STORY. INSTITUTIONAL FILINGS ARE STARTING TO TELL ANOTHER.
I find what’s happening with Opendoor increasingly interesting.
We’re only at the beginning of the Q3 2026 13F disclosure season. Many institutional investors haven’t reported their September 30 holdings yet.
But the early numbers are already worth paying attention to.
📊 Across the filings analyzed so far:
🟢 Approximately 5.6 MILLION shares added.
🔴 Approximately 850K shares reduced or sold.
🟢 NET: Nearly +4.8 MILLION SHARES.
And that’s AFTER accounting for the reported selling in this preliminary sample.
Daiwa Securities alone increased its position by approximately 4.4 million shares (+94%).
Sullivan Wood reported a new position of more than 500,000 shares.
Of course, some institutions have reduced their exposure. I’m not ignoring that. But the preliminary net balance remains positive, largely driven by a few significant buyers.
Now think about the contradiction.
If I looked only at the stock price, I’d think everyone was running for the exits.
But that’s not what these early ownership disclosures suggest.
And this brings me back to something I’ve been saying for a long time.
I strongly suspect that $OPEN is experiencing aggressive short pressure, algorithm-driven selling and repeated shakeouts that are testing the conviction of retail investors.
I cannot prove coordinated market manipulation from these filings alone. But I believe the disconnect between the price action and the underlying business deserves serious attention.
In my view, these violent moves are creating exactly the kind of environment in which frightened retail investors surrender their shares, while investors with deeper pockets may be quietly accumulating.
And here’s what makes this situation even more extraordinary.
While the stock price has been under pressure, I continue to see progress in Opendoor’s underlying business:
🟢 Acquisition activity and transaction volumes.
🟢 Resale execution and inventory turnover.
🟢 Operational efficiency and execution speed.
🟢 New products, technology releases and platform improvements.
🟢 A strengthening technological foundation and competitive positioning.
Month after month, I’m watching a company working to improve its operating engine, expand its capabilities and strengthen the technology behind its business.
Yet the market seems obsessed with the daily red candles.
I believe there’s a massive difference between a company whose fundamentals are deteriorating and a stock whose price is being relentlessly pressured.
And I suspect some sophisticated investors understand that difference perfectly.
Could larger players be accumulating shares while exhausted retail investors finally capitulate?
I think that’s a possibility worth taking very seriously.
The 13F disclosure season is far from over. I’ll continue tracking both purchases and sales, because the complete picture matters.
But the first signals certainly don’t look like the universal institutional exodus the stock price might lead people to believe.
I know what I’m holding.
I know what I’m watching.
And I’m not letting the daily price action define the entire investment thesis.
LONG $OPEN.
LONG OPENDOOR — THROUGH THE STORM. 🌪️
🤖 Made with AI

🚨 $OPEN — THE STOCK PRICE TELLS ONE STORY. INSTITUTIONAL FILINGS ARE STARTING TO TELL ANOTHER.
I find what’s happening with Opendoor increasingly interesting.
We’re only at the beginning of the Q3 2026 13F disclosure season. Many institutional investors haven’t reported their September 30 holdings yet.
But the early numbers are already worth paying attention to.
📊 Across the filings analyzed so far:
🟢 Approximately 5.6 MILLION shares added.
🔴 Approximately 850K shares reduced or sold.
🟢 NET: Nearly +4.8 MILLION SHARES.
And that’s AFTER accounting for the reported selling in this preliminary sample.
Daiwa Securities alone increased its position by approximately 4.4 million shares (+94%).
Sullivan Wood reported a new position of more than 500,000 shares.
Of course, some institutions have reduced their exposure. I’m not ignoring that. But the preliminary net balance remains positive, largely driven by a few significant buyers.
Now think about the contradiction.
If I looked only at the stock price, I’d think everyone was running for the exits.
But that’s not what these early ownership disclosures suggest.
And this brings me back to something I’ve been saying for a long time.
I strongly suspect that $OPEN is experiencing aggressive short pressure, algorithm-driven selling and repeated shakeouts that are testing the conviction of retail investors.
I cannot prove coordinated market manipulation from these filings alone. But I believe the disconnect between the price action and the underlying business deserves serious attention.
In my view, these violent moves are creating exactly the kind of environment in which frightened retail investors surrender their shares, while investors with deeper pockets may be quietly accumulating.
And here’s what makes this situation even more extraordinary.
While the stock price has been under pressure, I continue to see progress in Opendoor’s underlying business:
🟢 Acquisition activity and transaction volumes.
🟢 Resale execution and inventory turnover.
🟢 Operational efficiency and execution speed.
🟢 New products, technology releases and platform improvements.
🟢 A strengthening technological foundation and competitive positioning.
Month after month, I’m watching a company working to improve its operating engine, expand its capabilities and strengthen the technology behind its business.
Yet the market seems obsessed with the daily red candles.
I believe there’s a massive difference between a company whose fundamentals are deteriorating and a stock whose price is being relentlessly pressured.
And I suspect some sophisticated investors understand that difference perfectly.
Could larger players be accumulating shares while exhausted retail investors finally capitulate?
I think that’s a possibility worth taking very seriously.
The 13F disclosure season is far from over. I’ll continue tracking both purchases and sales, because the complete picture matters.
But the first signals certainly don’t look like the universal institutional exodus the stock price might lead people to believe.
I know what I’m holding.
I know what I’m watching.
And I’m not letting the daily price action define the entire investment thesis.
LONG $OPEN.
LONG OPENDOOR — THROUGH THE STORM. 🌪️
🤖 Made with AI
Quantum Leopard retweeted

We are very close to being able to open up Opendoor's scale advantage to everyone who wants to buy a home, whether that is an Opendoor home or not.
Quantum Leopard retweeted
👀 @mikealfred , newly appointed to Opendoor’s Board of Directors, just liked my post about a potential $OPEN buyback.
I find that timing very interesting. 🚀
Long Opendoor — Through the Storm.

👀 @mikealfred , newly appointed to Opendoor’s Board of Directors, just liked my post about a potential $OPEN buyback.
I find that timing very interesting. 🚀
Long Opendoor — Through the Storm.
Quantum Leopard retweeted
If buying back $OPEN at $3.49 made sense, what does $1.80 represent today?
I’d love to hear management’s perspective. Has the thesis changed, or just the price?
Long Opendoor — Through the Storm 🌪️
@mikealfred @nejatian @rabois
If buying back $OPEN at $3.49 made sense, what does $1.80 represent today?
I’d love to hear management’s perspective. Has the thesis changed, or just the price?
Long Opendoor — Through the Storm 🌪️
@mikealfred @nejatian @rabois
Quantum Leopard retweeted
Congratulations @mikealfred on joining the Board of Directors of $OPEN
As a long-term shareholder, I’m excited about this appointment. Well deserved, Mike!
Long Opendoor — Through the Storm. 🚀

Congratulations @mikealfred on joining the Board of Directors of $OPEN
As a long-term shareholder, I’m excited about this appointment. Well deserved, Mike!
Long Opendoor — Through the Storm. 🚀
Quantum Leopard retweeted
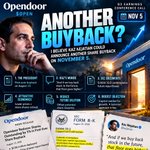
🚨 $OPEN — I BELIEVE @nejatian COULD ANNOUNCE ANOTHER SHARE BUYBACK ON NOVEMBER 5.
And after examining his public statements, SEC filings and Opendoor's capital structure, I believe the clues are too interesting to ignore.
This is not insider information. It is my personal investment thesis, built on publicly available documents and financial reasoning.
1. THE PRECEDENT: AUGUST 13, 2026
Opendoor announced its first-ever share repurchase:
• $158 million deployed
• 45.3 million shares repurchased
• $3.49 per share
• Approximately 5% of outstanding shares retired
The transaction was connected to a $650 million zero-coupon convertible financing, designed to support expansion while limiting shareholder dilution.
Kaz demonstrated something important: he was willing to use sophisticated financial structures to protect shareholder value.
2. THE WORDS THAT CAUGHT MY ATTENTION
Kaz has explicitly expressed the view that Opendoor should repurchase shares when its own stock represents one of the best uses of capital.
But another statement was particularly interesting:
“And if we buy back stock in the future, that floor goes higher.”
He was discussing the $10.38 threshold associated with the dilution protection structured into the August financing.
To me, the reference to future repurchases matters.
He wasn't announcing another buyback. But he was clearly contemplating the possibility.
3. THE SEC DOCUMENT MOST INVESTORS MAY HAVE MISSED
I examined Exhibit 10.2 of the August 13 Form 8-K, the Capped Call Confirmation.
Under its Method of Adjustment provisions, the agreement expressly contemplates:
• Future open-market share repurchases
• Accelerated Share Repurchases (ASRs)
• Forward repurchase arrangements
• Other qualifying transactions
The agreement also establishes specific treatment for qualifying additional repurchases within an aggregate threshold linked to 20% of the shares outstanding at the original transaction date.
And Section 8(e), Repurchase Notices, addresses repurchases carried out under Rule 10b5-1 trading plans.
Important distinction: this is NOT authorization to repurchase 20% of Opendoor. It is a contractual provision governing potential adjustments to the capped calls.
But the existing financing structure expressly accommodates the possibility of additional buybacks.
That deserves attention.
4. THE MATHEMATICS HAVE BECOME EVEN MORE INTERESTING
In August, Opendoor repurchased shares at $3.49.
Now consider a hypothetical share price of $2.
With $100 million:
At $3.49 → approximately 28.7 million shares.
At $2.00 → 50 million shares.
That represents approximately 74.5% more shares retired using exactly the same capital.
If Kaz believed the stock was attractive at $3.49, what does he think about the economics at substantially lower prices?
Of course, the underlying business outlook matters. A lower share price alone does not automatically justify a buyback.
But the capital allocation question becomes increasingly interesting.
5. THERE IS ANOTHER FACTOR: FUTURE DILUTION
Opendoor has substantial outstanding equity-based compensation awards, including performance-related RSUs.
Not all these awards will necessarily vest.
However, reducing future dilution is already a documented priority of Kaz's capital strategy.
A new repurchase program could potentially offset some future share issuance, rather than merely serve as a short-term market signal.
6. THE BIGGEST OBJECTION
Opendoor needs liquidity to acquire homes, expand its operations and execute its turnaround.
I cannot ignore that.
Capital deployed into buybacks is capital unavailable for other investments.
And the August transaction was structured around a convertible financing, not simply financed with excess operating cash.
That is why I am not necessarily predicting an immediate, massive open-market purchase.
A new board authorization, an opportunistic repurchase program or another structured capital transaction could be more plausible.
MY CONCLUSION
I see several pieces of a potentially significant puzzle:
Kaz has already executed a $158 million buyback.
He has explicitly contemplated future repurchases.
The August SEC agreements include mechanisms covering additional buybacks.
The economics of retiring shares become increasingly attractive at lower prices, provided the fundamental investment case remains intact.
And the company has an ongoing strategic reason to pay attention to dilution.
None of this proves that a new buyback will be announced on November 5. I have not found a public authorization for a second program.
But I believe the possibility deserves serious attention ahead of Q3 earnings.
I am watching the upcoming conference call not only for revenue, margins and acquisition growth, but also for one crucial question:
HOW WILL KAZ ALLOCATE CAPITAL TO MAXIMIZE LONG-TERM VALUE PER SHARE?
Could November 5 deliver another surprise?
My conviction in the long-term opportunity remains strong.
Long Opendoor through the storm. 🚀
$OPEN

🚨 $OPEN — I BELIEVE @nejatian COULD ANNOUNCE ANOTHER SHARE BUYBACK ON NOVEMBER 5.
And after examining his public statements, SEC filings and Opendoor's capital structure, I believe the clues are too interesting to ignore.
This is not insider information. It is my personal investment thesis, built on publicly available documents and financial reasoning.
1. THE PRECEDENT: AUGUST 13, 2026
Opendoor announced its first-ever share repurchase:
• $158 million deployed
• 45.3 million shares repurchased
• $3.49 per share
• Approximately 5% of outstanding shares retired
The transaction was connected to a $650 million zero-coupon convertible financing, designed to support expansion while limiting shareholder dilution.
Kaz demonstrated something important: he was willing to use sophisticated financial structures to protect shareholder value.
2. THE WORDS THAT CAUGHT MY ATTENTION
Kaz has explicitly expressed the view that Opendoor should repurchase shares when its own stock represents one of the best uses of capital.
But another statement was particularly interesting:
“And if we buy back stock in the future, that floor goes higher.”
He was discussing the $10.38 threshold associated with the dilution protection structured into the August financing.
To me, the reference to future repurchases matters.
He wasn't announcing another buyback. But he was clearly contemplating the possibility.
3. THE SEC DOCUMENT MOST INVESTORS MAY HAVE MISSED
I examined Exhibit 10.2 of the August 13 Form 8-K, the Capped Call Confirmation.
Under its Method of Adjustment provisions, the agreement expressly contemplates:
• Future open-market share repurchases
• Accelerated Share Repurchases (ASRs)
• Forward repurchase arrangements
• Other qualifying transactions
The agreement also establishes specific treatment for qualifying additional repurchases within an aggregate threshold linked to 20% of the shares outstanding at the original transaction date.
And Section 8(e), Repurchase Notices, addresses repurchases carried out under Rule 10b5-1 trading plans.
Important distinction: this is NOT authorization to repurchase 20% of Opendoor. It is a contractual provision governing potential adjustments to the capped calls.
But the existing financing structure expressly accommodates the possibility of additional buybacks.
That deserves attention.
4. THE MATHEMATICS HAVE BECOME EVEN MORE INTERESTING
In August, Opendoor repurchased shares at $3.49.
Now consider a hypothetical share price of $2.
With $100 million:
At $3.49 → approximately 28.7 million shares.
At $2.00 → 50 million shares.
That represents approximately 74.5% more shares retired using exactly the same capital.
If Kaz believed the stock was attractive at $3.49, what does he think about the economics at substantially lower prices?
Of course, the underlying business outlook matters. A lower share price alone does not automatically justify a buyback.
But the capital allocation question becomes increasingly interesting.
5. THERE IS ANOTHER FACTOR: FUTURE DILUTION
Opendoor has substantial outstanding equity-based compensation awards, including performance-related RSUs.
Not all these awards will necessarily vest.
However, reducing future dilution is already a documented priority of Kaz's capital strategy.
A new repurchase program could potentially offset some future share issuance, rather than merely serve as a short-term market signal.
6. THE BIGGEST OBJECTION
Opendoor needs liquidity to acquire homes, expand its operations and execute its turnaround.
I cannot ignore that.
Capital deployed into buybacks is capital unavailable for other investments.
And the August transaction was structured around a convertible financing, not simply financed with excess operating cash.
That is why I am not necessarily predicting an immediate, massive open-market purchase.
A new board authorization, an opportunistic repurchase program or another structured capital transaction could be more plausible.
MY CONCLUSION
I see several pieces of a potentially significant puzzle:
Kaz has already executed a $158 million buyback.
He has explicitly contemplated future repurchases.
The August SEC agreements include mechanisms covering additional buybacks.
The economics of retiring shares become increasingly attractive at lower prices, provided the fundamental investment case remains intact.
And the company has an ongoing strategic reason to pay attention to dilution.
None of this proves that a new buyback will be announced on November 5. I have not found a public authorization for a second program.
But I believe the possibility deserves serious attention ahead of Q3 earnings.
I am watching the upcoming conference call not only for revenue, margins and acquisition growth, but also for one crucial question:
HOW WILL KAZ ALLOCATE CAPITAL TO MAXIMIZE LONG-TERM VALUE PER SHARE?
Could November 5 deliver another surprise?
My conviction in the long-term opportunity remains strong.
Long Opendoor through the storm. 🚀
$OPEN