

Investor | Uncovering high-potential stocks & market anomalies | AI enthusiast | Founder of LARYA AI, a real estate technology startup.
Joined January 2026
- Tweets338
- Following71
- Followers654
- Likes770






Quantum Leopard retweeted
$SMCI just discovered a new law of physics: astronomical earnings, catastrophic stock performance. 🤡📉
Quantum Leopard retweeted
THEY’RE DEMOCRATS, NOT IDIOTS. 🇺🇸😂
Wall Street is panicking over Democratic governors and data center restrictions.
But I think the market is missing something fundamental.
Since when does slowing down the construction of a factory mean its customers no longer need the product?
Think about it.
The AI revolution doesn’t exist because politicians approve building permits.
It exists because companies need computing power. And that demand doesn’t magically disappear when a governor signs a moratorium.
Now, let’s look at some facts.
🇺🇸 MICHIGAN: Democratic Governor Gretchen Whitmer supported OpenAI and Oracle’s massive 1 GW Stargate campus. Construction is already underway, with hundreds of workers on site.
🇺🇸 PENNSYLVANIA: Democratic Governor Josh Shapiro welcomed Amazon’s planned $20 BILLION AI infrastructure investment. He then introduced tougher rules requiring developers to protect communities and cover their energy costs.
🇺🇸 GEORGIA: Newly elected Democratic Governor Keisha Lance Bottoms has called for a pause on new projects to assess their impact. She has also indicated she doesn’t support a permanent shutdown.
And here’s my favorite part:
TEXAS — REPUBLICAN Governor Greg Abbott had ALREADY frozen new data center permits before the election!
So please, explain to me again how this is suddenly a Democrats-versus-AI story. 😂
Now let’s talk about what Wall Street seems to be forgetting.
According to CBRE, across North America’s eight largest data center markets:
📊 80.4% of capacity under construction is already preleased.
📊 Vacancy is just 1.4%.
📊 Construction capacity increased 24.8% in H1 2026.
Read those numbers again.
The industry is facing a serious shortage of deliverable capacity, not an obvious collapse in customer demand.
And here’s where things get really interesting.
What happens when demand remains strong but new supply becomes harder to build?
Existing facilities with secured power and permits can become MORE valuable.
Developers may move projects to other states or invest in upgrading existing infrastructure.
And companies capable of delivering reliable, on-site electricity could become increasingly important.
Of course, delays can hurt developers, postpone server orders and increase costs. I’m not ignoring those risks.
But let’s distinguish between a supply bottleneck and a demand collapse.
They’re not the same thing.
And politicians have powerful economic incentives to get this right: investment, jobs, tax revenue, energy infrastructure and America’s technological competitiveness.
Nobody wants households subsidizing billion-dollar data centers. Requiring developers to pay their fair share is entirely reasonable.
The question isn’t whether America needs AI infrastructure. It’s how, where and at whose expense it gets built.
The U.S. is competing for technological leadership. China isn’t going to stop building computing infrastructure while American politicians debate electricity bills.
And that brings me to my investment thesis.
I think Wall Street may be pricing a political permitting problem as if it were the end of the AI infrastructure boom.
That’s a very different risk.
And today, I decided to do a little shopping. 🛒
💻 $SMCI — Super Micro Computer: The servers and AI systems.
☁️ $CRWV — CoreWeave: The computing capacity.
⚡ $BE — Bloom Energy: The electricity needed to power it all.
Three businesses, three parts of the same infrastructure chain.
I see the current fear as an opportunity to build exposure to a long-term transformation, while keeping the execution risks firmly in mind.
You can delay a building permit. You can’t legislate away the need for computing power.
THE AI REVOLUTION ISN’T A RED OR BLUE PROJECT. IT’S AN AMERICAN INDUSTRIAL PROJECT. 🇺🇸🚀
🤖 Made with AI


Quantum Leopard retweeted
🚨 $OPEN — THE STOCK PRICE TELLS ONE STORY. INSTITUTIONAL FILINGS ARE STARTING TO TELL ANOTHER.
I find what’s happening with Opendoor increasingly interesting.
We’re only at the beginning of the Q3 2026 13F disclosure season. Many institutional investors haven’t reported their September 30 holdings yet.
But the early numbers are already worth paying attention to.
📊 Across the filings analyzed so far:
🟢 Approximately 5.6 MILLION shares added.
🔴 Approximately 850K shares reduced or sold.
🟢 NET: Nearly +4.8 MILLION SHARES.
And that’s AFTER accounting for the reported selling in this preliminary sample.
Daiwa Securities alone increased its position by approximately 4.4 million shares (+94%).
Sullivan Wood reported a new position of more than 500,000 shares.
Of course, some institutions have reduced their exposure. I’m not ignoring that. But the preliminary net balance remains positive, largely driven by a few significant buyers.
Now think about the contradiction.
If I looked only at the stock price, I’d think everyone was running for the exits.
But that’s not what these early ownership disclosures suggest.
And this brings me back to something I’ve been saying for a long time.
I strongly suspect that $OPEN is experiencing aggressive short pressure, algorithm-driven selling and repeated shakeouts that are testing the conviction of retail investors.
I cannot prove coordinated market manipulation from these filings alone. But I believe the disconnect between the price action and the underlying business deserves serious attention.
In my view, these violent moves are creating exactly the kind of environment in which frightened retail investors surrender their shares, while investors with deeper pockets may be quietly accumulating.
And here’s what makes this situation even more extraordinary.
While the stock price has been under pressure, I continue to see progress in Opendoor’s underlying business:
🟢 Acquisition activity and transaction volumes.
🟢 Resale execution and inventory turnover.
🟢 Operational efficiency and execution speed.
🟢 New products, technology releases and platform improvements.
🟢 A strengthening technological foundation and competitive positioning.
Month after month, I’m watching a company working to improve its operating engine, expand its capabilities and strengthen the technology behind its business.
Yet the market seems obsessed with the daily red candles.
I believe there’s a massive difference between a company whose fundamentals are deteriorating and a stock whose price is being relentlessly pressured.
And I suspect some sophisticated investors understand that difference perfectly.
Could larger players be accumulating shares while exhausted retail investors finally capitulate?
I think that’s a possibility worth taking very seriously.
The 13F disclosure season is far from over. I’ll continue tracking both purchases and sales, because the complete picture matters.
But the first signals certainly don’t look like the universal institutional exodus the stock price might lead people to believe.
I know what I’m holding.
I know what I’m watching.
And I’m not letting the daily price action define the entire investment thesis.
LONG $OPEN.
LONG OPENDOOR — THROUGH THE STORM. 🌪️
🤖 Made with AI

Quantum Leopard retweeted

We are very close to being able to open up Opendoor's scale advantage to everyone who wants to buy a home, whether that is an Opendoor home or not.
Quantum Leopard retweeted
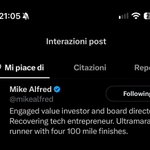
👀 @mikealfred , newly appointed to Opendoor’s Board of Directors, just liked my post about a potential $OPEN buyback.
I find that timing very interesting. 🚀
Long Opendoor — Through the Storm.

Quantum Leopard retweeted
If buying back $OPEN at $3.49 made sense, what does $1.80 represent today?
I’d love to hear management’s perspective. Has the thesis changed, or just the price?
Long Opendoor — Through the Storm 🌪️
@mikealfred @nejatian @rabois
Quantum Leopard retweeted
Congratulations @mikealfred on joining the Board of Directors of $OPEN
As a long-term shareholder, I’m excited about this appointment. Well deserved, Mike!
Long Opendoor — Through the Storm. 🚀

Quantum Leopard retweeted
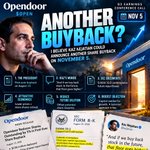
🚨 $OPEN — I BELIEVE @nejatian COULD ANNOUNCE ANOTHER SHARE BUYBACK ON NOVEMBER 5.
And after examining his public statements, SEC filings and Opendoor's capital structure, I believe the clues are too interesting to ignore.
This is not insider information. It is my personal investment thesis, built on publicly available documents and financial reasoning.
1. THE PRECEDENT: AUGUST 13, 2026
Opendoor announced its first-ever share repurchase:
• $158 million deployed
• 45.3 million shares repurchased
• $3.49 per share
• Approximately 5% of outstanding shares retired
The transaction was connected to a $650 million zero-coupon convertible financing, designed to support expansion while limiting shareholder dilution.
Kaz demonstrated something important: he was willing to use sophisticated financial structures to protect shareholder value.
2. THE WORDS THAT CAUGHT MY ATTENTION
Kaz has explicitly expressed the view that Opendoor should repurchase shares when its own stock represents one of the best uses of capital.
But another statement was particularly interesting:
“And if we buy back stock in the future, that floor goes higher.”
He was discussing the $10.38 threshold associated with the dilution protection structured into the August financing.
To me, the reference to future repurchases matters.
He wasn't announcing another buyback. But he was clearly contemplating the possibility.
3. THE SEC DOCUMENT MOST INVESTORS MAY HAVE MISSED
I examined Exhibit 10.2 of the August 13 Form 8-K, the Capped Call Confirmation.
Under its Method of Adjustment provisions, the agreement expressly contemplates:
• Future open-market share repurchases
• Accelerated Share Repurchases (ASRs)
• Forward repurchase arrangements
• Other qualifying transactions
The agreement also establishes specific treatment for qualifying additional repurchases within an aggregate threshold linked to 20% of the shares outstanding at the original transaction date.
And Section 8(e), Repurchase Notices, addresses repurchases carried out under Rule 10b5-1 trading plans.
Important distinction: this is NOT authorization to repurchase 20% of Opendoor. It is a contractual provision governing potential adjustments to the capped calls.
But the existing financing structure expressly accommodates the possibility of additional buybacks.
That deserves attention.
4. THE MATHEMATICS HAVE BECOME EVEN MORE INTERESTING
In August, Opendoor repurchased shares at $3.49.
Now consider a hypothetical share price of $2.
With $100 million:
At $3.49 → approximately 28.7 million shares.
At $2.00 → 50 million shares.
That represents approximately 74.5% more shares retired using exactly the same capital.
If Kaz believed the stock was attractive at $3.49, what does he think about the economics at substantially lower prices?
Of course, the underlying business outlook matters. A lower share price alone does not automatically justify a buyback.
But the capital allocation question becomes increasingly interesting.
5. THERE IS ANOTHER FACTOR: FUTURE DILUTION
Opendoor has substantial outstanding equity-based compensation awards, including performance-related RSUs.
Not all these awards will necessarily vest.
However, reducing future dilution is already a documented priority of Kaz's capital strategy.
A new repurchase program could potentially offset some future share issuance, rather than merely serve as a short-term market signal.
6. THE BIGGEST OBJECTION
Opendoor needs liquidity to acquire homes, expand its operations and execute its turnaround.
I cannot ignore that.
Capital deployed into buybacks is capital unavailable for other investments.
And the August transaction was structured around a convertible financing, not simply financed with excess operating cash.
That is why I am not necessarily predicting an immediate, massive open-market purchase.
A new board authorization, an opportunistic repurchase program or another structured capital transaction could be more plausible.
MY CONCLUSION
I see several pieces of a potentially significant puzzle:
Kaz has already executed a $158 million buyback.
He has explicitly contemplated future repurchases.
The August SEC agreements include mechanisms covering additional buybacks.
The economics of retiring shares become increasingly attractive at lower prices, provided the fundamental investment case remains intact.
And the company has an ongoing strategic reason to pay attention to dilution.
None of this proves that a new buyback will be announced on November 5. I have not found a public authorization for a second program.
But I believe the possibility deserves serious attention ahead of Q3 earnings.
I am watching the upcoming conference call not only for revenue, margins and acquisition growth, but also for one crucial question:
HOW WILL KAZ ALLOCATE CAPITAL TO MAXIMIZE LONG-TERM VALUE PER SHARE?
Could November 5 deliver another surprise?
My conviction in the long-term opportunity remains strong.
Long Opendoor through the storm. 🚀
$OPEN

Quantum Leopard retweeted
Thank you! Title acceptance is a great program and it tilts the world in favor of homeowners!
Quantum Leopard retweeted
$OPEN — THE PSYCHOLOGY OF HATING A STOCK YOU DON’T EVEN OWN.
What if some of Opendoor’s most aggressive critics aren’t short sellers, but people afraid they’ve missed an opportunity?
I’ve been reflecting on a phenomenon increasingly visible across X.
As attention around Opendoor ($OPEN) grows, I notice it under my posts and throughout the community.
I’m not talking about legitimate bearish arguments or criticism of fundamentals.
I’m talking about insults, childish provocations, and mockery from people who rarely present financial arguments.
Some follow every $OPEN discussion. A few have become my most loyal followers, generating engagement with every comment. I appreciate that. 😄
But something intrigues me.
Many don’t appear to hold short positions or benefit from Opendoor’s decline. Of course, I can’t verify their portfolios.
Why such hostility toward a stock they apparently don’t own?
Psychology offers fascinating explanations.
1. SOCIAL COMPARISON — LEON FESTINGER (1954)
People evaluate success partly by comparing themselves with others.
Imagine dismissing an investment, then watching someone else make substantial gains.
You haven’t lost a dollar.
Yet their success reminds you of what you missed.
Someone else’s financial gain becomes your psychological loss.
2. FOMO, REGRET & COGNITIVE DISSONANCE
FOMO usually describes investors chasing rising prices.
But what happens when FOMO becomes resentment?
Buying now might mean admitting you were wrong. Staying out means watching others profit.
You can reconsider your assumptions.
Or convince yourself everyone who invested is wrong and hope the stock collapses.
If it fails, the missed opportunity disappears. Your decision feels justified.
You don’t need the stock to make you money. You need it to stop making money for others.
3. MALICIOUS ENVY — WHEN SOMEONE ELSE’S FAILURE BECOMES YOUR VICTORY
Psychology distinguishes benign envy, which can motivate improvement, from malicious envy, which can involve wanting others to lose their advantages.
Someone who missed an opportunity can learn from it.
Or find relief in watching investors lose money.
Not because their finances improve, but because the uncomfortable comparison disappears.
They don’t necessarily want to win. They want those who acted when they didn’t to lose.
4. SCHADENFREUDE — THE PLEASURE OF WATCHING OTHERS FAIL
Schadenfreude describes satisfaction from another person’s misfortune.
Imagine someone with no apparent short position celebrating every red candle, mocking shareholders, and attacking bullish arguments without alternatives.
No financial reward. But potentially an emotional one.
A falling stock can reassure someone that staying out was the right decision.
These mechanisms don’t prove anyone’s motivations. Some enjoy trolling, and genuine skepticism isn’t envy.
DISAGREEMENT IS NOT HOSTILITY.
My bullish thesis on $OPEN could be wrong. I’ve never claimed otherwise.
I analyze acquisitions, resales, operations, valuations, market conditions, and strategy.
I present evidence and conclusions. Anyone can challenge my assumptions or offer coherent bearish arguments.
That’s what financial discussion should be about.
But insults aren’t analysis. Mockery isn’t due diligence. Repeating that someone is wrong isn’t demonstrating why.
What fascinates me is a possible third category:
The emotionally invested non-investor.
Someone with no financial exposure whose satisfaction may depend on seeing other investors fail.
An inverted FOMO: desperately wanting a missed opportunity to disappear.
No shares. No short position. No financial exposure.
Yet potentially an enormous emotional stake.
Some people aren’t betting against Opendoor with their capital.
They’re betting against it with their ego.
To my most dedicated critics: thanks for the engagement. 😄
I’ll keep bringing the analysis. You’re welcome to bring the evidence.
LONG $OPEN
🤖 Made with AI

Quantum Leopard retweeted
🚨 $OPEN — Q4 HOME RESALES ARE ACCELERATING. THE GAP WITH 2025 IS WIDENING.
Opendoor’s latest Accountable data reveal something important:
Q4 resale closings, YoY:
📈 Oct 7: +35.0% (185 vs. 137)
📈 Oct 14: +41.7% (394 vs. 278)
But here’s the real story:
Additional closings between the two updates:
2025: 141 homes
2026: 209 homes
🔥 +48.2% YoY incremental growth.
The gap isn’t just holding. It’s expanding.
And this is happening in a tougher housing market than last year.
Meanwhile, acquisition contracts remain +197% YoY, despite an 18% weekly pullback.
Opendoor isn’t just buying more homes. It’s closing more resales — and widening its lead over last year.
That’s the operational progress I’m watching.
LONG $OPEN


Quantum Leopard retweeted
I’ll be buying more $OPEN at the opening bell. I believe today’s ridiculous algorithm-driven pre-market selloff will be absorbed very quickly.

🚨 $OPEN — THEY SOLD THE DATE. THE RESULTS HAVEN’T EVEN ARRIVED.
Opendoor announces Q3 earnings for November 5, after the close.
No quarterly results.
No guidance cut.
No profit warning in that announcement.
Now look at the reaction.
October 19 regular close: $2.05.
After-hours low: $1.9315. −5.78%.
Last after-hours price: $1.9784. −3.49%.
At the low, OPEN was just 0.08% above its $1.93 annual low.
A reporting-date announcement. A trip back to the doorstep of the lowest price of the year.
Compare that with OPEN’s three preceding after-hours sessions:
October 14: −1.51%.
October 15: −0.86%.
October 16: −0.31%.
Monday’s final after-hours decline was 3.9 TIMES the average magnitude of those three moves.
And this wasn’t simply an extension of an equally violent sector-wide sell-off.
The same evening’s last available after-hours trades showed:
Zillow: +1.14%.
Rocket: +0.09%.
Better: +0.19%.
Homebuilder ETF ITB: unchanged.
Homebuilder ETF XHB: +0.16%.
Different businesses, different exposures—and trades recorded at different times. Still, nothing resembling OPEN’s slide toward its annual low.
Same evening. Same broad interest-rate environment. Very different treatment.
And spare me the automatic “Treasuries” explanation.
The relevant window starts at 4 p.m. ET, when after-hours begins. An earlier daily Treasury reading does not establish a fresh rates shock during that window.
The sector comparison shows no comparable housing-wide liquidation in those observations.
“Macro” needs to explain the divergence. It cannot just be a word we throw at every red candle.
Now look at what the announcement DID establish.
NOVEMBER 5 AFTER THE CLOSE: EARNINGS.
NOVEMBER 6: OPEN WEEKLY OPTIONS EXPIRE.
Those contracts have just one regular trading session after the results.
That matters to positioning, event risk and hedging. Traders can reassess exposure; dealers can adjust their share hedges.
But none of that requires a new conclusion about how many homes Opendoor sold or what margins it earned.
That is the distinction at the heart of this episode.
A change in the calendar of financial risk can trigger trading before any new operating information exists. In thinner after-hours conditions, automated execution and hedge adjustments can amplify the price impact.
Then the resulting chart gets treated as if investors have collectively discovered something terrible about the business.
What, exactly, did they discover in this release?
November 5.
My reading is that algorithms and positioning are exerting an outsized influence on OPEN, while actual investment analysis struggles to get a word in.
The scale of the move, the proximity to the annual low and the contrast with other housing names make that explanation worth serious scrutiny. They do not identify the sellers or establish manipulation.
My confidence in @nejatian remains high.
My willingness to confuse every sell order with an informed investment decision remains extremely low.
Show me weaker execution, deteriorating margins or a broken turnaround thesis, and I will analyse them.
Here, they sold a date.
Apparently the algorithms completed their due diligence.
They checked the calendar.
Long $OPEN .

Quantum Leopard retweeted
🚨 $OPEN — THEY SOLD THE DATE. THE RESULTS HAVEN’T EVEN ARRIVED.
Opendoor announces Q3 earnings for November 5, after the close.
No quarterly results.
No guidance cut.
No profit warning in that announcement.
Now look at the reaction.
October 19 regular close: $2.05.
After-hours low: $1.9315. −5.78%.
Last after-hours price: $1.9784. −3.49%.
At the low, OPEN was just 0.08% above its $1.93 annual low.
A reporting-date announcement. A trip back to the doorstep of the lowest price of the year.
Compare that with OPEN’s three preceding after-hours sessions:
October 14: −1.51%.
October 15: −0.86%.
October 16: −0.31%.
Monday’s final after-hours decline was 3.9 TIMES the average magnitude of those three moves.
And this wasn’t simply an extension of an equally violent sector-wide sell-off.
The same evening’s last available after-hours trades showed:
Zillow: +1.14%.
Rocket: +0.09%.
Better: +0.19%.
Homebuilder ETF ITB: unchanged.
Homebuilder ETF XHB: +0.16%.
Different businesses, different exposures—and trades recorded at different times. Still, nothing resembling OPEN’s slide toward its annual low.
Same evening. Same broad interest-rate environment. Very different treatment.
And spare me the automatic “Treasuries” explanation.
The relevant window starts at 4 p.m. ET, when after-hours begins. An earlier daily Treasury reading does not establish a fresh rates shock during that window.
The sector comparison shows no comparable housing-wide liquidation in those observations.
“Macro” needs to explain the divergence. It cannot just be a word we throw at every red candle.
Now look at what the announcement DID establish.
NOVEMBER 5 AFTER THE CLOSE: EARNINGS.
NOVEMBER 6: OPEN WEEKLY OPTIONS EXPIRE.
Those contracts have just one regular trading session after the results.
That matters to positioning, event risk and hedging. Traders can reassess exposure; dealers can adjust their share hedges.
But none of that requires a new conclusion about how many homes Opendoor sold or what margins it earned.
That is the distinction at the heart of this episode.
A change in the calendar of financial risk can trigger trading before any new operating information exists. In thinner after-hours conditions, automated execution and hedge adjustments can amplify the price impact.
Then the resulting chart gets treated as if investors have collectively discovered something terrible about the business.
What, exactly, did they discover in this release?
November 5.
My reading is that algorithms and positioning are exerting an outsized influence on OPEN, while actual investment analysis struggles to get a word in.
The scale of the move, the proximity to the annual low and the contrast with other housing names make that explanation worth serious scrutiny. They do not identify the sellers or establish manipulation.
My confidence in @nejatian remains high.
My willingness to confuse every sell order with an informed investment decision remains extremely low.
Show me weaker execution, deteriorating margins or a broken turnaround thesis, and I will analyse them.
Here, they sold a date.
Apparently the algorithms completed their due diligence.
They checked the calendar.
Long $OPEN .
Quantum Leopard retweeted
$OPEN — @mikealfred REPORTEDLY HOLDS 10.6 MILLION SHARES. DO YOU KNOW WHO HE IS?
Before dismissing his conviction in Opendoor, look at the man behind the investment.
Mike Alfred isn’t just another bullish personality on X.
He’s a Stanford graduate, serial entrepreneur, and investor known for identifying opportunities before they become mainstream.
HIS TRACK RECORD SPEAKS FOR ITSELF.
1. BRIGHTSCOPE — BUILT AND SOLD
In 2008, Alfred co-founded BrightScope with his brother Ryan, creating an independent rating system for US retirement plans.
The company was acquired by Strategic Insight in 2016.
His first major entrepreneurial exit.
2. DIGITAL ASSETS DATA — ANOTHER SUCCESSFUL EXIT
In 2018, Alfred co-founded Digital Assets Data, an institutional cryptocurrency data platform.
In November 2020, NYDIG acquired the company.
Two companies built. Two successful exits.
Not predictions. Actual businesses created and sold.
3. IREN — IDENTIFYING THE AI INFRASTRUCTURE OPPORTUNITY
When Bitcoin miners were considered speculative cryptocurrency businesses, Alfred recognized something deeper.
Electricity, land, grid connections, and physical infrastructure could become valuable in the AI era.
He reportedly began accumulating IREN around $2 per share and has discussed returns approaching 15x.
He’s served on IREN’s board since 2021.
He recognized the infrastructure opportunity before the AI narrative became mainstream.
4. ALPINE FOX CAPITAL — CONVICTION BACKED BY CAPITAL
Alfred founded Alpine Fox Capital in 2022.
His philosophy combines value investing with concentrated positions in businesses undergoing major transformations.
He has publicly described targeting 30–50% annualized returns over long periods, accepting substantial volatility.
His Q2 2026 reported US long holdings were approximately $211 million, including Cipher Mining, IREN, Bitcoin-related investments, and Opendoor.
NOW LOOK AT HIS REPORTED OPENDOOR EXPOSURE.
December 2025: 25,000 shares
February 2026: 1.6 million
March 2026: 1.67 million
June 2026: 4.73 million
September 2026: 8.1 million
September 20: 10.1 million
October 10: 10.6 MILLION SHARES
These figures combine institutional filings and public statements, not necessarily one account. October’s figure comes from a secondary report.
The progression is extraordinary.
And it happened amid selling pressure, high short interest, and negative sentiment toward Opendoor.
WHY DOES THIS MATTER TO ME?
Because I see a potential parallel between IREN and Opendoor.
With IREN, Alfred recognized that the market might be overlooking the strategic value of its infrastructure.
With Opendoor, I believe a similar question deserves attention.
Is Wall Street valuing OPEN merely as a struggling home-flipping company while overlooking its technology, proprietary data, transaction infrastructure, distribution network, and potential to transform residential real estate?
I don’t know whether Alfred shares that exact thesis.
But his reported exposure makes the question worth investigating.
HIS SUCCESS DOES NOT MAKE HIM INFALLIBLE.
Two successful exits and a major investment winner don’t guarantee another successful investment.
But experience matters. Capital allocation matters. Conviction backed by substantial exposure matters.
When someone who built and sold two companies, identified the AI infrastructure opportunity early, and manages a concentrated portfolio reportedly accumulates more than 10 million shares of Opendoor, I PAY ATTENTION.
Not because I blindly follow successful investors.
But because experienced capital can sometimes recognize opportunities the market overlooks.
The question isn’t whether Mike Alfred can be wrong. Of course he can.
The question is: WHAT DOES HE SEE IN OPENDOOR THAT THE MARKET DOESN’T?
I’m long $OPEN .
THROUGH THE STORM.
🤖 Made with AI

Quantum Leopard retweeted
IT’S NOT JUST A GREEN CANDLE. $OPEN
October 15: +16.58% close-to-close. Strongest daily gain since November 10, 2025.
From $1.93 to $2.35: +21.76%. The low-to-close recovery was +20.21%, the largest since November 7, 2025.
The standout is momentum.
Daily RSI(14, Wilder) jumped from 22.01 to 42.21: +20.20 POINTS. In my calculation on Yahoo’s daily history, that’s the largest one-session RSI increase since August 12, 2021.
Now look at the geometry.
The October 2 high was $2.53. The subsequent low was $1.93: a 23.72% drawdown.
Closing at $2.32 recovered 65% of that decline in ONE session, reclaiming its 61.8% retracement at $2.301.
The candle’s real body contains SIX previous daily bodies, on 2.16× the preceding 20-session average volume.
Price also closed above two descending trendlines:
• July 10 / October 9 highs.
• September 22 / October 2 highs.
The next battle is precisely defined: $2.37–$2.44.
Inside that zone:
• $2.370: 50% retracement of the September 22 downswing.
• $2.378–$2.388: 20-day SMA/EMA.
• $2.402: 78.6% retracement of the October 2 downswing.
• $2.434: 38.2% retracement of the September 3 downswing.
That’s a resistance cluster with several distinct anchors.
A sustained reclaim would bring $2.47–$2.53 into focus: the September 22 swing’s 61.8% retracement, the September 3 anchored VWAP and the October 2 high.
First area to defend on a retest: $2.21–$2.25.
Structural floor: $1.93.
Momentum confirmation still needed: RSI above 50.
A rare momentum impulse. A substantial retracement reclaimed. Two trendlines broken.
Now buyers have to turn that impulse into sustained trading above resistance.
LONG $OPEN through the storm!


